How Long Does a Settled Account Stay on CIBIL? (2026)
Understand the impact of settled accounts on your credit history and options available.
Anuj Anand Malik
Reviewed by AMA Legal Solutions
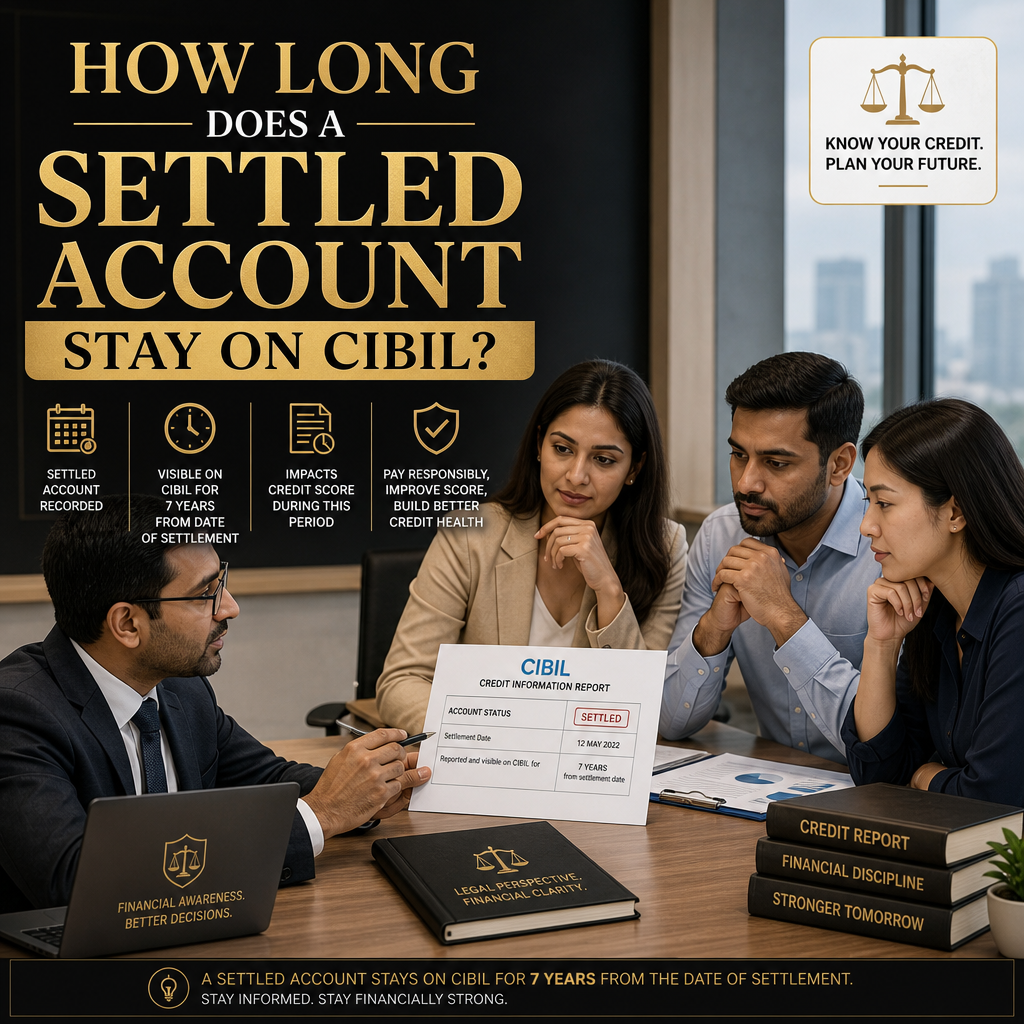
Key Takeaways: A settled account remains on your CIBIL report for a minimum of seven years from the date of settlement, as mandated by the Credit Information Companies Regulations, 2006. During this retention period, lenders can access your credit history, which may impact future credit decisions. To improve your creditworthiness, maintaining positive financial behavior after the settlement is crucial.
Introduction to How Long Does a Settled Account Stay on CIBIL?
When evaluating How Long Does a Settled Account Stay on CIBIL? in India, understanding the applicable statutory framework, legal procedures, and strategic rights is essential. Understanding how long a settled account stays on CIBIL is crucial for anyone aiming to maintain a good credit score and planning their financial strategy. In today's financial ecosystem, credit bureaus like TransUnion CIBIL play a pivotal role in shaping the creditworthiness of individuals. This importance is underscored when you settle a debt, potentially impacting your credit report for years.
In India, the retention of credit information, including accounts marked as 'settled', is governed by specific laws and regulations. Readers are keen to know how long does a settled account stay on CIBIL, and what this means for their financial future. This article aims to unravel these questions by shedding light on the statutory framework, practical implications, and strategic actions borrowers can embark upon.
Statutory Framework & Governing Legal Provisions
Before delving deeper into how long a settled account stays on CIBIL, it's essential to navigate through the statutory landscape that governs credit information in India. The primary legislation overseeing this domain is the Credit Information Companies (Regulation) Act, 2005 (CICRA). This Act, alongside the Credit Information Companies Regulations, 2006, guides the functioning of credit information companies like TransUnion CIBIL.
Retention Period Regulations: According to Section 10(d) of the Credit Information Companies Regulations, 2006, credit information related to defaults, late payments, and accounts marked as 'settled' must be retained for a minimum period of seven years. This period begins from the date of settlement, which ensures lenders have access to a comprehensive view of a borrower's credit history.
Data Update Obligations: Section 22 of the Credit Information Companies Rules, 2006 emphasizes that credit institutions must update credit information promptly. This is crucial where changes result from settlements or other arrangements, reinforcing accurate credit reporting.
Comprehensive Analysis & Practical Evaluation of a Settled Account
When exploring how long a settled account stays on CIBIL, it's vital to understand the impact this status can have on your credit report. A 'settled' status indicates that the borrower and lender agreed to resolve the outstanding debt for less than the full amount owed. This status can influence future credit decisions, as it shows a deviation from the initial credit agreement.
Typically, a settled account will remain on the CIBIL report for seven years from the date of settlement. During this period, the account's status serves as a historical marker of financial behavior, although its adverse impact on your credit score may lessen over time, especially with positive financial conduct thereafter.
For those contemplating changing a 'settled' status to 'closed', the following procedural steps are recommended:
- Contact the Lender: Initiate communication with the original lender to discuss the possibility of settling the remaining dues.
- Clear Outstanding Amounts: Pay the difference between the settled and the original outstanding amounts.
- Obtain a No Dues Certificate: Secure this certificate from your lender to confirm that no amounts are pending.
- Request an Update: Formally request your lender to update your account status with CIBIL as 'closed'.
- Monitor Your Credit Report: Regularly inspect your report to confirm that the updates have been accurately reflected.
It's pertinent to note that, while converting a 'settled' account to 'closed' can bolster creditworthiness, the original status can remain visible for seven years.
Key Insights & Data Infographic
Visual summary, statistical trends & procedural breakdown
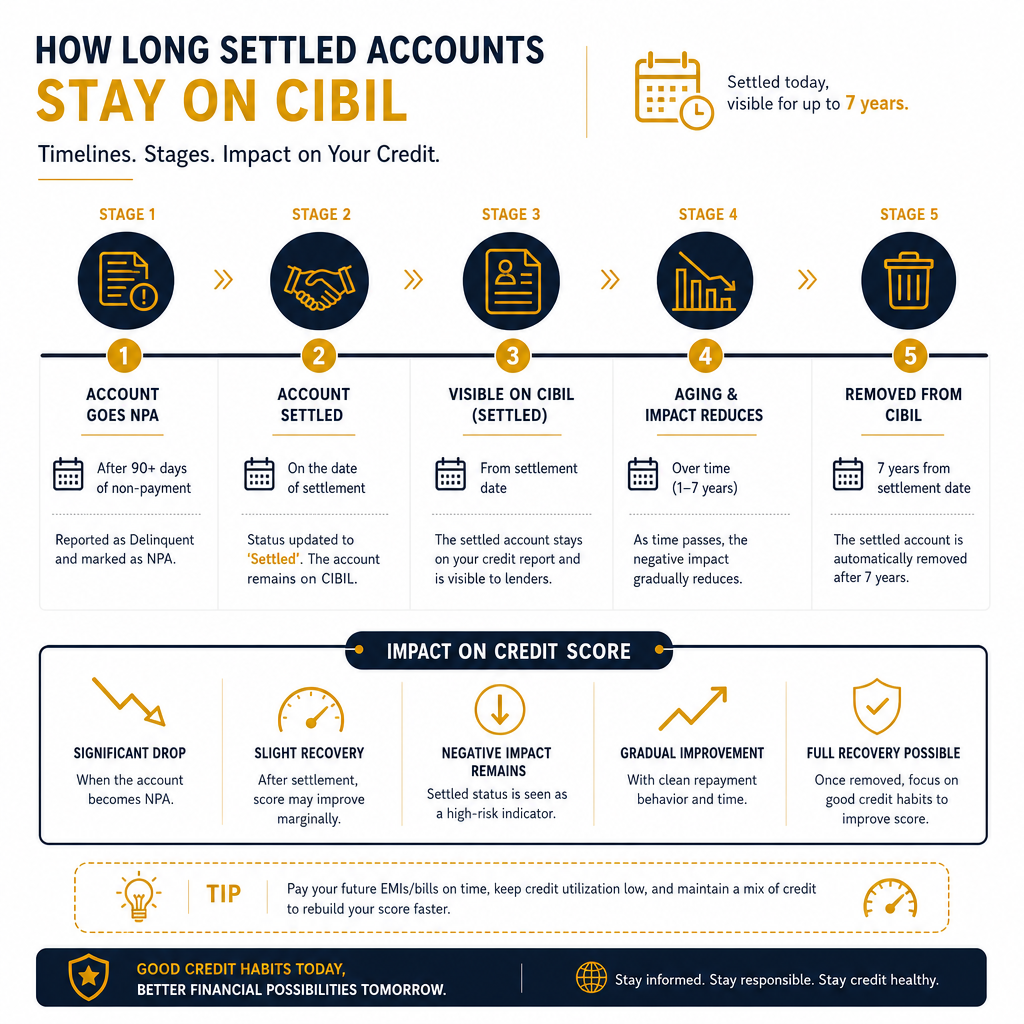
Prepared by AMA Legal Solutions Research & Analytics Team • Data & Compliance Overview

Halt Recovery Agent Harassment Legally
Comparative Parameters / Procedural Workflow Matrix for Settled Accounts
Let's explore how different actions and legal support can impact the process of handling a settled account and influencing its status on CIBIL.
| Parameter / Option | Legal Basis & Requirements | Key Procedures / Considerations | Strategic Advantage with Counsel |
|---|---|---|---|
| Initial Settlement | Agreement with Lender | Fulfill the terms of the settlement | Negotiate better terms |
| Updating Status to 'Closed' | Legal obligation to clear dues | Pay remaining dues and request update | Ensure compliance and accuracy |
| Dispute Resolution | Right to question inaccuracies | Lodge a dispute on CIBIL portal | Effectively present evidence and rectify errors |
| Credit Monitoring | Regular checks mandated | Frequent report assessment | Proactive rectification strategies |
Legal counsel can significantly streamline these processes, ensuring that all statutory requirements are met, thereby expediting the status update and minimizing negative impacts on your credit score.
Legal Safeguards, Consumer Rights, and Critical Risks to Avoid
Understanding how long a settled account stays on CIBIL also involves recognizing your legal rights and potential risks. Borrowers have the right to access their credit information and dispute any inaccuracies. Errors on your report could adversely affect your credit score and, therefore, your financial future.
If discrepancies are found, borrowers should immediately raise disputes via CIBIL's online platform or contact their lender to rectify errors. The Reserve Bank of India mandates that such concerns be addressed promptly to uphold the integrity of credit reporting.
Critically, borrowers must avoid agencies that promise quick fixes or unverified solutions for changing credit statuses. Instead, engaging reputable legal services ensures compliance and protects consumer rights.
Strategic Conclusion: Securing Legal Assurance with AMA Legal Solutions
In conclusion, understanding how long a settled account stays on CIBIL is imperative for anyone keen on maintaining a healthy credit profile. The retention period, set at seven years by regulatory norms, demands careful navigation through legal and procedural frameworks.
Engaging professional legal assistance from proficient law firms like AMA Legal Solutions offers the strategic advantage of expert advocacy. Their attorneys can navigate complex regulations, assist in dispute resolutions, and provide tailored legal advice rooted in the Advocate-client privilege under the Indian Evidence Act.
For personalized guidance and comprehensive credit management solutions, feel free to reach out to AMA Legal Solutions for a consultation. Their experienced team stands ready to help you achieve and maintain a robust credit history.
Popular Searches & Topics
Commonly searched legal queries and keywords related to this article
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.
AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages
Frequently Asked Questions
Related Articles
Can a Personal Loan Defaulter Go to Jail in India? (2026)
Understanding legal ramifications & safeguards for personal loan defaulters in India
Read Article
What Happens If You Miss Three Personal Loan EMIs?
Understand the consequences and legal options after missing three EMIs on your personal loan.
Read Article
How to Negotiate Credit Card Write-Off: A Practical Guide (2026)
Unlock effective strategies for negotiating credit card write-offs and reclaim financial control.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611