What Happens If You Miss Three Personal Loan EMIs?
Understand the consequences and legal options after missing three EMIs on your personal loan.
Anuj Anand Malik
Reviewed by AMA Legal Solutions
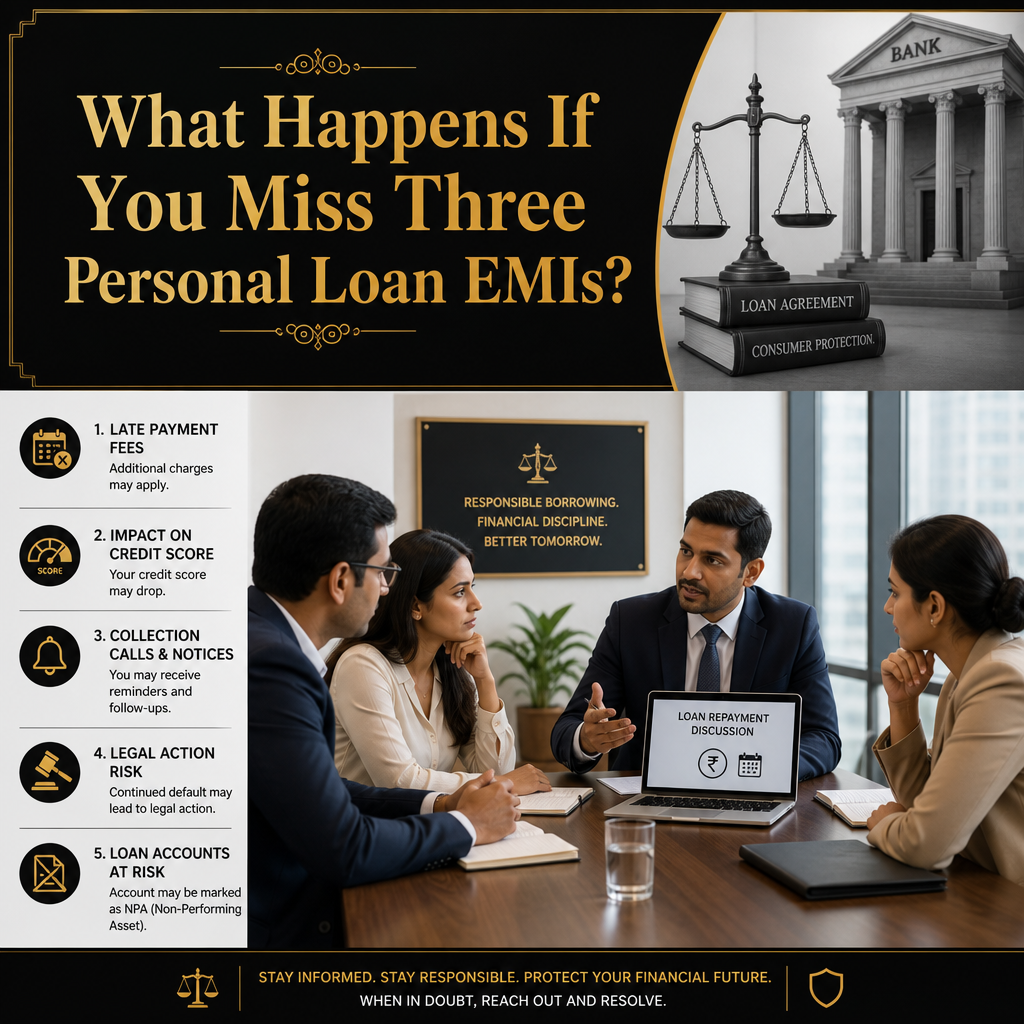
Key Takeaways: Missing three EMIs on a personal loan classifies the loan as a Non-Performing Asset (NPA), impacts your credit score significantly, and may lead to legal actions, including recovery proceedings. Proactive communication with lenders and exploring options such as debt restructuring can mitigate repercussions.
Introduction to Personal Loan EMIs in India
When evaluating What Happens If You Miss Three Personal Loan EMIs? in India, understanding the applicable statutory framework, legal procedures, and strategic rights is essential. Understanding what happens if you miss three personal loan EMIs is crucial for any borrower in India. This scenario often leads to a chain of escalating events that affect your financial standing, credit rating, and legal position. Personal loans are a popular financial tool in India due to their unsecured nature and easy accessibility. However, missing three consecutive EMIs can initiate serious consequences, compelling both legal and financial actions.
Statutory Framework & Governing Legal Provisions
Personal loans in India are governed by various laws and regulations. Notably, the Reserve Bank of India (RBI) plays a significant role in setting guidelines for loan classification and recovery. According to the RBI Master Circular on Prudential Norms, loans that are overdue for more than 90 days are classified as Non-Performing Assets (NPAs). When you miss three personal loan EMIs, the lender is required to initiate specific recovery measures, potentially involving legal actions under the SARFAESI Act or the Civil Procedure Code for unsecured loans.
Consequences of Missing Three Personal Loan EMIs
Missing three personal loan EMIs triggers multiple consequences:
- Loan Classified as NPA: Your loan account may be classified as an NPA if EMIs remain unpaid for 90 days.
- Credit Score Impact: Significant negative impact on your credit score is likely, affecting future borrowing capabilities.
- Legal Actions: Lenders may resort to legal notices and recovery proceedings to recover dues.
- Increased Financial Liabilities: Additional penalties and interest increase the overall debt burden.
These repercussions underline the importance of understanding what happens if you miss three personal loan EMIs and taking proactive measures to prevent such outcomes.
Practical Steps to Take After Missing EMIs
If you find yourself in a situation where you've missed three personal loan EMIs, consider the following steps to mitigate adverse effects:
- Contact Your Lender: Open communication channels with your lender to discuss possible solutions.
- Negotiate Repayment Plans: Work on renegotiating the terms to make repayments manageable.
- Seek Professional Advice: Utilize services like credit counseling to better manage financial obligations.
- Reply to Bank Legal Notices appropriately to prevent escalation.
Key Insights & Data Infographic
Visual summary, statistical trends & procedural breakdown
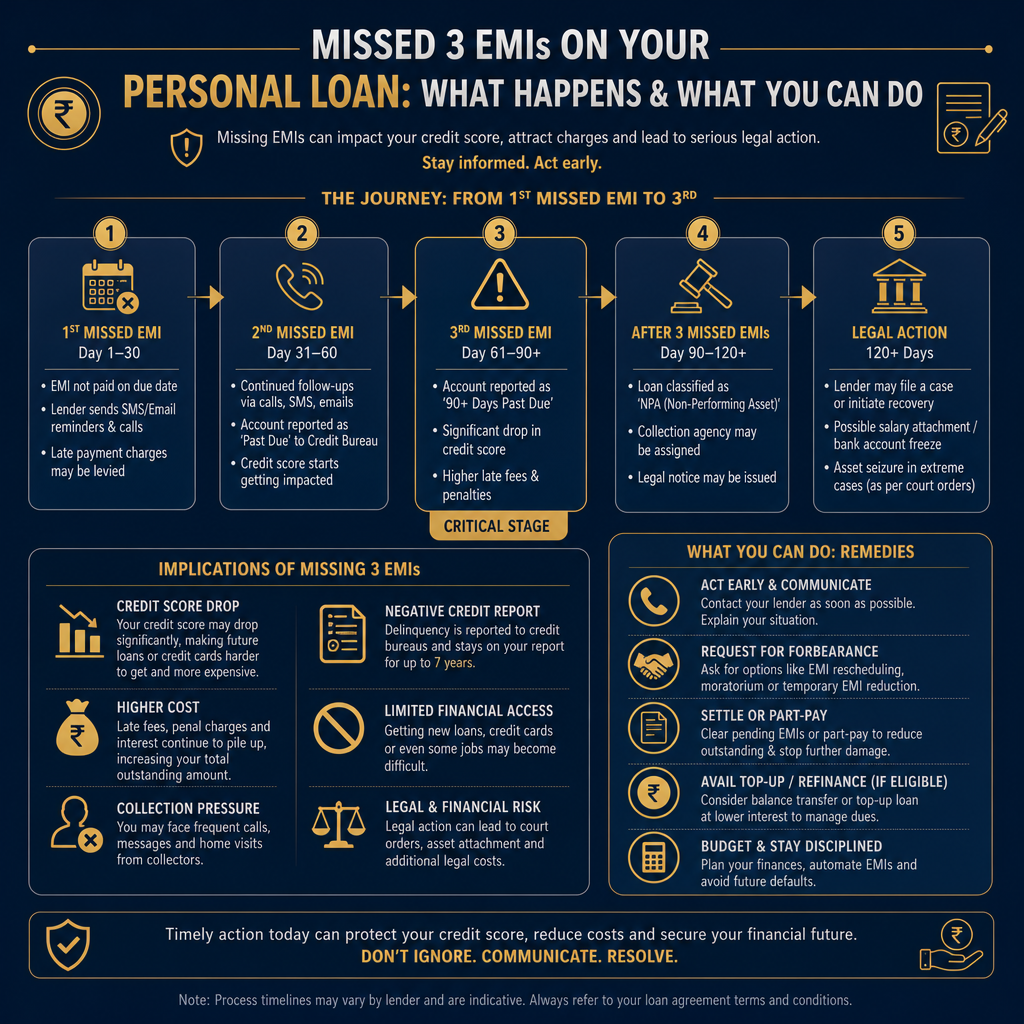
Prepared by AMA Legal Solutions Research & Analytics Team • Data & Compliance Overview

Halt Recovery Agent Harassment Legally
Options Available to Borrowers in Default
Once you comprehend what happens if you miss three personal loan EMIs, exploring available options becomes crucial. Borrowers can resort to debt restructuring programs, engage in credit counseling, or look for one-time settlement offers. Each option requires diligent assessment to avoid adverse impacts on one's credit and financial health.
Understanding Legal Notices and Their Implications
Receiving a legal notice is a common consequence when you miss three personal loan EMIs. This formal communication outlines the due payments and potential legal actions if dues are not cleared. Ignoring such notices can lead to litigation. It’s essential to understand the implications thoroughly and respond aptly, often involving engaging a lawyer for better guidance and handling.
Strategies for Loan Negotiation and Settlement
To minimize the damage of missing three personal loan EMIs, borrowers may negotiate new terms or settle through lump-sum payments. While these negotiations can relieve pressure, it is often beneficial to have professional representation for strategic advice. Legal firms are better positioned to ensure fair and legally sound settlements compared to agencies.
Legal Safeguards, Consumer Rights, and Critical Risks to Avoid
Understanding what happens if you miss three personal loan EMIs includes recognizing borrower rights and legal safeguards. The RBI mandates fair practices in loan recovery, providing avenues to contest undue recovery techniques. Critical risks include ignoring lender communications and accumulating more penalties. Engage with grievances channels and know your rights against harassment from recovery agents.
| Delinquency Stage | Time Frame | Legal Outcome | Financial Impact |
|---|---|---|---|
| Initial Delinquency | 1-30 Days Overdue | Minimal legal action | Minor penalties |
| Extended Delinquency | 31-90 Days Overdue | Heightened legal notices | Higher penalties; credit report hits |
| NPA Classification | Beyond 90 Days | Possible legal proceedings | Substantial penalties; credit score damaged |
Conclusion: Securing Legal Assurance with AMA Legal Solutions
Recognizing what happens if you miss three personal loan EMIs is vital for mitigating financial and legal repercussions in India. It's imperative to act promptly by either restructuring loan terms or addressing legal notices correctly. Given the potential complexities, enlisting the support of a trusted legal advisor such as AMA Legal Solutions can guide you through the process efficiently. Our firm offers informed insights and representation, ensuring that you navigate these challenges effectively.
When you miss three personal loan EMIs, the paths you take can protect your financial interests. Engage with AMA Legal Solutions today for expert legal assistance tailored to your specific situation.
Popular Searches & Topics
Commonly searched legal queries and keywords related to this article
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.
AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages
Frequently Asked Questions
Related Articles
How Long Does a Settled Account Stay on CIBIL? (2026)
Understand the impact of settled accounts on your credit history and options available.
Read Article
Can a Personal Loan Defaulter Go to Jail in India? (2026)
Understanding legal ramifications & safeguards for personal loan defaulters in India
Read Article
How to Negotiate Credit Card Write-Off: A Practical Guide (2026)
Unlock effective strategies for negotiating credit card write-offs and reclaim financial control.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611