Mastering Loan Settlement of Personal Loan by Bajaj Finance
Navigate Bajaj Finance Loan Settlements with Expert Legal Insights

Anuj Anand Malik
Reviewed by AMA Legal Solutions
Key Takeaways: Settling a personal loan with Bajaj Finance involves strategic negotiation to reduce debt repayment while understanding its credit implications. Initiate talks early to secure favorable terms, document everything, and seek legal advice to protect rights. RBI and Indian Contract Act regulations guide fair practices, enabling borrowers to challenge unfair recovery. Legal recourse through Banking Ombudsman and courts can aid in securing equitable outcomes.
Understanding Loan Settlement with Bajaj Finance: Key Considerations
Settling a personal loan with Bajaj Finance requires strategic planning and an understanding of the financial implications. Loan settlement is not just about paying off your debt; it involves negotiating a reduced amount that the lender accepts as full and final payment. This process can significantly affect your credit score, and it’s crucial to understand the nuances involved.
Why Consider Loan Settlement?
Loan settlement is often considered when a borrower is severely financially strained and unable to repay the loan in full. It provides a way to avoid prolonged financial distress and potential legal actions. However, it should be approached with caution as settled accounts are reflected negatively on your credit report.
When to Initiate Settlement?
Initiating settlement discussions typically happens after default. It’s advisable to contact Bajaj Finance before recovery agents become involved. Proactive communication can sometimes lead to more favorable settlement terms. Early negotiation is key to reaching a mutually beneficial agreement.
How to Approach the Settlement Process?
- Gather all relevant loan documents and understand your current financial situation.
- Contact Bajaj Finance directly to discuss settlement options. It's essential to document all communications in writing.
- Consider seeking professional legal advice to ensure the settlement terms are fair. For specialized assistance, visit our Loan Settlement Services page.
For borrowers under significant financial stress, consulting with a legal expert can provide clarity and ensure that your rights are protected throughout the process. For more insights into the legal landscape of loan settlements, explore our Banking and Finance Law services.
Legal Framework for Personal Loan Settlements in India
The legal framework governing personal loan settlements in India, particularly with institutions like Bajaj Finance, is primarily shaped by the Reserve Bank of India (RBI) guidelines and the Indian Contract Act, 1872. The RBI provides directives that ensure borrowers’ rights are protected while enabling financial institutions to recover dues justly.
Key Regulatory Guidelines
- Reserve Bank of India (RBI) Guidelines: The RBI mandates banks and financial institutions to adopt fair practices while dealing with defaulters. They must follow a structured approach to loan settlements.
- Indian Contract Act, 1872: This Act underpins the legality of agreements between borrowers and lenders. Loan settlements are essentially contracts, requiring mutual consent and clear terms.
Legal Recourse and Rights
Borrowers possess significant rights, including the ability to challenge unfair recovery practices. Legal recourse is available through forums such as the Banking Ombudsman and Consumer Courts. It's crucial for borrowers to understand that while loan settlements can impact credit scores, they provide a legitimate path to financial stability.
For a deeper legal understanding, borrowers may explore Banking and Finance Law services that offer specialized counsel in navigating complex settlement negotiations effectively.
Bajaj Finance Settlement Process: Step-by-Step Guide
The loan settlement process for a personal loan with Bajaj Finance involves a series of carefully structured steps to ensure a mutually beneficial resolution. Below is a detailed guide to help you navigate through this process efficiently.
Step 1: Initiate Communication
It's crucial to contact Bajaj Finance proactively as soon as you face difficulties in repaying your loan. This initial communication can set the tone for a positive negotiation process.
Step 2: Submit a Settlement Request
Prepare a formal request letter detailing your financial hardship and proposing a potential settlement offer. Ensure to include supportive documents such as payslips or termination letters.
Step 3: Negotiate Terms
Engage with the Bajaj Finance team to discuss and negotiate the terms of the settlement. Be open but firm about what you can realistically afford to pay.
Step 4: Finalize Agreement
Once both parties agree on the terms, make sure to document the settlement agreement in writing, specifying the amount, timelines, and other critical details.
| Parameter / Criterion | Key Details / Legal Provision | Timeline / Practical Impact |
|---|---|---|
| Initial Communication | Contact Bajaj Finance to discuss repayment issues | Start immediately upon financial difficulties |
| Settlement Request | Submit a formal request with supporting documents | Within 7-14 days of initial contact |
| Negotiation | Discuss and agree on feasible terms | Can take 2-4 weeks, depending on complexity |
| Final Agreement | Document the agreed settlement terms | Finalized within 1 week after negotiation |
Step 5: Payment Execution
Adhere to the payment schedule as agreed in the settlement. Timely payments can help improve your credit score over time. For more details on managing debt, consider exploring our Debt Consolidation & Restructuring services.
Negotiation Strategies: How to Approach Bajaj Finance
Successfully negotiating a settlement with Bajaj Finance requires a strategic approach, grounded in understanding the company's policies and being prepared. Begin by assessing your financial situation comprehensively. Knowing your financial limits will help you propose a realistic settlement amount.
Reach out to Bajaj Finance through their official communication channels and request to speak with the loan settlement department. It's essential to present a genuine explanation for your inability to continue regular payments. For instance, you might discuss how unexpected medical expenses or job loss have affected your finances. Emphasize your willingness to resolve the debt amicably, possibly suggesting a lump-sum payment or structured installments.
Key Points to Discuss
- Explain your situation clearly and honestly.
- Propose a realistic and mutually beneficial settlement amount.
- Be open to counteroffers, showing flexibility while staying within your financial capabilities.
- Seek written confirmation of any agreement reached to avoid future discrepancies.
Understanding Loan Settlement Services can provide deeper insights into the process. Additionally, familiarizing yourself with Banking and Finance Law helps you understand your rights and obligations.
Remember, patience and persistence are key. Bajaj Finance may not immediately accept your first offer, but with careful negotiation, you can work towards a favorable outcome.
Rights and Obligations of Borrowers: What You Need to Know
When engaging in a loan settlement with Bajaj Finance, it is crucial for borrowers to understand their rights and obligations. As a borrower, you have the right to be treated with respect and dignity, and lenders are required to follow fair practices set forth by the Banking and Finance Law. This includes receiving clear information about the settlement process and having any queries addressed promptly.
Borrowers have the obligation to communicate openly with the lender, providing accurate financial information when negotiating settlements. This transparency helps in assessing the ability to pay and formulating a viable settlement plan. Additionally, borrowers should be aware of their right to seek legal assistance, ensuring that any settlement agreement is fair and legally sound.
Key Rights of Borrowers
- Receive clear and accurate information about loan terms and settlement options.
- Be free from harassment by recovery agents, as outlined in Legal Rights Against Recovery Agent Harassment.
- Access to dispute resolution mechanisms if disagreements arise.
Borrower Obligations
- Timely communication with lenders to discuss financial difficulties.
- Honest sharing of financial status to reach a feasible settlement.
- Adherence to the terms agreed upon during the settlement process.
Understanding these rights and obligations not only empowers borrowers but also facilitates smoother negotiations, leading to successful outcomes in loan settlements.
Common Mistakes in Loan Settlements and How to Avoid Them
When it comes to the loan settlement of personal loan by Bajaj Finance, borrowers often make errors that can prolong the process or result in unfavorable terms. Understanding these pitfalls is crucial for a successful negotiation and settlement.
Overlooking Detailed Documentation
Many borrowers fail to maintain comprehensive records of their communications and agreements with Bajaj Finance. It's vital to document every step, including emails, official letters, and phone conversations. This ensures accountability and helps resolve disputes quickly.
Ignoring the Importance of Communication
Effective communication with Bajaj Finance is essential. Borrowers who avoid discussions or miss opportunities to negotiate may find themselves with less favorable terms. Engage actively and professionally with bank representatives to explore all possible solutions.
Inadequate Financial Assessment
Some borrowers rush into settlement without thoroughly assessing their financial situation. Calculate your income, expenses, and potential savings to present a realistic repayment plan. This knowledge empowers you to negotiate terms that are manageable.
- Never underestimate the role of timely payments during negotiations. Commit to a feasible payment plan that you can adhere to.
- Avoid making verbal agreements without written confirmation. Always request formal documentation from Bajaj Finance for any settlement terms.
- Seek professional assistance if necessary. Engaging with experts in banking and finance law can provide valuable insights and strengthen your position during negotiations.
By avoiding these common mistakes and being proactive in your approach, you can improve your chances of a successful loan settlement with Bajaj Finance.
Key Insights & Data Infographic
Visual summary, statistical trends & procedural breakdown
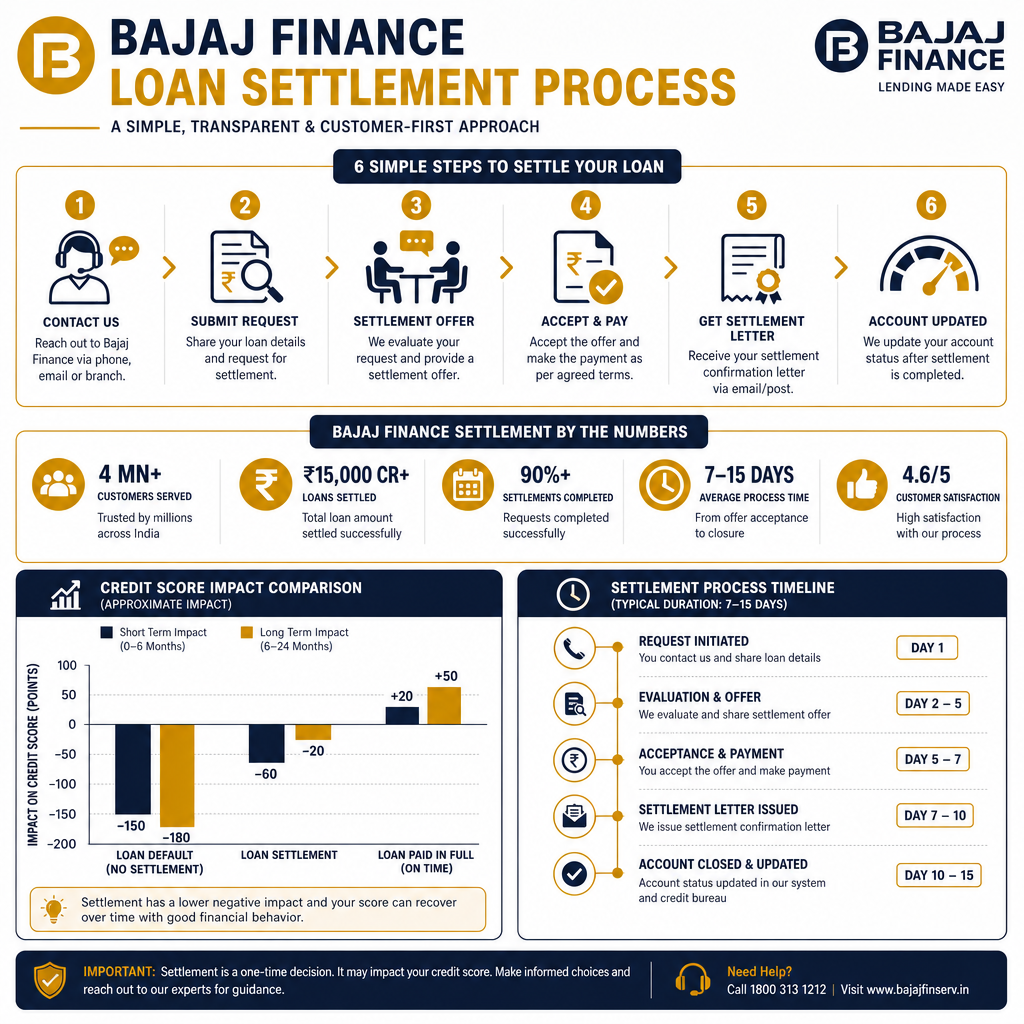
Prepared by AMA Legal Solutions Research & Analytics Team • Data & Compliance Overview
RBI Guidelines on Loan Settlements: What Borrowers Must Know
For Indian borrowers, understanding the Reserve Bank of India's (RBI) guidelines on loan settlements is crucial, especially when dealing with institutions like Bajaj Finance. The RBI provides a framework for fair and transparent loan settlement processes, ensuring borrowers' rights are protected.
One of the primary considerations is the RBI's directive that financial institutions must communicate all terms clearly, avoiding any hidden charges. This transparency helps borrowers make informed decisions.
Key Points to Remember
- One-Time Settlement: This is a popular option, where a borrower pays a lump sum amount less than the total outstanding to settle the debt. The RBI allows such settlements but mandates that they must be offered without coercion.
- Asset Classification: The RBI guidelines state that once a loan is settled, it should be reflected in the borrower's credit report as settled, not as a write-off, unless explicitly agreed upon.
- Grievance Redressal: Borrowers should utilize the internal grievance redressal mechanisms of financial institutions if they feel the settlement process was unfair. If unresolved, they can approach the Banking Ombudsman.
For those facing challenges, it may be beneficial to consult with experts specializing in Loan Settlement Services or seek advice on Banking and Finance Law to explore all available settlement options and rights.
Structured Table: Comparison of Legal Remedies vs Loan Settlement Procedures
Understanding the difference between legal remedies and loan settlement procedures is crucial for borrowers considering resolving their loan issues with Bajaj Finance. This comparison outlines the key aspects of each approach to assist borrowers in making informed decisions. Whether opting for Loan Settlement Services or pursuing legal avenues under Banking and Finance Law, clarity on these options ensures better decision-making.
| Parameter / Criterion | Key Details / Legal Provision | Timeline / Practical Impact |
|---|---|---|
| Initiation Process | Legal remedies typically involve filing a lawsuit or arbitration, requiring legal counsel. Loan settlement involves direct negotiation with Bajaj Finance for a reduced lump sum payment. | Legal actions can take months to years, while settlements might conclude within weeks to months depending on negotiation success. |
| Cost Implications | Legal processes often involve court fees and attorney costs. Settlements usually involve paying a negotiated amount, potentially saving on legal fees. | Legal costs are incurred throughout the duration, while settlement costs are typically a one-time payment. |
| Impact on Credit Score | Legal outcomes can lead to negative credit reporting if the judgment is unfavorable. Successful settlement can prevent further negative credit reporting. | Legal judgments could have a long-lasting impact, whereas settling can help stabilize credit faster with responsible future credit behavior. |
| Risk and Uncertainty | Legal proceedings carry risk and uncertainty due to potential unfavorable rulings. Settlements offer more predictable outcomes as they are mutual agreements. | Uncertainty persists until legal resolution, whereas settlement finalizes terms and conditions effectively. |
Borrowers must weigh these factors carefully to decide between pursuing a legal remedy or settling their personal loan with Bajaj Finance. Professional advice may also be sought from experts in Arbitration and Dispute Resolution to navigate these options effectively.
Case Studies: Successful Loan Settlements with Bajaj Finance
Understanding real-world applications can greatly demystify the loan settlement process. Below are a few case studies of successful loan settlements with Bajaj Finance, illustrating practical approaches and outcomes.
Case Study 1: Business Owner Facing Cash Flow Issues
A business owner from Chennai, struggling with cash flow issues, approached Bajaj Finance for a personal loan settlement. After negotiating, they agreed on a one-time settlement amount that was 30% lower than the outstanding balance. This agreement eased the financial burden without affecting the business's operations. This case exemplifies the importance of early communication and negotiation skills. For individuals facing similar challenges, exploring Loan Settlement Services can offer strategic solutions.
Case Study 2: Salaried Individual with Unexpected Medical Expenses
A salaried employee in Mumbai encountered unforeseen medical expenses, making timely loan repayments unmanageable. By presenting detailed financial statements and medical bills to Bajaj Finance, the individual negotiated a reduced settlement amount. This outcome highlights how providing clear evidence of financial hardship can facilitate favorable terms. Those interested in similar resolutions can consult our Banking and Finance Law experts.
These case studies underscore the effectiveness of proactive communication and documentation in achieving successful settlements. Borrowers should always aim to communicate clearly with financial institutions and consider professional advice when negotiating settlements.
How to Handle Recovery Agents Legally and Effectively
Dealing with recovery agents can be daunting but understanding your legal rights can help manage the situation more effectively. The Loan Settlement Services you engage with should inform you about your rights. According to RBI guidelines, recovery agents must respect the borrower's dignity and privacy. They should only contact you between 7 AM and 7 PM, and must not resort to harassment, intimidation, or abusive language.
What to Do When Contacted by a Recovery Agent
- Stay calm and composed. Do not panic or show aggression.
- Politely ask for the agent’s identity and verify their credentials.
- Request all communication to be done via email for documentation purposes.
- Clearly state your financial situation and propose realistic repayment plans if you are currently working towards settlement.
- If you feel threatened or harassed, report the matter to both Bajaj Finance and the local police authorities.
It is crucial to know that recovery agents cannot confiscate your personal property without following due legal process. If negotiations are ongoing and you are seeking a Debt Consolidation & Restructuring option, inform the recovery agents to pause their actions and provide them with necessary documentation of your negotiations.
Internal Classification of NPAs by Bajaj Finance: Insights
Bajaj Finance, like other financial institutions, adheres to regulatory guidelines to classify Non-Performing Assets (NPAs). An NPA typically arises when a borrower fails to make scheduled payments for a specified period, often 90 days. However, the internal classification can be more nuanced, impacting the possibility and terms of a loan settlement.
Stages of NPA Classification
The classification of NPAs is generally divided into different stages, each reflecting the duration of default and the risk associated with the loan:
- Sub-Standard Assets: Loans overdue for more than 90 days. Bajaj Finance may initiate recovery actions, but settlement options can be explored at this stage.
- Doubtful Assets: Defaults that extend beyond 12 months. The risk increases, making it crucial for borrowers to consider debt consolidation or settlement strategies.
- Loss Assets: Loans identified as non-recoverable by Bajaj Finance or auditors. Although challenging, settlements are still negotiable under specific conditions.
Understanding these classifications is vital as they influence the lender's approach to recovery and settlement negotiations. Borrowers should actively engage with Bajaj Finance to discuss possible solutions early in the NPA lifecycle. This proactive approach can lead to more favorable settlement terms, reducing financial strain and minimizing credit score impact.
Practical Tips for Enhancing Your Settlement Offer
Maximizing the potential of your loan settlement offer with Bajaj Finance begins with understanding the dynamics and strategically positioning yourself. Here are expert tips that can significantly influence the negotiation process:
Understand Your Position
Before engaging in negotiations, assess your financial situation thoroughly. This self-awareness not only supports your case but also helps Bajaj Finance grasp your genuine constraints. Document your income, expenses, and any financial hardships to create a compelling narrative.
Negotiate Professionally
Approach negotiations with professionalism and clarity. While it is crucial to express your difficulties, maintaining a respectful tone ensures a constructive dialogue. Consider enlisting the aid of a legal expert to advocate on your behalf, enhancing the credibility of your proposal.
- Be Honest: Transparency about your financial struggles can aid in building trust.
- Offer a Lump Sum Payment: If possible, propose a lump sum payment as it may lead to more favorable terms.
- Highlight Past Payment History: If you have a history of timely payments, use it to bolster your credibility.
Lastly, familiarize yourself with Bajaj Finance’s policies and past settlement trends. This knowledge can provide valuable insights and leverage during negotiations, ultimately improving the terms of your settlement offer.
Popular Searches

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages
Client Reviews
"AMA Legal Solutions demonstrated exceptional professionalism. Their expert advice on loan settlements was invaluable."
Neha Gupta
"I highly recommend AMA Legal Solutions for their thorough understanding of banking law. They helped me navigate a complex settlement effectively."
Priya Mehra
"AMA Legal Solutions provided excellent guidance on settling my loan with Bajaj Finance. Their expertise made the process smooth and stress-free."
Rohit Sharma
"Great service from AMA Legal Solutions! They provided clear guidance and helped me resolve my financial issues efficiently."
Vikram Iyer
"The legal team at AMA was incredibly supportive and knowledgeable. They negotiated a fair settlement on my behalf with Bajaj Finance."
Ajay Patel
Frequently Asked Questions
Related Articles

How to Trust Law Associates for Loan Settlement
Ensure Successful Loan Settlement with Trusted Legal Experts
Read Article
Expert Loan Settlement Lawyer: Minimize Amount, Maximize Waiver
Unlocking the Secrets to Successful Loan Settlements in India
Read Article
Loan Settlement of Personal Loan by IDFC Bank: A Comprehensive Guide
Navigate IDFC Bank Loan Settlements with Expert Legal Insights
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Help?
Get expert advice on loan settlement and debt relief.
Call +91-8700343611Request Callback