Mastering Loan Settlement with Axis Bank: A Legal Guide
Navigate the complexities of Axis Bank's personal loan settlements effectively.
Anuj Anand Malik
Reviewed by AMA Legal Solutions
Key Takeaways: Successfully negotiating a loan settlement with Axis Bank involves understanding your financial hardship, presenting a compelling case, and adhering to RBI guidelines. It’s crucial to document the settlement terms, consider the impact on your credit score, and protect yourself from unethical recovery practices by leveraging consumer rights.
Understanding Personal Loan Settlements with Axis Bank
When facing financial distress, negotiating a personal loan settlement with Axis Bank can be a viable option. A loan settlement allows borrowers to pay a lump sum that is typically less than the outstanding balance. This process requires strategic communication and comprehensive knowledge of your financial situation.
To initiate a settlement, communicate directly with Axis Bank's loan recovery department. It's crucial to present a compelling case detailing your financial hardship, such as loss of income or medical emergencies. Be prepared to provide documentation that supports your claim. Understanding your legal rights during the settlement process is essential to avoid common pitfalls.
Step-by-Step Guide to Settlement
- Review your loan agreement to understand the terms and conditions.
- Contact Axis Bank's loan settlement division and express your intent to settle.
- Negotiate the settlement amount, ensuring it's within your financial capability.
- Once agreed, request a written confirmation of the settlement terms.
- Make the payment through an official channel, and retain the receipt for your records.
Remember, a settlement might impact your credit score. For personalized guidance, consider consulting with a professional in Banking and Finance Law to maximize your settlement's effectiveness while minimizing negative repercussions on your credit profile.
Legal Framework Surrounding Loan Settlements in India
The legal framework for loan settlements in India is primarily governed by the guidelines issued by the Reserve Bank of India (RBI). These guidelines mandate that banks, including Axis Bank, evaluate each case based on the borrower's financial capacity and the merit of the situation. This ensures a fair assessment and customized settlement offer.
RBI Guidelines and Compliance
The RBI has laid down comprehensive norms to ensure transparency and fairness in the process. Banks are required to follow due process, which includes providing a legal notice to the borrower, outlining the details of the outstanding loan and available settlement options. This notice plays a critical role in initiating the settlement process.
- Banks must engage in fair negotiation practices and offer settlements based on genuine financial difficulties faced by borrowers.
- The terms of the settlement should be documented in writing to prevent future disputes.
Consumer Protection Act
The Consumer Protection Act also offers a safeguard for borrowers against unethical recovery practices. Borrowers can lodge complaints with consumer courts if they feel their rights have been violated. For detailed assistance, consider our Banking and Finance Law services.
Understanding these legal nuances can significantly aid borrowers in navigating the complex landscape of loan settlements effectively.
How Axis Bank Approaches Loan Settlements
Axis Bank has a structured process for handling loan settlements, providing borrowers with avenues to resolve outstanding dues amicably. The bank's primary goal is to recover dues while maintaining a positive relationship with customers. Typically, Axis Bank initiates contact with borrowers facing difficulties through their recovery management team. They offer negotiation options based on the borrower's financial situation and the amount overdue.
Negotiation and Settlement Offers
Axis Bank often proposes settlement offers that might include waiving a portion of the interest or principal amount, depending on the borrower's financial distress and payment history. This approach not only enables borrowers to clear their loans but also helps in maintaining their creditworthiness. Borrowers can understand these offers better by exploring our Loan Settlement Services page.
Legal and Financial Considerations
Before finalizing any settlement, Axis Bank assesses the borrower's repayment capacity and any legal implications. They adhere to RBI guidelines ensuring that all settlements are within legal frameworks. This careful consideration is crucial to ensuring a fair settlement process. Find more on our Banking and Finance Law page for detailed legal insights.
It's important for borrowers to communicate openly with Axis Bank's representatives, provide accurate financial information, and consider seeking legal advice to ensure the best possible outcomes. Understanding the various nuances of settlement can prevent future financial complications.
Key Factors Influencing Settlement Offers
The settlement offer for a personal loan by Axis Bank is influenced by several pivotal factors that borrowers should understand. Recognizing these can significantly enhance your negotiation position and lead to a more favorable outcome.
Current Financial Situation
Your current income, liabilities, and overall financial health play a crucial role. Banks assess if you genuinely lack the means to repay. Transparency about employment status, unexpected expenses, or health issues can impact their assessment.
Loan Amount and Tenure
The outstanding loan amount and how long it has been overdue are critical. Larger sums with prolonged defaults might prompt stricter settlement terms. Banks often evaluate the cost-benefit of pursuing legal action versus settlement.
Previous Payment History
A history of timely payments before financial difficulties can work in your favor. It suggests reliability and increases the bank's confidence in your commitment to settle. This Loan Settlement Services page provides further insight into the importance of maintaining a good payment track record.
- Negotiation Strategy: Approach with a clear proposal, showing willingness to settle. Legal consultation can help frame this effectively.
- Bank Policies: Axis Bank might have specific policies or seasonal offers influencing settlements. Staying informed can provide leverage.
- External Economic Conditions: Broader economic factors, such as inflation or recession, may pressure banks to accept settlements strategically.
Understanding these factors is crucial when considering a settlement. For further legal assistance, you can learn more about Banking and Finance Law on our website.
RBI Guidelines on Loan Settlements
The Reserve Bank of India (RBI) provides comprehensive guidelines regarding the settlement of personal loans, including those with banks like Axis Bank. These guidelines ensure that the settlement process is fair, transparent, and in compliance with established banking norms. Understanding these guidelines is crucial for borrowers aiming to resolve their loan issues effectively.
Framework for Loan Settlements
RBI's framework emphasizes the importance of a One Time Settlement (OTS) which is designed to provide a final resolution for borrowers facing difficulties in repaying their loans. This framework encourages banks to offer settlements that consider the borrower's financial situation and ensure the settlement amount is feasible.
Key Provisions
- Transparent Communication: Banks must communicate the terms of the settlement clearly, ensuring borrowers are fully informed.
- Policy Adherence: Banks like Axis Bank should follow internal policies approved by their Board of Directors, as per RBI's directive.
- Non-Coercive Measures: The use of recovery agents must comply with RBI's guidelines to avoid harassment and unfair practices.
For borrowers seeking guidance on loan settlement, it is recommended to consult resources like Loan Settlement Services and Legal Rights Against Recovery Agent Harassment for a comprehensive understanding and to safeguard their interests during the settlement process.
Consumer Rights During Loan Recovery Processes
During the loan recovery processes, borrowers have specific consumer rights that protect them from unfair practices. Knowing these rights can empower you to handle recovery agents effectively and ensure a fair settlement process. The Loan Settlement Services offered by AMA Legal Solutions can provide guidance tailored to your situation.
As per the Reserve Bank of India (RBI) guidelines, recovery agents must adhere to ethical practices. They are prohibited from using abusive language, and harassment is not allowed. If you experience any misconduct, you have the right to report it to the bank and escalate it to the RBI if necessary.
| Parameter / Criterion | Key Details / Legal Provision | Timeline / Practical Impact |
|---|---|---|
| Communication | Recovery agents may contact between 7 AM and 7 PM only. | Immediate; ensures peace during personal time. |
| Language | Prohibited from using abusive or threatening language. | Immediate; promotes respectful interaction. |
| Documentation | All communications must be documented; request written communication. | Ongoing; ensures clarity and record-keeping. |
| Complaints | Report misconduct to the bank; escalate unresolved issues to RBI. | Within a stipulated period; follow bank/RBI guidelines. |
If you're considering settling your loan, it's crucial to be aware of your rights to negotiate effectively. Learn more about consumer protection and legal avenues by exploring our Banking and Finance Law services for robust support.
Key Insights & Data Infographic
Visual summary, statistical trends & procedural breakdown
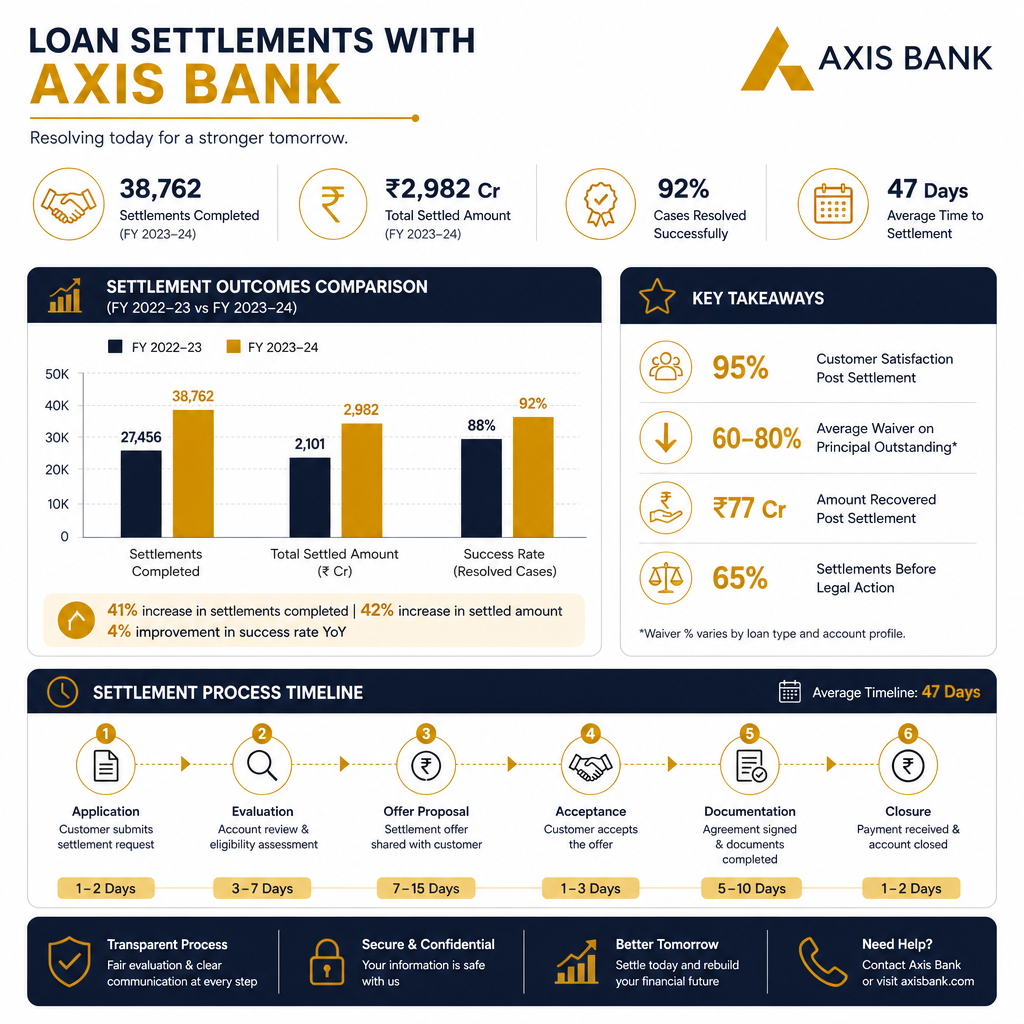
Prepared by AMA Legal Solutions Research & Analytics Team • Data & Compliance Overview
Practical Steps for Negotiating a Settlement with Axis Bank
Negotiating a loan settlement with Axis Bank can be a complex yet manageable process with the right approach. The initial step is to assess your financial position meticulously. Understanding your liabilities and resources will empower you to propose a realistic settlement offer. It is advisable to request a detailed statement of your outstanding dues from Axis Bank to ensure clarity in negotiations.
Engage in Constructive Communication
Initiate a respectful and constructive dialogue with the bank's recovery department. Clearly explain your current financial challenges, such as loss of income or unexpected expenses. Express your intention to settle the matter amicably. Always communicate in writing for record-keeping purposes, and request the bank to do the same.
Offer a Reasonable Settlement Proposal
Propose a settlement amount that reflects a fair compromise. Typically, banks are open to settling for a percentage of the outstanding amount. Ensure your proposal is backed by factual evidence of your financial condition. You might consider discussing options such as Debt Consolidation & Restructuring to strengthen your case.
Leverage Legal Assistance
Seeking advice from a legal professional specializing in Banking and Finance Law can be invaluable. They can help you navigate the complexities of the settlement process, ensuring you understand your rights and obligations under Indian banking laws. This guidance can be crucial in achieving a favorable outcome.
Common Mistakes Borrowers Make During Settlements
Securing a loan settlement with a bank like Axis Bank involves intricate negotiations, and borrowers often stumble into pitfalls that could be avoided with the right guidance. A prevalent mistake is not understanding the settlement impact on credit scores; a settled loan is reported as "settled" rather than "closed", affecting future creditworthiness.
Many borrowers also fail to document their conversations and agreements. It's crucial to have every agreement, especially those regarding settlements, in writing. Oral agreements hold little legal value and might lead to misunderstandings or disputes later.
Overlooking Legal Advice
Engaging in settlement discussions without legal consultation can be detrimental. A seasoned expert can provide insights into banking and finance law, ensuring negotiations are in your best interest and compliant with RBI guidelines.
- Ignoring the importance of a no-dues certificate post-settlement, which confirms that no amount is outstanding.
- Failing to negotiate effectively. Borrowers often accept the first offer, unaware that banks may be open to further negotiation.
- Not considering alternative resolutions or restructuring options which may be more beneficial in the long term.
- Being unaware of consumer rights and legal protections against aggressive recovery tactics can lead to undue stress.
Avoiding these common mistakes can significantly improve the outcome of a personal loan settlement with Axis Bank. Always stay informed and seek professional guidance to navigate the complexities of loan settlements effectively.
What Recovery Agents Can Legally Do and Not Do
Recovery agents play a crucial role in the loan settlement process with Axis Bank, but there are clear legal boundaries they must adhere to. Understanding these limits ensures borrowers can protect their rights during potentially stressful recoveries. These agents are authorized to contact borrowers and negotiate repayment plans, typically through phone calls or scheduled meetings.
What Recovery Agents Can Legally Do
- Contact borrowers directly by phone or in person during reasonable hours (typically 7 AM to 7 PM).
- Inform borrowers of outstanding dues and discuss possible repayment plans.
- Request payment of debts and provide options for restructuring or settlement.
- Visit borrowers' residences or offices with prior consent and during appropriate times.
What Recovery Agents Cannot Do
- Use offensive or abusive language in any communication.
- Threaten borrowers with legal action without basis or authority.
- Confiscate or repossess property without following due legal process.
- Misrepresent themselves as legal authorities or law enforcement officers.
If borrowers feel harassed or their rights are being violated, they should consider seeking legal assistance. For further guidance, explore our services on Banking and Finance Law which ensure borrowers are well-informed of their legal rights.
Timeline and Process for Axis Bank Loan Settlements
Understanding the timeline and process for settling a personal loan with Axis Bank is crucial for borrowers looking to alleviate financial stress. Axis Bank follows a structured approach that involves negotiation and legal compliance. Below is a detailed timeline and process outline:
Initial Contact and Documentation
Once you decide to pursue a loan settlement, initiate contact with Axis Bank's loan department. Gather all relevant documents, including your loan agreement, payment history, and any correspondence with the bank. This will provide a solid foundation for negotiation.
Negotiation and Offer
Engage in discussions with the bank's representatives to negotiate a settlement amount. Axis Bank typically assesses your financial situation and might offer a discount on the outstanding amount. Ensure all offers are documented.
Formal Agreement
Upon reaching an agreement, a formal settlement agreement will be drafted. Review this document carefully to ensure it aligns with the terms discussed. Seek assistance from a legal expert if necessary.
Payment and Closure
Make the agreed-upon payment by the specified deadline. Once payment is confirmed, request a 'No Dues Certificate' from the bank to officially close the loan account. This certificate is critical for maintaining your credit record.
| Parameter / Criterion | Key Details / Legal Provision | Timeline / Practical Impact |
|---|---|---|
| Initial Contact | Reach out to Axis Bank's loan department with your loan details. | Within 1-2 weeks |
| Negotiation | Discuss and negotiate settlement amount. | 2-4 weeks |
| Formal Agreement | Review and sign the settlement agreement. | 1 week |
| Payment and Closure | Complete payment and obtain 'No Dues Certificate'. | 1-2 weeks post-payment |
For further assistance on the Loan Settlement Services and understanding the intricacies of Banking and Finance Law, consider consulting legal experts. Each step requires careful attention to detail to ensure compliance and favorable outcomes.
Structured Table: Comparison of Legal Remedies vs. Procedural Steps
In the context of the loan settlement of a personal loan by Axis Bank, understanding the difference between legal remedies and procedural steps is crucial. Legal remedies provide borrowers with formal solutions to resolve disputes or defaults, while procedural steps are the actions taken to manage the settlement process efficiently.
Legal Remedies
- Debt Restructuring: This involves altering the terms of your loan to make repayment more feasible, such as extending the loan term or reducing the interest rate.
- Arbitration: Engaging in a structured process to resolve disputes outside of court. More information is available in our Arbitration and Dispute Resolution service.
- Legal Notice: Sending a formal demand for settlement or outlining legal consequences. Consider our Legal Notice and Agreement Drafting services for assistance.
Procedural Steps
- Assessment of Financial Position: Evaluate your current financial status to determine the best settlement strategy.
- Negotiation with Bank: Directly engage with Axis Bank to discuss and negotiate settlement terms.
- Documentation: Compile all necessary documents such as loan agreements, repayment history, and correspondence with the bank.
- Formal Agreement: Once terms are agreed upon, ensure a formal written agreement is in place to avoid future disputes.
For a detailed understanding of loan settlement processes, explore our Loan Settlement Services.
Case Studies: Successful Loan Settlements with Axis Bank
Understanding real-life experiences can be incredibly insightful when navigating the complex process of loan settlements. Here, we explore successful cases of loan settlements with Axis Bank, illustrating strategies that worked for borrowers.
Case Study 1: Business Owner in Financial Distress
A small business owner facing financial distress due to declining sales had defaulted on a personal loan with Axis Bank. Through proactive communication and presenting a detailed financial statement, they negotiated a significant reduction in the outstanding amount. By opting for loan settlement services, the borrower managed to settle the debt amicably without further legal action.
Case Study 2: Salaried Individual's Debt Resolution
A salaried individual found themselves unable to meet the EMI requirements due to unexpected medical expenses. Axis Bank was approached with a formal request for restructuring the loan, backed by medical documentation. The bank offered a settlement offer, which was accepted, helping the individual regain financial stability. This highlights the importance of banking and finance law expertise in navigating such settlements.
Lessons Learned
- Transparency and honesty in financial disclosures can lead to a successful negotiation.
- Professional guidance, such as expert legal advice, is crucial in presenting a compelling case to the bank.
- Timely communication with the bank prevents escalation and opens the door to negotiations.
Popular Searches

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages
Client Reviews
"The professionalism and in-depth knowledge of banking law at AMA Legal Solutions helped me negotiate a settlement effectively."
Neha Sharma
"AMA Legal Solutions expertly guided me through the loan settlement process with Axis Bank, ensuring a fair deal that I could manage."
Arjun Mehta
"Thanks to AMA Legal Solutions, I was able to resolve my financial distress with Axis Bank smoothly and amicably."
Ravi Patel
"AMA Legal Solutions provided exceptional service, navigating the complexities of my loan settlement with expertise."
Vivek Rathi
"Their guidance on RBI guidelines and consumer protection was invaluable during my loan settlement with Axis Bank."
Sonia Kapoor
Frequently Asked Questions
Related Articles

How to Trust Law Associates for Loan Settlement
Ensure Successful Loan Settlement with Trusted Legal Experts
Read Article
Expert Loan Settlement Lawyer: Minimize Amount, Maximize Waiver
Unlocking the Secrets to Successful Loan Settlements in India
Read Article
Mastering Loan Settlement of Personal Loan by Bajaj Finance
Navigate Bajaj Finance Loan Settlements with Expert Legal Insights
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Help?
Get expert advice on loan settlement and debt relief.
Call +91-8700343611Request Callback