SAMA, Presolv360 & Cordis ODR Notice for Loan Default: Legal Defense & Settlement (2026)
Prevent ex-parte online arbitration awards and negotiate a 50%+ OTS on ODR portals.
Anuj Anand Malik
Reviewed by AMA Legal Solutions
Key Takeaways: Receiving a digital legal summons via SMS, WhatsApp, or email from platforms like SAMA.live, Presolv360, Cordis, or CADRE is now the standard recovery protocol for Indian banks and NBFCs managing delinquent credit cards and personal loans. Navigating a sama presolv360 cordis online dispute resolution odr notice loan settlement requires an immediate, informed legal response rather than fear or dismissive neglect. These private institutional Online Dispute Resolution (ODR) portals are not government courts, yet the arbitral proceedings conducted on them carry binding judicial authority under the Arbitration and Conciliation Act, 1996 and the Mediation Act, 2023. Dismissing an ODR communication as spam invariably triggers an ex-parte arbitral award enforceable as a civil court decree under Section 36, exposing borrowers to bank account attachments and salary garnishments. Conversely, engaging early with seasoned advocates at arbitration and dispute resolution services transforms the digital hearing into a powerful strategic advantage: borrowers can challenge unilateral arbitrator appointments under landmark Supreme Court jurisprudence (CORE v. ECI & Perkins Eastman) and leverage the mandatory conciliation window to secure a binding 50% to 70% One-Time Settlement (OTS) via loan settlement services at AMA Legal Solutions.
Introduction: Understanding SAMA, Presolv360 & Cordis Online Dispute Resolution (ODR) Notices in India
When an Indian borrower defaults on an unsecured personal loan or credit card, dealing with a sama presolv360 cordis online dispute resolution odr notice loan settlement requires immediate, strategic legal comprehension. Over the past three years, the landscape of retail debt recovery across India has undergone a massive digital transformation. Traditional registered post legal notices printed on green paper and sent via India Post Speed Post have been overtaken by automated digital alerts pinging directly onto borrowers' smartphone screens.
Every single day, thousands of distressed borrowers across Mumbai, Delhi NCR, Bengaluru, Hyderabad, Chennai, Kolkata, and Pune awaken to WhatsApp messages, text messages, and urgent emails carrying formal captions:
- "NOTICE OF ARBITRATION: ICICI Bank / HDFC Bank has referred Loan A/C XXXXXX to SAMA. Click here to join your conciliation hearing on Zoom."
- "URGENT LEGAL DISPUTE: Presolv360 Dispute Resolution Platform has been appointed in the matter of Axis Bank vs. You. Access your dispute docket and file your response within 14 days."
- "ARBITRAL TRIBUNAL SUMMONS: Cordis Digital Resolution Notice issued on behalf of Bajaj Finance Ltd. Sole Arbitrator has scheduled virtual hearing. Failure to attend will result in ex-parte proceedings."
- "CADRE / WEBNYAY ONLINE MEDIATION NOTICE: Kotak Mahindra Bank / IDFC First Bank has initiated institutional ADR proceedings regarding your outstanding dues."
Borrowers across Delhi, Mumbai, Bengaluru, and tier-2 cities frequently panic upon receiving a digital summons, unsure how to handle a sama presolv360 cordis online dispute resolution odr notice loan settlement without compromising their financial future. The natural human reaction is polarized between two dangerous extremes: total panic leading to rushed, desperate payments of illegal penal interest, or total apathy rooted in the misconception that an unsolicited WhatsApp link is merely a fraudulent phishing trap or an empty threat from a third-party tele-calling recovery agency.
Both responses are legally flawed. SAMA, Presolv360, Cordis, and CADRE are legitimate, institutional alternative dispute resolution entities backed by comprehensive Indian statutory frameworks. If you treat their notices as spam, an independent arbitrator will conduct a five-minute virtual hearing in your absence and issue an ex-parte monetary award carrying the full force of a civil court decree. However, if you understand the procedural rules of the Arbitration and Conciliation Act, 1996 and engage experienced banking defense counsel at loan settlement in India, these very ODR portals can be converted into your most formidable weapon to freeze recovery agent harassment, dispute predatory charges, and negotiate an ironclad One-Time Settlement (OTS) at a 50% to 70% discount.
Are SAMA, Presolv360, Cordis, and CADRE Real Courts or Private ODR Platforms? Legal Status Explained
To demystify these digital summonses, one must first dissect the constitutional and corporate nature of Online Dispute Resolution (ODR) entities operating in India. A frequent question asked by panicked clients is: "Is SAMA a real court? Did a government judge send me this WhatsApp link?"
1. Private Institutional Administrators vs. Judicial Courts
Understanding the corporate and administrative foundation of these entities is vital when preparing your sama presolv360 cordis online dispute resolution odr notice loan settlement defense. SAMA (administered by Presolv Solution Pvt Ltd / Sama Technologies), Presolv360 (Edgecraft Solutions Pvt Ltd), Cordis (Cordis Technology Solutions), CADRE (Centre for Alternate Dispute Resolution Excellence), Webnyay, and JustAct are private, tech-enabled institutional alternative dispute resolution (ADR) service providers. They are NOT government courts, they are not Debt Recovery Tribunals (DRTs), and they are not state-run Lok Adalats created under the Legal Services Authorities Act, 1987.
These platforms function as digital registries and dispute infrastructure administrators. They provide the software architecture: automated WhatsApp notifications, secure electronic evidence repositories, video-conferencing rooms (frequently integrated via Zoom or proprietary WebRTC modules), digital docket tracking, and electronic timestamping. They do not decide the dispute themselves; rather, they provide an institutional roster of empanelled neutrals—primarily retired district judges, senior advocates, accredited mediators, and specialized commercial arbitrators—who preside over the digital proceedings.
2. The Policy and Statutory Impetus: NITI Aayog's ODR Framework
While these platforms are private corporations, their operational model is explicitly endorsed and accelerated by the Government of India and the judiciary. Following the landmark NITI Aayog committee report entitled 'Designing the Future of Dispute Resolution: The ODR Policy Plan for India', the Indian state recognized that traditional courts—burdened by over 45 million pending cases—could never resolve millions of micro-value consumer credit disputes efficiently. ODR was designated as a national imperative to unclog the civil justice apparatus.
Neither SAMA, Presolv360, Cordis, nor CADRE is a government court; however, ignoring a sama presolv360 cordis online dispute resolution odr notice loan settlement carries severe civil consequences. When an empanelled arbitrator on an ODR portal conducts a proceeding under Part I of the Arbitration and Conciliation Act, 1996, that arbitrator exercises quasi-judicial statutory powers. An arbitral award signed digitally on an ODR portal is not a private recommendation; under Section 36 of the Act, it is directly executable in the Principal District Court or High Court having jurisdiction, possessing the exact same legal efficacy as a formal decree issued by a senior civil judge!
| ODR Platform | Operating Corporate Entity & Headquarters | Major Partner Banks & Lending NBFCs | Primary Dispute Workflows Handled | Statutory Powers & Enforceability of Outcomes |
|---|---|---|---|---|
| SAMA (Sama.live) | Sama Technologies Pvt Ltd (Bengaluru / Pan-India) | ICICI Bank, Axis Bank, DMI Finance, KrazyBee, Northern Arc | Pre-litigation conciliation, digital mediation, Section 21 sole arbitration | Mediated Settlement Agreements under Mediation Act, 2023; Binding Arbitral Awards executable under Section 36 CPC. |
| Presolv360 | Edgecraft Solutions Pvt Ltd (Mumbai) | HDFC Bank, Kotak Mahindra Bank, IDFC First Bank, Aditya Birla Capital | Automated dispute intake, institutional conciliation, fast-track digital arbitration | Official institutional arbitration rules; awards enforceable as civil decrees across all Indian District Courts. |
| Cordis (Cordis.co.in) | Cordis Technology Solutions Pvt Ltd (Pune / New Delhi) | Bajaj Finance, Axis Finance, Piramal Capital, Tata Capital | Mass digital arbitration, virtual evidentiary hearings, Section 17 interim relief | High-volume institutional arbitrations; issues Section 31 final awards subject to Section 34 challenge. |
| CADRE | Centre for Alternate Dispute Resolution Excellence (Bengaluru) | Small Finance Banks, Microfinance Institutions, Digital NBFCs | Community mediation, micro-arbitration, expedited debt conciliation | Pre-litigation settlements enforceable under Section 73/74 Arbitration Act; arbitral decrees. |
| Webnyay & JustAct | Webnyay Legal Technologies / JustAct Resolution Services | State Bank of India, Public Sector Banks, Regional Fintechs | Virtual mediation, MSME commercial conciliation, e-Lok Adalat integrations | Statutory conciliation awards; consent decrees under Section 30 of the Arbitration and Conciliation Act, 1996. |
Why Indian Banks & NBFCs (HDFC, ICICI, Axis, SBI, Kotak, IDFC First & Bajaj Finance) Moved to Mass Digital Arbitration
To understand why you received a sama presolv360 cordis online dispute resolution odr notice loan settlement, one must evaluate the cost economics of retail banking recovery. Over the past decade, Indian commercial banks and Non-Banking Financial Companies aggressively expanded their unsecured retail credit books, disbursing trillions of rupees through instant personal loans, pre-approved digital overdrafts, Buy Now Pay Later (BNPL) schemes, and credit cards. When macroeconomic headwinds, inflation, and corporate job cuts triggered rising default rates, institutional lenders discovered that conventional legal recovery mechanisms were completely broken.
1. The Breakdown of Traditional Judicial Channels
Before the advent of ODR, an Indian bank seeking to recover a defaulted loan of Rs. 1,50,000 to Rs. 10,00,000 faced insurmountable judicial bottlenecks:
- Debt Recovery Tribunals (DRTs) Are Inaccessible: Under the Recovery of Debts Due to Banks and Financial Institutions (RDB) Act, 1993, the minimum pecuniary threshold for filing an Original Application (OA) before a DRT is Rs. 20 Lakhs. Over 90% of retail credit card and personal loan defaults fall far below this threshold, leaving banks legally barred from DRT courts.
- Civil Courts (Summary Suits) Take Decades: Filing a Summary Suit under Order XXXVII of the Code of Civil Procedure (CPC) in a local civil court involves paying substantial court fees (frequently 3% to 7% of the claim amount in state stamps), serving physical summons via court bailiffs, and waiting 5 to 12 years for trial conclusion. For an unsecured loan of Rs. 3 Lakhs, legal fees and court expenses rapidly exceed the recoverable principal.
- Section 138 NI Act & Section 25 PASSA Backlogs: While banks routinely initiate criminal complaints for cheque bounces or failed e-NACH mandates, Magistrate Courts across metropolitan cities are clogged with millions of pending cases. Process service is notoriously slow, and these criminal proceedings do not directly attach borrower assets—they merely exert psychological pressure.
- Physical Arbitration Was Prohibitively Expensive: Traditional physical arbitrations required leasing expensive arbitration chambers, paying substantial per-hearing sitting fees to retired judges, and managing mountain loads of paper pleadings. For retail portfolios, physical arbitration was economically unviable.
2. The Algorithmic Efficiency of ODR for Institutional Lenders
Online Dispute Resolution solved every logistical and financial problem for credit institutions. By deploying digital portals at scale, financial institutions fast-track default proceedings, making an advocate-guided sama presolv360 cordis online dispute resolution odr notice loan settlement your principal line of defense. Through API integrations between a bank's core banking system (CBS) and platforms like SAMA or Presolv360, the lender's recovery team can initiate 25,000 arbitration matters simultaneously with a single click.
The entire workflow is automated: digital loan agreements, account statements, and interest computation sheets are ingested by the platform. The system generates a digital notice, uploads it to an encrypted cloud docket, and dispatches automated hyperlinks via WhatsApp Business APIs, SMS gateways, and automated emails. The cost per case drops from Rs. 40,000 in physical arbitration to less than Rs. 1,500 on an ODR SaaS platform. For lenders like HDFC Bank, ICICI Bank, Axis Bank, State Bank of India, Kotak Mahindra Bank, IDFC First Bank, and Bajaj Finance, ODR represents the most ruthless, cost-effective recovery assembly line ever engineered.
Critical Distinction: Voluntary Online Conciliation/Mediation vs. Binding Section 21 Online Arbitration
The most crucial step in any sama presolv360 cordis online dispute resolution odr notice loan settlement strategy is deciphering whether the communication is an invitation to conciliate or a formal arbitration notice. When a borrower receives an ODR link, the text message or email often uses loose, confusing terminology such as "Notice for Virtual Dispute Resolution" or "Mediation-cum-Arbitration Session". However, under Indian law, conciliation and arbitration are fundamentally distinct legal processes with entirely different rules of engagement, risk profiles, and tactical opportunities.
1. Online Conciliation / Mediation: Completely Voluntary & Non-Binding
Many initial notices issued by SAMA, Presolv360, and CADRE are initiated under Part III of the Arbitration and Conciliation Act, 1996 (Sections 61 to 81) or under the Mediation Act, 2023. In conciliation or mediation:
- Voluntary Participation: Conciliation requires mutual consent. Under Section 62 of the Arbitration Act, conciliation proceedings only commence if the recipient explicitly accepts the invitation in writing. If you decline to participate, the conciliation simply fails.
- Zero Threat of an Adverse Unilateral Order: A conciliator or mediator is a neutral facilitator, NOT a judge. They have absolutely no statutory authority to impose a settlement, pass a monetary penalty, or issue an adverse ruling against you. They cannot pass an ex-parte award.
- High Settlement Leverage: If you do participate, any agreement reached is completely consensual. Under Section 73 of the Arbitration Act, a signed Conciliation Agreement (or Mediated Settlement Agreement) has the same status as an arbitral award on agreed terms under Section 30. It provides an exceptional opportunity to secure a 50% to 70% principal waiver without facing adversarial litigation. Review our deep-dive guides on the conciliation process for loan settlement and mediation process for loan settlement to understand how voluntary negotiations protect your rights.
2. Section 21 Online Arbitration: Adversarial, Quasi-Judicial & Legally Binding
In contrast, if the communication is a formal notice invoking Section 21 of the Arbitration and Conciliation Act, 1996, the character of the proceeding changes instantly from collaborative negotiation to binding adversarial litigation. Under Indian jurisprudence, an arbitration commences on the date on which a request for the dispute to be referred to arbitration is received by the respondent. For a detailed breakdown of statutory commencement, study what is Section 21 of Arbitration and Conciliation Act.
Misinterpreting the nature of the link can prove catastrophic during a sama presolv360 cordis online dispute resolution odr notice loan settlement. In an arbitration proceeding:
- Adversarial Trial: The empanelled arbitrator acts as a private judge empowered by contract and statute to adjudicate claims, award interest, assess default liabilities, and issue a final decree.
- The Menace of Section 25(b) Ex-Parte Orders: Unlike conciliation, your refusal or failure to participate DOES NOT halt the proceeding. Under Section 25(b) of the Act, if the borrower fails to communicate their statement of defense or fails to appear at a hearing without showing sufficient cause, the arbitral tribunal has full statutory authority to continue the proceedings and render a final ex-parte arbitral award on the basis of the evidence presented solely by the bank!
| Procedural Dimension | Online Conciliation / Mediation (Section 62 / Mediation Act) | Online Arbitration (Section 21 Arbitration Act) | Strategic Impact on Borrower Defense |
|---|---|---|---|
| Statutory Nature | Consensual, confidential alternative dispute resolution. | Binding, quasi-judicial adjudicatory process. | Conciliation is safe to test waters; arbitration demands formal legal representation. |
| Consequence of Non-Appearance | Proceedings terminate automatically with zero adverse decree or penalty. | Arbitrator proceeds ex-parte under Section 25(b) and passes binding monetary award. | Never boycott Section 21 arbitration; failure to defend results in rapid execution decree. |
| Role of the Neutral | Facilitates compromise; cannot impose terms or award damages. | Acts as sole judge; determines contractual liability and awards interest. | In arbitration, the neutral's appointment must be scrutinized for bias under Section 12(5). |
| Outcome Document | Conciliation Agreement / Mediated Settlement Agreement. | Final Arbitral Award (or Section 30 Consent Award if settled). | Both outcomes carry civil court decree force, but arbitration can enforce adverse debt. |
| OTS Negotiation Flexibility | Very high; lenders enter conciliation specifically seeking compromise cash flow. | High, provided borrower files Section 12/16 objections to shatter lender confidence. | Use conciliation for early discounts; use arbitration objections to compel desperate OTS waivers. |
Key Insights & Data Infographic
Visual summary, statistical trends & procedural breakdown
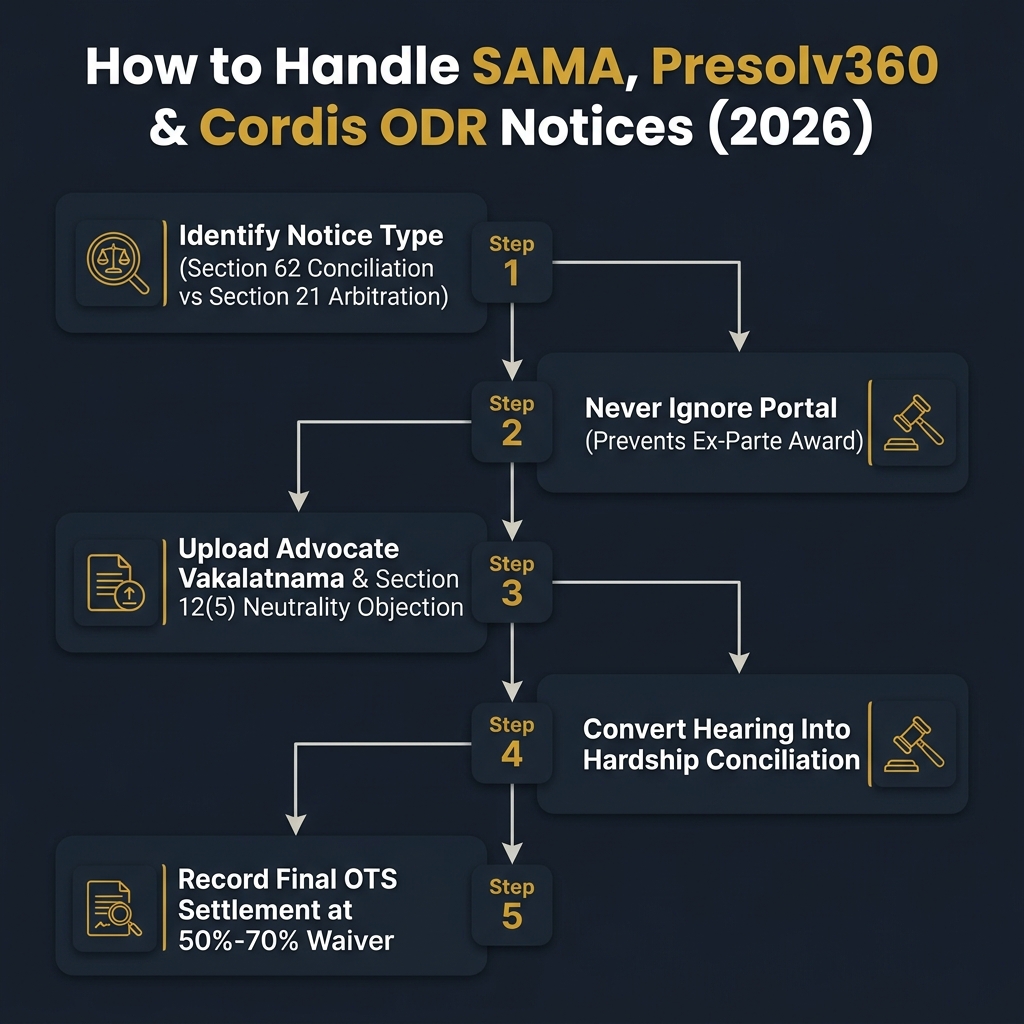
Prepared by AMA Legal Solutions Research & Analytics Team • Data & Compliance Overview

Halt Recovery Agent Harassment Legally
Why Ignoring an ODR WhatsApp or Email Link Leads to an Ex-Parte Award and Section 36 Execution
The single most dangerous piece of misinformation circulating on social media forums and amateur debt-help groups is the advice to "just block the number" or "ignore the WhatsApp link because online courts are fake". Every month, borrowers who follow this reckless advice consult AMA Legal Solutions after their primary savings accounts are suddenly frozen by court orders. To grasp the gravity of the situation, read our comprehensive analysis on can you ignore bank arbitration notice in India and examine what steps to take when you have received arbitration notice from bank in India.
1. Electronic Service Is 100% Legally Valid Under Indian Law
Many borrowers mistakenly assume that digital notices have no legal teeth, but abandoning a sama presolv360 cordis online dispute resolution odr notice loan settlement is the quickest route to an enforceable ex-parte decree. Under Section 3 of the Arbitration and Conciliation Act, 1996, any written communication is deemed to have been received if it is delivered to the addressee personally, or if it is delivered at his place of business, habitual residence, or mailing address. Furthermore, the Indian judiciary has universally recognized digital process service.
Under Section 63 of the Bharatiya Sakshya Adhiniyam, 2023 (BSA) (which superseded Section 65B of the Indian Evidence Act, 1872) and Rule 3 of the Information Technology (Intermediary Guidelines and Digital Media Ethics Code) Rules, electronic transmission via verified email addresses, SMS dispatch logs, and WhatsApp blue-tick read receipts are legally admissible as primary proof of service. When SAMA, Presolv360, or Cordis dispatches a notice to the mobile number registered in your original bank loan agreement, the platform automatically generates an encrypted cryptographic log confirming delivery. The arbitrator certifies this log, marks service as complete, and closes your opportunity to plead ignorance.
2. The Devastating Cascade of Section 36 Execution
Once you are proceeded against ex-parte, the arbitrator reviews the bank's digital claim statement, computes the inflated balance including compounding penal interest, late fees, and processing charges, and passes an Ex-Parte Arbitral Award. Here is the terrifying legal mechanism that follows:
- The 90-Day Challenge Window (Section 34): Under Section 34(3) of the Arbitration Act, a party has exactly three months (extendable by 30 days upon showing sufficient cause) to challenge an arbitral award before a Commercial Court or District Court. If you ignored the ODR notices and failed to monitor your registered email, this 90-day limitation period expires silently. Once limitation lapses, the award becomes final, unappealable, and absolute!
- Filing of Execution Petition (Section 36): Under Section 36 of the Act, an arbitral award is enforced in accordance with the provisions of the Code of Civil Procedure, 1908 (CPC) in the same manner as if it were a decree of the civil court. The bank takes the certified copy of the digital award and files an Execution Petition under Order XXI of the CPC before the District Judge where you reside or where your assets are located.
- Attachment of Bank Accounts (Garnishee Orders): The execution court issues a Garnishee Order under Order XXI Rule 46 of the CPC, directing all commercial banks in India holding accounts under your PAN to immediately freeze and transfer funds to the creditor until the awarded sum is fully satisfied.
- Attachment of Salary: If you are salaried, the court serves an order under Order XXI Rule 48 directly upon your employer's human resources or payroll department, mandating a monthly deduction of up to one-third of your attachable salary!
- Attachment of Movable & Immovable Property: The court can attach vehicles, residential property, or commercial assets for court-supervised public auction.
Once an ex-parte award is certified, executing a favorable sama presolv360 cordis online dispute resolution odr notice loan settlement becomes significantly more challenging in execution court. Fighting an execution petition after an award has become final is an uphill battle involving heavy litigation costs. The only intelligent, safe strategy is to intercept the ODR proceeding at the very outset.
How an Advocate Challenges Biased Institutional Arbitrator Rosters Under Supreme Court Law (CORE vs. ECI & Perkins Eastman)
While banks utilize ODR as an automated weapon, the judicial reality is that the vast majority of institutional online arbitrations conducted in India suffer from profound, fatal jurisdictional defects. When an experienced banking and arbitration advocate enters the proceeding, the lender's perceived advantage instantly collapses.
1. The Constitutional Prohibition Against Unilateral Arbitrator Appointments
Mounting a robust challenge under Section 12(5) of the Arbitration Act forms the legal backbone of a successful sama presolv360 cordis online dispute resolution odr notice loan settlement. Under Indian arbitration jurisprudence, neutrality is the cornerstone of justice. In a sequence of landmark judgments, the Supreme Court of India established an unshakeable doctrine:
- TRF Ltd. v. Energo Engineering Projects Ltd. (2017) 8 SCC 377: The Supreme Court held that by virtue of Section 12(5) read with the Seventh Schedule of the Arbitration Act, an individual who is legally ineligible to act as an arbitrator cannot nominate or appoint another person as an arbitrator.
- Perkins Eastman Architects DPC v. HSCC (India) Ltd. (2020) 20 SCC 760: The Supreme Court expanded the TRF doctrine, holding that an interested party—such as a lender seeking recovery—cannot unilaterally appoint a sole arbitrator to adjudicate its own dispute. The right to appoint an arbitrator cannot be monopolized by one party, as it creates an inherent, incurable apprehension of bias.
- The 5-Judge Constitution Bench in CORE v. ECI (Decided November 8, 2024 / Overruling CORE I): In Central Organisation for Railway Electrification v. M/s ECI-SPIC-SMO-MCML (JV), a five-judge Constitution Bench headed by the Chief Justice of India definitively overruled previous conflicting judgments and held that unilateral appointment mechanisms and party-curated closed panels are completely void and illegal. The Supreme Court ruled that public policy and Section 18 of the Act (equal treatment of parties) prohibit a dominant corporate party from handpicking a narrow panel and forcing the weaker party to select from it.
2. Exposing the Institutional Roster Bias on ODR Portals
The 2024 Constitution Bench ruling in CORE v. ECI empowers borrowers to dismantle unilateral panels during a sama presolv360 cordis online dispute resolution odr notice loan settlement. How do banks and NBFCs appoint arbitrators on SAMA, Presolv360, or Cordis? They rely on a standard clause buried in their 60-page digital loan agreements stating that "all disputes shall be referred to institutional arbitration administered by XYZ ODR platform". The bank pays the platform's enterprise subscription, refers thousands of cases per month, and the platform assigns an arbitrator from its closed internal roster.
When our High Court advocates at AMA Legal Solutions appear on an ODR dashboard, we immediately serve a comprehensive Section 12 and Section 16 Jurisdictional Challenge, raising three devastating legal objections:
- Violation of Section 12(5) & Seventh Schedule: We demand that the arbitrator disclose their complete case history over the preceding three years under Section 12(1) read with the Fifth and Sixth Schedules. In practice, many ODR arbitrators handle hundreds or thousands of matters referred exclusively by that same bank or NBFC! Item 22 and Item 31 of the Fifth Schedule explicitly classify an ongoing business relationship or repeat appointments by one party as justifiable grounds giving rise to real doubts regarding independence and impartiality.
- Unilateral Institutional Appointment Void Ab Initio: Under the Constitution Bench ruling in CORE v. ECI and Perkins Eastman, the institutional framework cannot act as a surrogate for unilateral appointments. Because the borrower was never given an equal voice in selecting the specific arbitrator post-dispute, the entire constitution of the tribunal is non-est and void from inception.
- Threat of Section 14 Application to High Court: We notify the arbitrator and the bank that unless the arbitrator immediately recuses themselves, AMA Legal Solutions will file an application under Section 14(2) before the jurisdictional High Court for termination of the arbitrator's mandate, alongside an application under Section 11(6) for appointment of an independent judicial arbitrator.
The impact of this legal challenge is instantaneous. An institutional lender relies on ODR because it is cheap, fast, and automated. If forced to defend a contested Section 14 or Section 11(6) petition in the High Court, the bank must engage senior trial counsel at costs ranging from Rs. 75,000 to Rs. 2,50,000 per hearing—vastly exceeding the defaulted loan amount! The bank's legal department immediately contacts AMA Legal Solutions to pull the matter out of contested arbitration and settle amicably on terms highly favorable to the borrower.
Using the ODR Conciliation Window to Negotiate a Binding 50% to 70% One-Time Settlement (OTS) Consent Award
Rather than running away from the digital hearing, turning the platform into a venue for an affordable sama presolv360 cordis online dispute resolution odr notice loan settlement gives you maximum financial leverage. An ODR proceeding is not an execution chamber; it is a structured, institutional negotiation table where the bank's decision-makers are directly accessible under formal dispute timelines. When represented by competent legal counsel, distressed borrowers can achieve remarkable compromise outcomes.
1. Step-by-Step Protocol to Execute an ODR One-Time Settlement
Here is the proven, five-stage legal protocol deployed by AMA Legal Solutions to secure deep settlement waivers on SAMA, Presolv360, and Cordis:
- Formal Representation & Vakalatnama Submission: Within 7 to 10 days of the ODR notice, our advocates upload a formal Vakalatnama and Notice of Appearance on the platform's secure portal. This single act blocks the arbitrator from passing an ex-parte order and legally mandates that all future communications, evidentiary submissions, and hearing notices be served directly upon our legal team.
- Submission of Financial Hardship Portfolio: We compile a comprehensive, irrefutable dossier documenting the borrower's genuine financial distress: medical hospitalization records, corporate downsizing letters, salary deduction slips, bank statements proving depleted reserves, or GST audit reports showing commercial downturn. Under Indian banking norms, institutional credit committees require verifiable documentary justification to write off distressed principal balances.
- Invoking Section 30 of the Arbitration and Conciliation Act: Section 30 explicitly encourages arbitral tribunals to encourage settlement between the parties and empowers the tribunal to use mediation, conciliation, or other procedures at any time during the arbitral proceedings. We formally request the arbitrator to adjourn adversarial pleadings and facilitate an amicable compromise settlement session with the bank's authorized legal recovery manager.
- Stripping Unlawful Penalties & Compound Charges: We conduct a forensic audit of the bank's Statement of Account. In accordance with the Reserve Bank of India's Master Directions on Fair Practices Code and Guidelines on Penal Charges in Loan Accounts, we demand the complete, 100% removal of all non-contractual penal interest, capitalized bounce charges, late payment penalties, and platform administrative fees.
- Locking in a 50% to 70% Principal Haircut: Operating from a position of procedural strength, our advocates negotiate a lump-sum or structured multi-tranche One-Time Settlement (OTS), typically reducing the outstanding total claim by 50% to 70%.
2. The Absolute Protection of a Section 30 Consent Award
When structured through AMA Legal Solutions, a sama presolv360 cordis online dispute resolution odr notice loan settlement culminates in a formal Section 30 Consent Award or an ironclad Bank NDC. One of the greatest hazards of informal loan settlements arranged over phone calls with third-party recovery agents is that the agent takes the money, deposits it as a partial payment, and the bank continues to demand the remaining balance. ODR completely eliminates this risk through Section 30 of the Arbitration and Conciliation Act.
Under Section 30(2), if the parties settle the dispute during arbitral proceedings, the arbitral tribunal terminates the proceedings and records the settlement in the form of an Arbitral Award on Agreed Terms (Consent Award). A Section 30 Consent Award has the exact same legal status and effect as any other arbitral award. It formally records that upon receipt of the agreed compromise sum, the entire loan facility stands fully and finally discharged, all personal guarantees are extinguished, all legal proceedings across all courts are permanently withdrawn, and the lender is legally mandated to issue a formal No Dues Certificate (NDC) and update credit bureau records across CIBIL, Experian, Equifax, and CRIF High Mark within 30 days!
Strategic Conclusion: Let AMA Legal Solutions Represent You in Any ODR Proceeding Across India
In modern Indian retail debt recovery, a sama presolv360 cordis online dispute resolution odr notice loan settlement is not a dead end but a powerful opportunity to resolve toxic debt under formal legal protection. The era of running away from debt collection, hiding from abusive recovery tele-callers, or suffering sleepless nights over anonymous legal threats is over. The digitization of alternative dispute resolution has brought legal disputes onto a transparent, recorded, and strictly regulated technological platform.
However, navigating an institutional ODR proceeding requires sophisticated legal advocacy. A single procedural error—such as ignoring a digital summons, clicking an unverified acceptance button, or attempting to argue technical points of arbitration law before a seasoned corporate arbitrator without counsel—can lead to an irrevocable ex-parte award that puts your bank accounts, salary, and personal property at severe risk.
At AMA Legal Solutions, our specialized banking litigation and arbitration practice is dedicated to protecting Indian borrowers from institutional exploitation. Spearheaded by Senior Advocate Anuj Anand Malik, our legal team provides comprehensive, end-to-end representation across every major Online Dispute Resolution platform in India, including SAMA, Presolv360, Cordis, CADRE, Webnyay, and JustAct. Because these platforms operate 100% virtually, our advocates represent clients seamlessly across all 28 states and union territories—whether you reside in Mumbai, Delhi, Bengaluru, Hyderabad, Chennai, Kolkata, Pune, Ahmedabad, Lucknow, or Chandigarh.
When you entrust your ODR defense to AMA Legal Solutions, our team immediately enters formal appearance to safeguard you against ex-parte rulings, conducts rigorous forensic audits of your loan accounts, deploys Supreme Court precedents to challenge structural arbitrator bias, and leads tough negotiations with bank credit committees to secure deep, sustainable One-Time Settlements. We ensure that every rupee you pay is legally recognized, that all criminal and civil actions are terminated, and that you receive an unshakeable, certified No Dues Certificate that restores your peace of mind and paves the path to your financial resurgence.
If you or someone you know has received an ODR notice, WhatsApp hearing summons, or arbitration alert from SAMA, Presolv360, Cordis, or CADRE, do not delay. Review our comprehensive resources on arbitration and dispute resolution services, study your fundamental protections under loan settlement services, and explore our proven track record in loan settlement in India. Take command of your legal standing today. Contact AMA Legal Solutions immediately to schedule a confidential legal consultation with our senior arbitration advocates and turn an intimidating ODR notice into permanent debt freedom.
Popular Searches & Topics
Commonly searched legal queries and keywords related to this article
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.
References & Authority
- Arbitration and Conciliation Act, 1996 (Sections 12, 16, 21, 25, 30, 34, 36 & 62) - India Code
- Mediation Act, 2023 - Ministry of Law and Justice, Government of India
- Supreme Court of India - Central Organisation for Railway Electrification (CORE) v. M/s ECI-SPIC-SMO-MCML (JV) (2024 INSC 859 / 5-Judge Constitution Bench on Unilateral Appointments)
- Supreme Court of India - Perkins Eastman Architects DPC & Anr. v. HSCC (India) Ltd. (2019 INSC 1294 / Neutrality of Arbitrators)
- NITI Aayog - Designing the Future of Dispute Resolution: The ODR Policy Plan for India
- Reserve Bank of India (RBI) - Master Direction on Fair Practices Code for Lenders & Guidelines on Recovery Agents
- Bharatiya Sakshya Adhiniyam, 2023 (Section 63 - Electronic Records Admissibility) - India Code
- Reserve Bank of India (RBI) - Framework for Compromise Settlements and Technical Write-offs
AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages
Frequently Asked Questions
Related Articles
Multiple e-NACH & UPI Autopay Bounce Charges Harassment: RBI Rules & Settlement (2026)
Stop repeated e-NACH bounce charges under NPCI rules and get a 100% OTS waiver.
Read Article
CIBIL Locate Plus Skip Tracing & Account Aggregator Consent Revocation (2026)
Learn how to revoke Account Aggregator consents and stop CIBIL skip tracing.
Read Article
Understanding Legal Notice: Key Aspects and Procedures in India (2026)
Explore essential insights and practical steps on issuing a legal notice effectively.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611