Loan Settlement Kab Karna Zaruri Hota Hai?
Explore the crucial times to consider loan settlement

Anuj Anand Malik
Reviewed by AMA Legal Solutions
Loan Settlement Kab Karna Zaruri Hota Hai?
The concept of loan settlement becomes imperative for individuals facing financial hardships. Understanding when and why ‘loan settlement kab karna zaruri hota hai’ can significantly impact your financial status and relationship with banks. This article delves into the essential aspects of loan settlement, offering practical legal advice and insights for individuals and businesses.
Understanding Loan Settlement Kab Karna Zaruri Hota Hai?
Loan settlement, often considered a last resort, is crucial when other options like refinancing or restructuring are unfeasible. It involves negotiating with banks to settle outstanding amounts usually less than what is owed, especially in scenarios where repayment capacity is severely diminished. Knowing when it becomes necessary depends on multiple factors, which we explore below.
Primary Reasons for Loan Settlement
There are several scenarios where loan settlement becomes a necessary step:
Severe Financial Distress: When you are unable to maintain regular income streams or face business closures, settling a loan can be a practical option.
Involuntary Employment Loss: If unexpected job loss leads to substantial drops in monthly income, affecting repayment abilities.
Medical Emergencies: When unforeseen medical expenses deplete emergency funds, impacting loan repayment.
Legal Obligations: Other pressing legal obligations such as settlements or judgments can necessitate loan settlement strategies.
Legal Perspectives on Loan Settlement
Understanding the legal ramifications of loan settlement is crucial when considering this financial move. It is essential to consult with banking laws and financial regulations to ensure a comprehensive approach. At AMA Legal Solutions, we provide expert advice on loan settlement, ensuring alignment with banking norms and compliance.
Steps to Initiate Loan Settlement
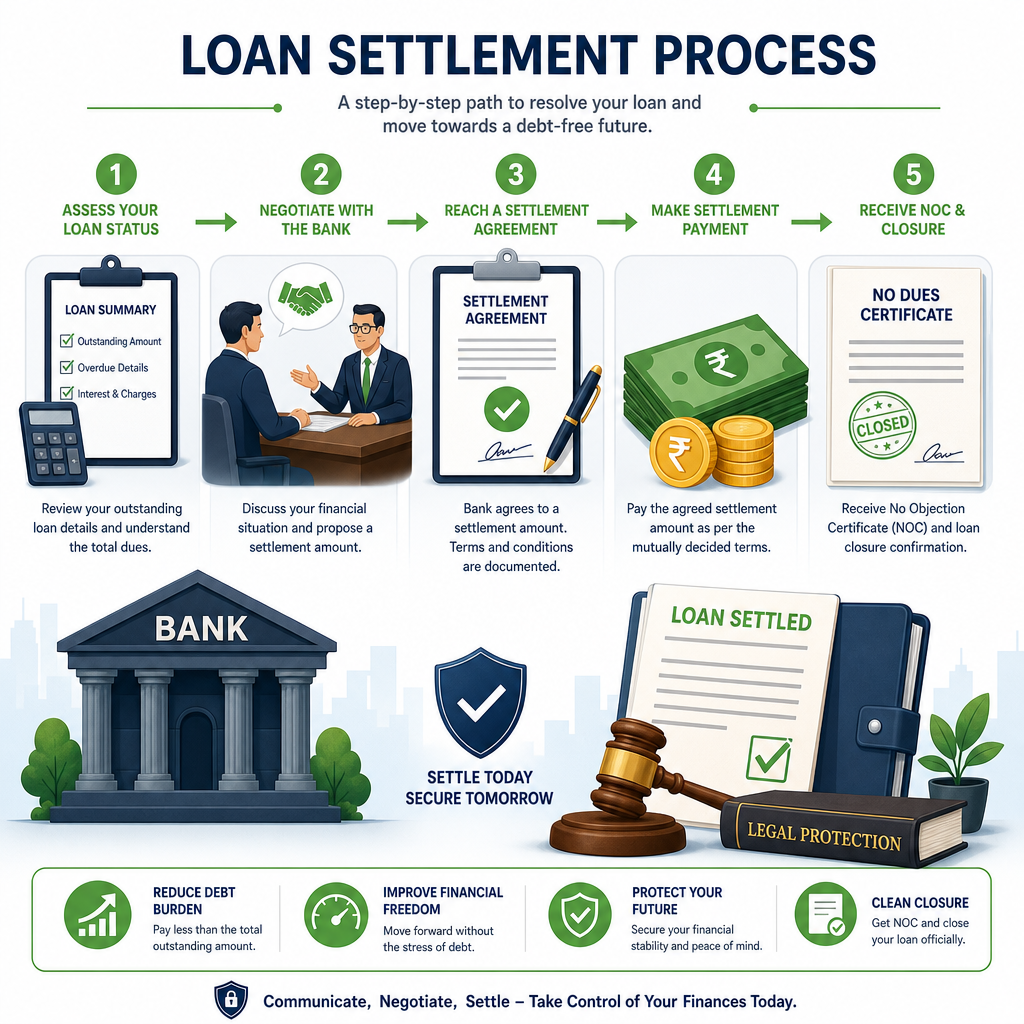
Evaluate the Financial Scenario: Assess your financial capacity and outstanding debt to determine settlement feasibility.
Consult with Legal Experts: Partner with legal advisors or firms offering banking and finance solutions.
Negotiation with Lenders: Initiate discussions with lenders, presenting them with a realistic settlement proposal.
Drafting a Settlement Agreement: Engage in meticulous agreement drafting to legally bind the settlement terms.
Finalize and Execute: Upon mutual agreement, execute the settlement, ensuring clarity on affected credit aspects.
Key Considerations in Loan Settlement
Top Quality of Loan Settlement for Banks
For successful negotiations, certain qualities are pivotal in loan settlements with banks:
Transparency in Financial Disclosures
Realistic Settlement Proposals
Professional Representation
Structured Agreements
Each of these components contributes to favorable terms and successful settlement agreements. At AMA Legal Solutions, our services ensure these elements are present and effectively exercised.
Long-term Implications of Loan Settlement
Before proceeding, consider the long-term impacts of loan settlement, which primarily include:
Affected Credit Scores
Impact on Future Loan Approvals
Potential Recovery Paths Available During Debt Resolutions
Understand these implications comprehensively with our experts at litigation and arbitration to explore recovery and resolution pathways effectively.
Conclusion
Loan settlement should be considered when financial liabilities outweigh repayment capacities, affecting one's fiscal future. It requires a strategic approach, meticulous planning, and expert guidance to navigate the associated complexities. At AMA Legal Solutions, we offer comprehensive expertise across various domains, including criminal law, corporate advisory, and more, ensuring that your financial decisions are informed and strategic.
Loan Settlement Kab Karna Zaruri Hota Hai?
The concept of loan settlement becomes imperative for individuals and businesses facing financial hardships. Understanding when and why ‘loan settlement kab karna zaruri hota hai’ can significantly impact your financial status and relationship with banks. This article delves into the essential aspects of loan settlement, offering practical legal advice and insights for individuals and businesses.

Halt Recovery Agent Harassment Legally
Understanding Loan Settlement Kab Karna Zaruri Hota Hai?
Loan settlement, often considered a last resort, is crucial when other options like refinancing or restructuring are unfeasible. It involves negotiating with banks to settle outstanding amounts usually less than what is owed, especially in scenarios where repayment capacity is severely diminished. Knowing when it becomes necessary depends on multiple factors, which we explore below.
Primary Reasons for Loan Settlement
There are several scenarios where loan settlement becomes a necessary step:
-
Severe Financial Distress: When you are unable to maintain regular income streams or face business closures, settling a loan can be a practical option.
-
Involuntary Employment Loss: If unexpected job loss leads to substantial drops in monthly income, affecting repayment abilities.
-
Medical Emergencies: When unforeseen medical expenses deplete emergency funds, impacting loan repayment.
-
Legal Obligations: Other pressing legal obligations such as settlements or judgments can necessitate loan settlement strategies.
Percentage of Waivers Given by Banks
One common question borrowers have is the percentage of waivers that banks usually offer during loan settlements. As per industry averages, leading banks may provide waivers of 25%-50% on the outstanding loan amount, depending on factors like financial distress and the borrower’s repayment history. However, it’s crucial to discuss directly with your bank as these percentages can vary. Consulting with experts in banking and finance is advisable to gauge a realistic expectation.
Legal Perspectives on Loan Settlement
Understanding the legal ramifications of loan settlement is crucial when considering this financial move. It is essential to consult with banking laws and financial regulations to ensure a comprehensive approach. At AMA Legal Solutions, we provide expert advice on loan settlement, ensuring alignment with banking norms and compliance.
Steps to Initiate Loan Settlement
-
Evaluate the Financial Scenario: Assess your financial capacity and outstanding debt to determine settlement feasibility. Create a comprehensive budget and identify all income sources to realistically evaluate the possibility of a partial repayment.
-
Consult with Legal Experts: Partner with legal advisors or firms offering banking and finance solutions. Seeking professional advice empowers you with insights into negotiation tactics and legal compliance requirements.
-
Negotiation with Lenders: Initiate discussions with lenders, presenting them with a realistic settlement proposal. A well-drafted proposal should highlight your financial constraints and the potential benefits for both parties to agree on settlement.
-
Drafting a Settlement Agreement: Engage in meticulous agreement drafting to legally bind the settlement terms. Ensuring all terms are clearly defined helps avoid future disputes.
-
Finalize and Execute: Upon mutual agreement, execute the settlement, ensuring clarity on affected credit aspects. Finalizing involves ensuring that all parties are fully aware of their obligations and rights post-settlement.
Key Considerations in Loan Settlement
Top Quality of Loan Settlement for Banks
For successful negotiations, certain qualities are pivotal in loan settlements with banks:
-
Transparency in Financial Disclosures: Clearly present your financial situation, making the bank aware of your inability to meet full repayment obligations.
-
Realistic Settlement Proposals: Offer proposals that reflect your genuine financial capacity and aim for solutions beneficial to both parties.
-
Professional Representation: Employ professional advisors who can represent your case convincingly to lenders and ensure legal compliance throughout the process.
-
Structured Agreements: Ensure all terms are documented and legally binding to protect your interests after settling.
Each of these components contributes to favorable terms and successful settlement agreements. At AMA Legal Solutions, our services ensure these elements are present and effectively exercised.
Long-term Implications of Loan Settlement
Before proceeding, consider the long-term impacts of loan settlement, which primarily include:
-
Affected Credit Scores: Loan settlement may negatively impact credit scores, affecting your ability to acquire loans in the future.
-
Impact on Future Loan Approvals: Banks may view settled loans as risk indicators causing stricter scrutiny on future credit applications.
-
Potential Recovery Paths Available During Debt Resolutions: Understanding each option can help you prepare for rebuilding creditworthiness post-settlement.
Understand these implications comprehensively with our experts at litigation and arbitration to explore recovery and resolution pathways effectively.
Related Legal Services
At AMA Legal Solutions, we don't just offer expertise in loan settlements but also across various domains. This includes:
- Intellectual Property Rights: Protect your innovations and creative works legally.
- Entertainment Law: Navigate complex issues in media and entertainment contracts.
- Real Estate: Secure your investments and property rights through comprehensive legal support.
- Criminal Law: Ensure your rights are protected in criminal proceedings.
- Corporate Advisory: Get strategic guidance on corporate governance and compliance.
- Arbitration: Resolve disputes efficiently through arbitration.
- Cyber Law: Protect your data and navigate cyber regulation efficiently.
- Civil Law: Seek justice in civil rights, property disputes, and more.
- Drafting Legal Documents: Create robust contracts and legal documents with professionals.
- Litigation: Navigate through the complexities of legal processes with expert representation.
Conclusion
Loan settlement should be considered when financial liabilities outweigh repayment capacities, affecting one's fiscal future. It requires a strategic approach, meticulous planning, and expert guidance to navigate the associated complexities. At AMA Legal Solutions, we offer comprehensive expertise across various domains, including criminal law, corporate advisory, and more, ensuring that your financial decisions are informed and strategic.
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages





Client Reviews
"Very insightful legal assistance from AMA Legal, aiding in crafting a well-negotiated settlement agreement."
Meera Singh
"Expert advice on banking laws at AMA Legal was instrumental in my financial rebound after settlement."
Priya Chopra
"AMA Legal Solutions ensured that my settlement process aligned with required legal standards beautifully."
Anjali Verma
"Their professional approach and transparency made a complex loan settlement process seamless."
Rishabh Nair
"AMA Legal Solutions provided impeccable guidance that helped me navigate my loan settlement efficiently."
Aryan Patel
Frequently Asked Questions
Related Articles

RuPay Credit Card on UPI Default & Credit Line on UPI Settlement (2026)
Micro-transactions on RuPay UPI Credit Cards and pre-approved 'Credit Lines on UPI' have triggered a massive wave of 42%+ APR revolving debt traps. Find out if defaulting blocks your personal savings UPI and how to settle RuPay UPI credit dues for 30%–50%.
Read Article
Paytm, PhonePe & BharatPe Daily EDI Merchant Loan Settlement (2026)
Drowning in Equated Daily Installment (EDI) merchant loans where 100% of your daily QR Soundbox collections are auto-swept before you can pay suppliers or rent? Learn how retail shopkeepers and MSMEs legally halt QR sweeps and negotiate a 50%+ OTS.
Read Article
Can Bank or Loan App Remotely Lock Phone for EMI Default? RBI Rules (2026)
An investigative breakdown of RBI's Remote Device Locking Directions—explaining why lenders cannot lock your phone for personal loans, the mandatory 30/60 DPD safeguards on financed devices, the Rs. 250/hour delay penalty, and how to settle device & app loans.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611