What Reason You Should Give to Recovery Agent Calls
Navigate debt recovery calls with confidence and legality.

Anuj Anand Malik
Reviewed by AMA Legal Solutions
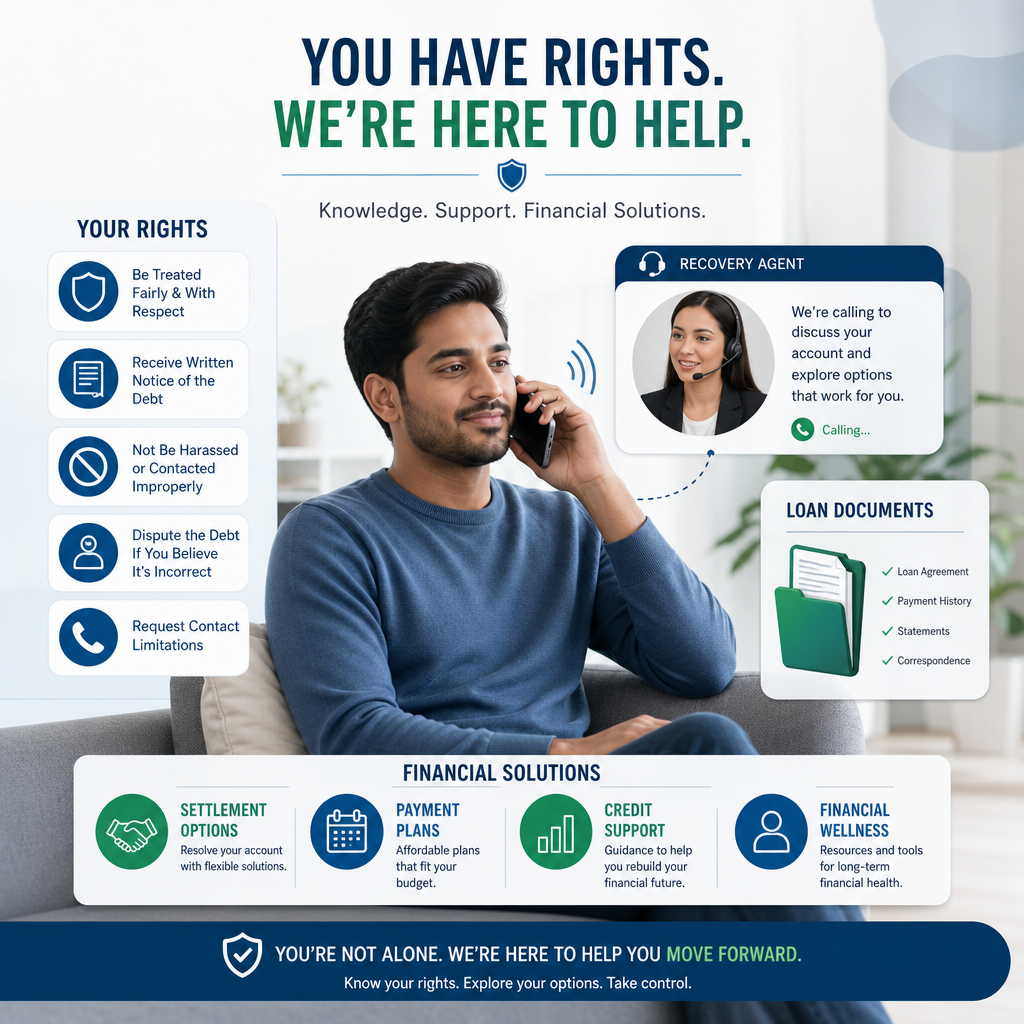
What to Say to Recovery Agents in India: Legal Reasons, Rights & Call Scripts
Receiving calls from debt recovery agents can be overwhelming. Whether you are facing a temporary financial setback or dealing with a dispute over loan details, knowing how to handle these interactions calmly, legally, and strategically is crucial.
This guide details valid reasons for payment delays, outlines your rights under Reserve Bank of India (RBI) regulations, and provides exact scripts to use on the phone.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute legal or financial advice. For specific debt or legal issues, consult a qualified advocate or financial advisor.
At-a-Glance: Dos and Don’ts During a Recovery Call
What You SHOULD Do | What You Should NEVER Do |
Remain calm and respectful throughout the call. | Do not make false promises or overcommit to payment dates. |
Verify the agent's credentials and agency details. | Do not give in to verbal threats or aggressive pressure. |
State genuine reasons for repayment delays clearly. | Do not ignore calls completely; address them strategically. |
Record the date, time, and content of all conversations. | Do not share sensitive financial info (UPI PINs, passwords). |
4 Legitimate Reasons for Repayment Delays
When speaking with a recovery agent, honesty combined with clear documentation is your best defense. Presenting a factual, verifiable reason helps set the stage for loan restructuring or temporary relief.
1. Unexpected Financial Hardship (Job Loss / Salary Cut)
If you have experienced sudden unemployment or an income reduction, inform the agent immediately. State that the delay is temporary and that you are actively seeking employment or alternative income streams.
2. Medical Emergencies or Health Expenses
Unforeseen medical expenses are widely acknowledged by lenders as valid grounds for temporary relief. Informing the lender about unexpected healthcare costs can open doors to a moratorium or restructured Equated Monthly Installment (EMI) plans.
3. Account Discrepancies or Billing Errors
If the overdue amount displayed by the agent is incorrect, or if you have already made payments that were not updated in the system, state this clearly. Mention that you require a updated statement of account before proceeding with any settlement.
4. Active Business Cash Flow Disruptions
For business or commercial loans, client payment delays or operational disruptions directly impact cash flow. Explaining these dynamics helps demonstrate that non-payment is due to operational timing rather than willful default.

Halt Recovery Agent Harassment Legally
Your Rights Under RBI Recovery Guidelines
The Reserve Bank of India (RBI) enforces strict codes of conduct to protect borrowers from unethical recovery tactics. Knowing these rules empowers you to stand your ground during any conversation.
Permissible Calling Hours: Recovery agents are permitted to contact you only between 7:00 AM and 7:00 PM. Calling outside this window is a direct violation of RBI guidelines.
Prohibition of Harassment: Agents are strictly prohibited from using abusive language, intimidation, physical threats, or contacting your family members/friends to shame you.
Right to Privacy: Agents cannot visit your workplace or residence without prior notice or at unreasonable hours.
Right to Request Written Statements: You have the legal right to request an official written statement detailing the exact principal, interest, and penalties charged before agreeing to any repayment plan.
Exact Scripts: How to Respond to Recovery Agents
Use these field-tested response templates to maintain control of the conversation:
Scenario 1: Explaining Temporary Financial Setbacks
"I acknowledge my obligation toward this loan. However, due to an unexpected financial setback [e.g., job loss / medical emergency], I am currently unable to clear the full EMI. I intend to clear my dues as soon as my situation stabilizes, and I request you to note this reason in your system."
Scenario 2: Requesting Debt Restructuring or a Revised Plan
"I am committed to clearing this debt, but the current installment is unmanageable. I would like to formally request a revised repayment schedule or loan restructuring. Please guide me on the official procedure to submit my request to the bank."
Scenario 3: Addressing Discrepancies or Demanding Verification
"The amount you are quoting does not match my records. Please send me a detailed, written account statement over email. I will review the figures and respond once I verify the breakdown."
Scenario 4: Dealing with Unprofessional or Aggressive Behavior
"I am speaking to you respectfully and expect the same in return. Under RBI guidelines, intimidation and abusive language are illegal. I am recording this call for record-keeping, and if this conduct continues, I will escalate a formal complaint to the bank's Nodal Officer and the RBI Banking Ombudsman."
What to Do If Recovery Agents Harass You
If a recovery agent violates RBI guidelines through harassment, persistent calls outside permitted hours, or threats, follow these escalation steps:
Document Everything: Maintain a log of call dates, times, agent names, and call recordings.
File a Written Complaint with the Bank: Contact the principal nodal officer of the bank or NBFC with details of the harassment.
Escalate to the RBI Ombudsman: If the bank fails to resolve your grievance within 30 days, submit a complaint on the official RBI CMS portal (
cms.rbi.org.in).Legal Recourse: For extreme cases involving physical harassment or criminal intimidation, contact legal counsel to file a police report under relevant sections of the Indian Penal Code (IPC).
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages





Client Reviews
"AMA Legal Solutions provided exceptional guidance in negotiating with recovery agents. Their expertise made a significant difference in restructuring my debt."
Priya Sharma
"The legal team at AMA was incredibly supportive and professional. They helped me understand my rights and handle recovery calls with newfound confidence."
Rajiv Menon
"I was extremely satisfied with the service from AMA Legal Solutions. They effectively mediated with my creditors and provided crucial insights into the legal process."
Sunita Narang
"Their guidance was invaluable in addressing my financial issues. AMA Legal Solutions turned a stressful situation into something manageable with their expertise."
Neha Kapoor
"A very professional and knowledgeable team! They helped me navigate through complex legal frameworks, ensuring I was protected and well-represented."
Vikram Patel
Frequently Asked Questions
Related Articles

RuPay Credit Card on UPI Default & Credit Line on UPI Settlement (2026)
Micro-transactions on RuPay UPI Credit Cards and pre-approved 'Credit Lines on UPI' have triggered a massive wave of 42%+ APR revolving debt traps. Find out if defaulting blocks your personal savings UPI and how to settle RuPay UPI credit dues for 30%–50%.
Read Article
Paytm, PhonePe & BharatPe Daily EDI Merchant Loan Settlement (2026)
Drowning in Equated Daily Installment (EDI) merchant loans where 100% of your daily QR Soundbox collections are auto-swept before you can pay suppliers or rent? Learn how retail shopkeepers and MSMEs legally halt QR sweeps and negotiate a 50%+ OTS.
Read Article
Can Bank or Loan App Remotely Lock Phone for EMI Default? RBI Rules (2026)
An investigative breakdown of RBI's Remote Device Locking Directions—explaining why lenders cannot lock your phone for personal loans, the mandatory 30/60 DPD safeguards on financed devices, the Rs. 250/hour delay penalty, and how to settle device & app loans.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611