Loan Settlement of Personal Loan by IDFC Bank: A Comprehensive Guide
Navigate IDFC Bank Loan Settlements with Expert Legal Insights
Anuj Anand Malik
Reviewed by AMA Legal Solutions
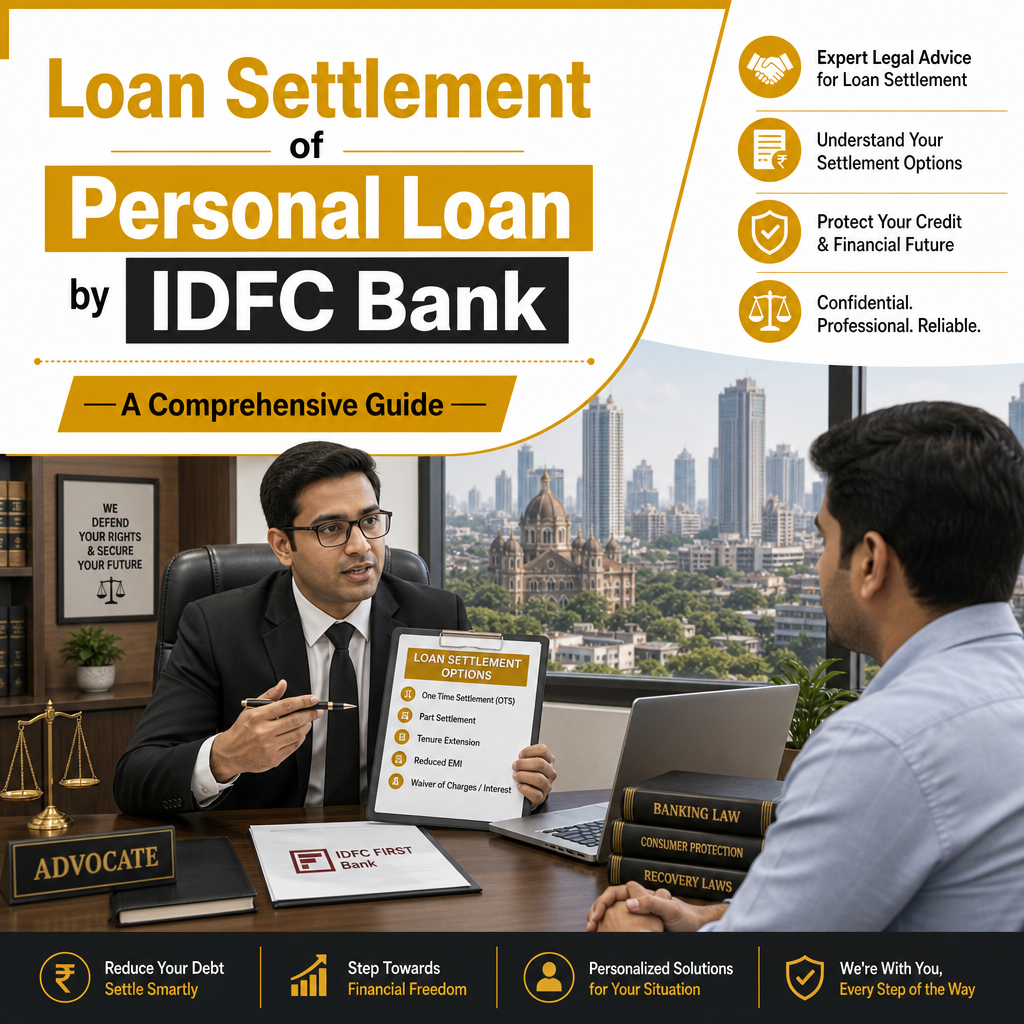
Key Takeaways: Understanding loan settlement with IDFC Bank involves negotiating to repay an outstanding personal loan for less than its total due. The process is governed by RBI guidelines, which ensure fairness. While settlements can relieve debt, they can also impact credit scores. Legal advice is crucial to navigate this process effectively and achieve a favorable outcome.
Understanding Loan Settlement: What It Means for Borrowers
Loan settlement, particularly with institutions like IDFC Bank, involves negotiating with the bank to repay an outstanding personal loan for an amount less than the total due. This often becomes necessary when borrowers face financial distress, making it impossible to meet original loan terms. The settlement process can significantly impact a borrower's credit score but offers relief from overwhelming debt.
The loan settlement process usually begins when you initiate a discussion with the bank, typically through their collections or recovery department. It's crucial to present your current financial situation transparently, supported by evidence such as job loss or unexpected expenses. Banks may consider settlement based on factors like the borrower's repayment history and the outstanding amount.
Why Consider Loan Settlement?
Borrowers might opt for loan settlement to avoid lengthy legal battles or when they are unable to pay even the minimum amounts. This agreement provides a feasible exit strategy from financial liabilities and allows individuals to focus on rebuilding their financial health.
However, it is essential to be cautious. A loan settlement can affect your credit report, leading to difficulties in obtaining future loans. Understanding the implications and considering legal advice can help you navigate the process more effectively. For those facing significant financial issues, exploring options like debt consolidation might also be beneficial.
Legal Framework: How IDFC Bank Handles Loan Settlements
IDFC Bank, like other financial institutions in India, adheres to established legal frameworks while handling loan settlements. The process is governed by regulations and guidelines provided by the Reserve Bank of India (RBI), ensuring a fair approach towards borrowers struggling with repayment. When a borrower requests a settlement, IDFC Bank assesses the individual's financial situation, the outstanding loan amount, and the reasons for default.
RBI guidelines mandate that banks must consider genuine cases and offer reasonable terms to borrowers. IDFC Bank typically reviews the borrower's repayment history, evaluates the cause of financial distress, and considers restructuring or settling the loan. Banking and Finance Law also influences the terms offered during negotiations, emphasizing transparency and fairness.
Once a settlement offer is agreed upon, the borrower must fulfill the terms within the stipulated period. Failure to adhere can lead to legal consequences or resumption of recovery actions. It's crucial for borrowers to communicate clearly and document all agreements to avoid future disputes. For those navigating this complex process, professional advice from loan settlement services can be invaluable in ensuring compliance with all legal requirements.
Key RBI Guidelines Impacting Loan Settlements
The Reserve Bank of India (RBI) provides crucial frameworks to ensure fairness and transparency in loan settlements. Understanding these guidelines is critical for borrowers negotiating with IDFC Bank for a personal loan settlement.
One-Time Settlement (OTS) Framework
The RBI encourages banks to adopt the One-Time Settlement (OTS) approach for personal loans, enabling borrowers to repay their dues through a mutually agreed lump sum amount. This process helps mitigate the burden of outstanding debt and can benefit both the bank and the borrower.
Asset Classification Norms
The RBI mandates banks to classify assets based on their performance. Non-Performing Assets (NPAs) are a significant focus, and banks must follow strict norms before declaring a loan as an NPA. This classification affects settlement offers, as banks are keen to resolve NPAs swiftly to improve their financial health.
- Banks must provide borrowers with clear options for settling their loans.
- Borrowers should be informed of the implications of settling a loan versus closure.
Recovery Agent Regulations
To protect borrowers, the RBI has stringent guidelines regarding the conduct of recovery agents. Harassment by recovery agents is prohibited, and borrowers can exercise their legal rights against recovery agent harassment. Understanding these rights is essential for a fair settlement process.
For further guidance, consider exploring our Loan Settlement Services to navigate the complexities of loan settlements effectively.
Practical Steps to Initiate a Loan Settlement with IDFC Bank
Embarking on the journey of loan settlement with IDFC Bank demands strategic planning and informed actions. Below, find a detailed guide on initiating this process effectively:
1. Assess Your Financial Situation
Begin by auditing your financial health. Understand your total outstanding dues, current income, and potential for negotiation. This clarity will empower you to propose a realistic settlement offer.
2. Contact IDFC Bank
Reach out to the bank's loan settlement department. Ensure to communicate your intention to settle the loan and request an outline of the bank’s settlement process. Maintaining transparency and a cooperative attitude can forge a positive negotiation environment.
3. Draft a Proposal
Create a settlement proposal outlining your current financial constraints and proposed repayment amount. Ensure it is reasonable and justifiable. Reference past settlements or financial hardships to strengthen your case.
4. Negotiate Terms
Engage in open discussions with the bank's representatives. Be prepared to negotiate terms such as reduced interest rates or waived penalties. Highlight your commitment to resolve the debt and consider seeking professional advice from experts in debt consolidation if needed.
5. Formalize the Agreement
Once terms are agreed upon, ensure that all details are documented in a formal settlement agreement. This documentation safeguards your interests and confirms the bank’s acceptance of the settlement terms.
By following these steps, borrowers can strategically navigate the complexities of loan settlement with IDFC Bank, ensuring a resolution that benefits both parties.
Negotiation Strategies: Getting the Best Settlement Offer
When negotiating a loan settlement with IDFC Bank, preparation is key. Start by gathering all relevant documents, such as your loan agreement, recent payment slips, and any correspondence with the bank. This will help you understand your current position and provide leverage during negotiations. Remember, the bank is more likely to agree to a settlement if you can demonstrate financial hardship.
Approaching the Bank
Initiate contact with IDFC Bank through their official communication channels. It's advisable to request a meeting with a senior loan officer who has the authority to negotiate settlement terms. During the discussion, clearly explain your situation and propose a reasonable settlement amount. Be prepared to justify your offer with financial statements or evidence of hardship.
Practical Tips
- Be Calm and Professional: Maintain a respectful tone throughout the negotiation process.
- Know Your Limits: Decide beforehand the maximum amount you can afford to pay and stick to it.
- Seek Legal Advice: Consider consulting a specialist in loan settlement services for guidance on the best approach to take.
Additionally, explore other alternatives, such as debt consolidation, which might offer a viable solution without affecting your credit score drastically. Remember, the goal is to reach an amicable agreement that satisfies both parties, ensuring your financial situation is stabilized while fulfilling the bank's recovery objectives.
Rights and Obligations: Borrowers vs. IDFC Bank
When navigating the loan settlement process with IDFC Bank, understanding your rights and obligations is crucial. Borrowers are entitled to transparency and respectful communication from the bank's recovery agents. Conversely, borrowers must communicate genuine financial difficulties and maintain a record of all correspondences.
IDFC Bank is obligated to provide clear terms for settlement and adhere to RBI guidelines. Borrowers should be aware that any negotiated settlement can impact their credit score, but it is not classified as a criminal offense in India. Understanding these dynamics can aid in a smoother resolution process.
| Parameter / Criterion | Key Details / Legal Provision | Timeline / Practical Impact |
|---|---|---|
| Communication with Recovery Agents | Borrowers have the right to demand respectful communication under RBI guidelines. | Immediate; impacts borrower’s mental health and negotiation effectiveness. |
| Transparency in Settlement Terms | IDFC Bank must disclose all terms clearly to the borrower. | Before signing the settlement agreement; vital for informed decisions. |
| Credit Bureau Reporting | Settlements are reflected in credit reports, affecting credit scores. | Reported within 30 days post-settlement; affects future creditworthiness. |
| Adherence to RBI Guidelines | Both parties must adhere to the guidelines set by the Reserve Bank of India. | Throughout the negotiation and settlement process; legal compliance. |
It is recommended to consult a legal expert for personalized guidance, especially when dealing with complex financial situations. For more information on legal rights against recovery agents, consider reading Legal Rights Against Recovery Agent Harassment.
Common Pitfalls in Loan Settlements and How to Avoid Them
The journey of a loan settlement for a personal loan with IDFC Bank is fraught with potential missteps that can complicate your financial situation if not navigated carefully. Here are some common pitfalls and strategies to avoid them:
Incomplete Documentation
Borrowers often overlook the importance of thorough documentation. Ensure you have a complete set of loan documents, communication records with the bank, and any settlement offers. Missing documentation can delay the settlement process and weaken your negotiating position.
Unrealistic Settlement Offers
Submitting overly ambitious settlement offers is a common mistake. Understand the bank’s position and financial health to make a realistic offer. Research how settlements typically happen at IDFC Bank and consider seeking professional advice for debt restructuring solutions.
Ignoring Legal Advice
Many borrowers underestimate the complexity of loan settlements and neglect to consult legal experts. Engaging with a legal professional can provide insights into your rights and the bank's obligations, ensuring a fair settlement while avoiding legal pitfalls.
Neglecting CIBIL Impact
A key concern is the impact of settlement on your credit score. Before agreeing to any terms, understand how a settlement might affect your credit and explore alternatives such as credit score repair strategies.
- Ensure all communications are documented.
- Consult with legal experts before making offers.
- Understand the potential impact on your credit score.
- Do not rush the process; take time to evaluate all options.
What Banks Don't Tell You: Behind-the-Scenes of Loan Settlements
When it comes to the loan settlement of a personal loan by IDFC Bank, there are several aspects that borrowers often remain unaware of. Typically, banks prioritize recovering the maximum amount possible while minimizing time and resource expenditure. They might not openly disclose their internal processes or the criteria they use to decide on settlement offers.
One critical point to understand is that banks internally classify non-performing assets (NPAs) into different categories. This classification can significantly impact the settlement process. For instance, loans that have been overdue for more extended periods might be more negotiable compared to recent defaults. Understanding these nuances can give borrowers an edge during negotiations.
Moreover, the banks may not readily share that their recovery agents have specific legal boundaries they must adhere to. They cannot resort to harassment or unlawful practices in pursuit of recovering dues. Knowing when to stop engaging verbally and request all communications in writing can protect you from potential harassment. For borrowers facing such issues, understanding Legal Rights Against Recovery Agent Harassment can be crucial.
In many cases, banks may not inform you that settling a loan could negatively impact your credit score, affecting future borrowing. It's advisable to weigh the pros and cons carefully and consult a legal expert in Loan Settlement Services to explore all available options and understand the implications thoroughly.
Recovery Agents: Legal Boundaries and Borrower Protections
Recovery agents play a significant role in the loan settlement process, especially in cases involving personal loans from institutions like IDFC Bank. It is essential for borrowers to understand the legal boundaries governing these agents to protect their rights effectively. Under the Reserve Bank of India (RBI) guidelines, agents must adhere to ethical collection practices, ensuring that they do not resort to harassment or coercion.
Legal Boundaries
- Agents cannot use abusive or threatening language. Borrowers have the right to be treated with respect at all times.
- Calls should only be made between 7 AM and 7 PM, maintaining a decorum that respects the borrower's privacy and schedule.
- Agents must present an official ID provided by the bank before any in-person discussions.
Borrower Protections
- If a borrower feels harassed, they can file a complaint with the bank's grievance redressal cell.
- Borrowers can insist that all communications be in writing to maintain a clear record of discussions.
- Legal actions can be pursued if agents violate the guidelines. For comprehensive support, borrowers can refer to Banking and Finance Law services.
Understanding these boundaries and protections is crucial for borrowers to navigate through the loan settlement process confidently and effectively.
Case Studies: Successful Loan Settlement Stories
Loan settlements can be daunting, but real stories of success can offer both guidance and hope. Here are two compelling case studies that illustrate how individuals successfully navigated the loan settlement process with IDFC Bank.
Case Study 1: Restructuring a Business Loan
An MSME business owner was struggling due to declining sales, resulting in default on a personal loan taken for business purposes from IDFC Bank. Initially, the bank was persistent with calls and notices. The borrower sought advice on Loan Settlement Services and began communication with the bank through formal channels. By presenting a detailed financial situation and a proposed repayment plan, the borrower successfully negotiated a reduced settlement amount, allowing for business recovery.
Case Study 2: Overcoming Personal Financial Crisis
Facing a sudden job loss, a salaried individual defaulted on an IDFC Bank personal loan. Understanding the need for resolution, they proactively contacted the bank's settlement division. By leveraging RBI guidelines and utilizing Banking and Finance Law expertise, they negotiated a settlement that allowed them to clear the debt at a fraction of the original amount. This solution helped prevent long-term credit damage.
Structured Approach: Loan Settlement Process and Timelines
Settling a personal loan with IDFC Bank requires a structured approach to ensure a favorable outcome. Initially, borrowers need to assess their financial situation and gather necessary documentation, such as income proof and bank statements. This documentation supports negotiations for a settlement. Borrowers can then approach the bank to discuss potential loan settlement options. It's crucial to understand the implications on credit scores and future borrowing.
Typically, the process involves an offer from the borrower, followed by negotiations with the bank. Successful negotiations might include a lump-sum payment or an extended payment plan. It's advisable to communicate clearly and document all agreements. The entire process can span several weeks to months, depending on the complexity of the case and the negotiation skills involved.
For expert guidance, consider consulting professionals experienced in loan settlement services to navigate the intricacies of the process. Understanding the timelines and legal framework will aid in achieving a mutually beneficial agreement.
| Parameter / Criterion | Key Details / Legal Provision | Timeline / Practical Impact |
|---|---|---|
| Initial Assessment | Review financial standing and collect documents | 1-2 weeks |
| Negotiation with Bank | Discuss settlement options and agreements | 2-6 weeks |
| Final Settlement Offer | Formalized agreement outlining payment terms | 1-3 weeks |
| Impact on Credit Score | Possible reduction in credit rating | Immediate and long-term effects |
To further understand the legalities involved, you may also explore the scope of banking and finance law for comprehensive insights. Adhering to a meticulous process ensures transparency and effectiveness in resolving loan settlements.
Legal Recourse: When Settlement Negotiations Fail
If settlement negotiations with IDFC Bank reach an impasse, borrowers have several legal avenues available. The first step is to understand the bank's actions and evaluate if they have breached any banking regulations or consumer rights. It's crucial to know that banks must adhere to RBI guidelines during recovery processes.
Next, borrowers can consider filing a complaint with the Banking Ombudsman if they suspect unfair practices. This is especially relevant if IDFC Bank is not responsive or cooperative. Additionally, approaching a legal expert can provide insights into whether filing a suit for relief in a consumer court is viable, especially if the bank's actions have been detrimental or illegal.
Arbitration and Mediation
Some cases may benefit from arbitration, which can be less adversarial and more cost-effective than litigation. Engaging in arbitration or mediation can provide a platform for more flexible negotiation, potentially leading to a more amicable resolution.
Litigation
If other methods fail, initiating civil litigation may be necessary. This step involves using the judicial system to seek a formal resolution. However, litigation can be time-consuming and expensive, so it's advisable to consult with a legal expert to assess the feasibility and potential outcomes before proceeding.
Popular Searches

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages
Client Reviews
"I was impressed by the professionalism and dedication of AMA Legal Solutions. They made the loan settlement process with IDFC Bank seamless."
Vikram Singh
"AMA Legal Solutions offered invaluable assistance in my loan settlement case. Their strategic approach led to a satisfactory settlement."
Anjali Patel
"AMA Legal Solutions provided exceptional guidance throughout my IDFC Bank loan settlement. Their expertise ensured a favorable outcome."
Rohit Mehra
"The expertise of AMA Legal Solutions made a significant difference in my IDFC Bank loan settlement experience. Highly recommend their services."
Karan Malhotra
"The legal team at AMA Legal Solutions is highly knowledgeable. They helped me understand the complexities of loan settlements with IDFC Bank."
Priya Nair
Frequently Asked Questions
Related Articles

How to Trust Law Associates for Loan Settlement
Ensure Successful Loan Settlement with Trusted Legal Experts
Read Article
Expert Loan Settlement Lawyer: Minimize Amount, Maximize Waiver
Unlocking the Secrets to Successful Loan Settlements in India
Read Article
Mastering Loan Settlement of Personal Loan by Bajaj Finance
Navigate Bajaj Finance Loan Settlements with Expert Legal Insights
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Help?
Get expert advice on loan settlement and debt relief.
Call +91-8700343611Request Callback