India’s Consumer Spending Boom Comes With Growing Debt Bill (2026)
Understanding the implications of rising consumer debt amidst India's spending surge.
Anuj Anand Malik
Reviewed by AMA Legal Solutions
Key Takeaways: India’s consumer spending boom, driven by increased access to credit, is accompanied by a growing debt burden that poses sustainability risks for consumers. Relevant legal protections, including the Consumer Protection Act and Reserve Bank regulations, play a crucial role in safeguarding consumer rights within this landscape.
Introduction to India’s Consumer Spending Boom and Debt Landscape
When evaluating India’s Consumer Spending Boom Comes With Growing Debt Bill in India, understanding the applicable statutory framework, legal procedures, and strategic rights is essential. India's consumer spending boom, fueled by an expanding middle class and increased access to credit, has significantly boosted economic growth and contributed to financial inclusion for millions of Indians. However, this boom is accompanied by a growing debt bill, raising concerns about the sustainability and potential risks of such rapid credit expansion. As consumers continue to spend vigorously, understanding the legal and financial frameworks that govern consumer debt in India becomes vital.
Statutory Framework & Governing Legal Provisions on Consumer Debt
The robust legal framework in India addresses issues related to consumer debt, balancing between fostering economic growth and protecting consumer rights. Key statutes relevant to this area include:
- The Reserve Bank of India Act, 1934: This Act empowers the Reserve Bank of India (RBI) to regulate banking sector practices, including oversight of consumer lending.
- The Banking Regulation Act, 1949: It provides a comprehensive framework ensuring fairness and transparency in lending activities.
- The Consumer Protection Act, 2019: Designed to safeguard consumer rights, this Act addresses unfair trade practices and ensures redressal mechanisms for grievances related to consumer debt.
- The Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest (SARFAESI) Act, 2002: It facilitates creditors in recovering debts through enforcement mechanisms without requiring court intervention.
These statutes collectively create a structured environment, allowing consumers to enjoy the benefits of the spending boom while protecting them from the pitfalls of mounting debt.
Comprehensive Analysis & Practical Evaluation of Consumer Spending Trends
India's consumer spending boom is largely driven by a surge in non-housing retail loans, which constitute a significant portion of household borrowings. As consumer confidence grows, spending on goods and services has soared, further spurring economic activities. However, this growth accompanies a notable increase in household debt, reaching 49.1% of GDP in the first quarter of 2026.
This trend raises critical questions about sustainability, particularly when credit-driven consumption may outpace income growth, leading to financial distress. As consumers take on more debt, navigating the complex landscape of consumer credit becomes crucial to avoid potential financial pitfalls.
Comparative Analysis: Impact of Debt on Consumer Behavior
The rising debt levels due to India's consumer spending boom have altered consumer behavior significantly. A comparative analysis of the spending patterns and related consequences unveils critical insights:
| Consumer Behavior Aspect | Pre-Boom Trends | Post-Boom Trends | Implications of Increased Debt | Guidance |
|---|---|---|---|---|
| Savings Rate | Moderate | Decreased as spending increased | Reduced financial resilience | Encourage balanced financial planning |
| Credit Utilization | Conservative | High credit card usage | Higher vulnerability to default | Consider credit card debt settlement |
| Loan Preferences | Home and auto loans | Increase in personal and instant loans | Risk of over-leverage | Seek loan settlement services |
| Financial Literacy | Low | Improving but still lacking | Poor decision-making | Promote financial literacy programs |
This analysis highlights the need for prudent financial planning and the selection of suitable debt instruments to ensure balanced economic growth and personal financial health.
Key Insights & Data Infographic
Visual summary, statistical trends & procedural breakdown
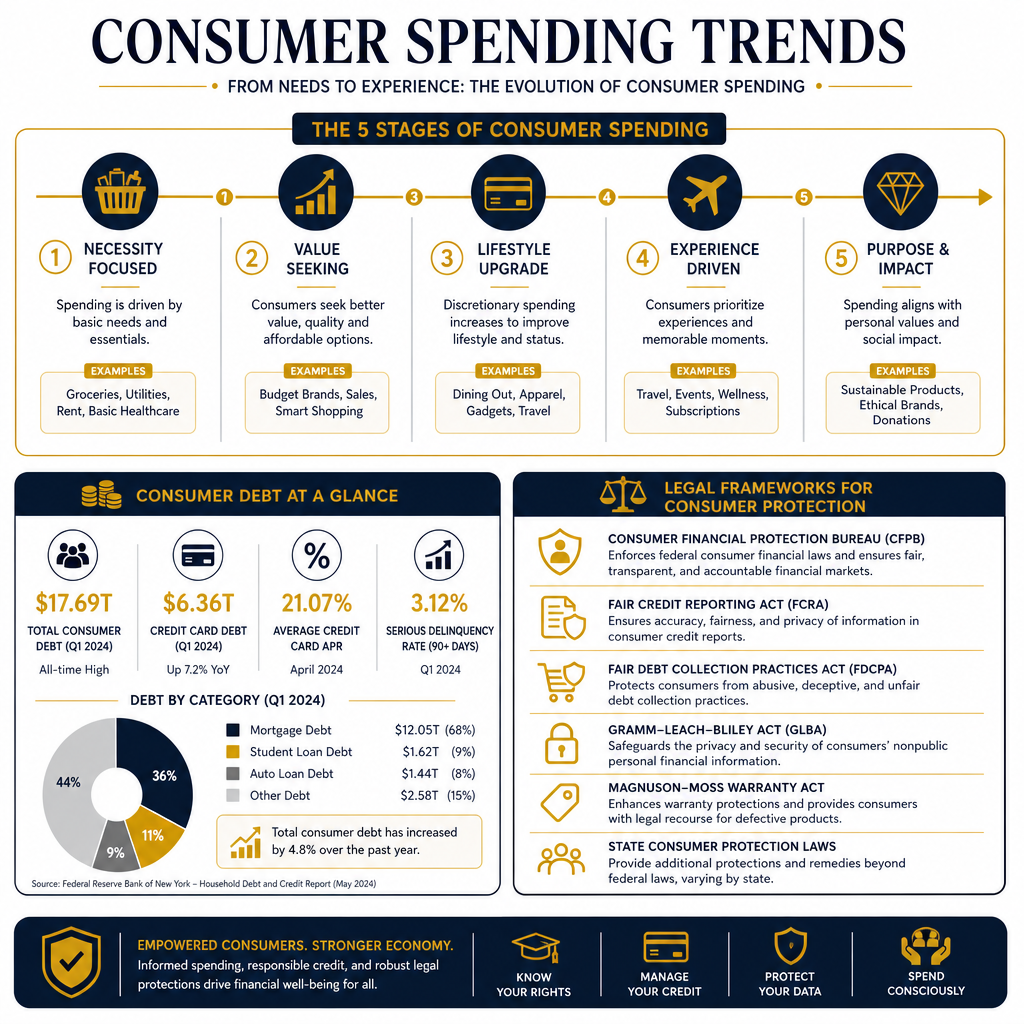
Prepared by AMA Legal Solutions Research & Analytics Team • Data & Compliance Overview

Credit Card & Personal Loan Settlement With Your Bank
Legal Safeguards, Consumer Rights, and Critical Risks to Avoid
Legal frameworks provide several consumer rights and safeguards in the face of the consumer spending boom and growing debt:
- Right to Fair Treatment: Financial institutions must follow fair practices throughout the lending and recovery processes, with coercive tactics strictly prohibited.
- Transparency Obligations: Lenders are mandated to disclose loan terms, interest rates, fees, and penalties in a clear and comprehensive manner to enable informed decision-making by consumers.
- Access to Grievance Mechanisms: Consumers have recourse to Consumer Disputes Redressal Commissions to address grievances concerning financial services.
- Protection Against Unfair Trade Practices: The Consumer Protection Act ensures consumers are safeguarded against misleading practices and can seek redressal for such grievances.
Despite these safeguards, consumers must remain vigilant to prevent over-borrowing and ensure they have a thorough understanding of their financial obligations.
Understanding the Role of Financial Institutions and Regulations
Financial institutions play a crucial role in India’s consumer spending boom, significantly influencing consumer borrowing habits. With the RBI providing stringent oversight, these entities operate within a regulatory framework that prioritizes transparency and customer protection. Nevertheless, challenges persist, particularly with digital lending platforms, which often operate outside traditional regulatory scrutiny.
Here, consumers must ensure they engage with reputable lenders and fully comprehend the terms and conditions of their financial agreements. Additionally, seeking advisory services from expert legal counsel at firms like AMA Legal Solutions can prevent adverse legal and financial outcomes.
Challenges Consumers Face Amidst Rising Debt Levels
The burgeoning debt from India’s consumer spending boom presents several challenges, notably:
- Increased Likelihood of Default: With high levels of borrowing, particularly through high-interest products, consumers risk defaulting, leading to severe financial strain.
- Asset Seizure and Credit Score Damage: Defaults can trigger asset seizures under the SARFAESI Act and negatively impact consumers' credit scores, limiting future borrowing capacity.
- Psychological Stress: Continuous financial burden can significantly affect mental health, highlighting the importance of financial literacy and assistance.
- Legal Complications: Consumers might face complex legal challenges, especially with aggressive recovery practices from unauthorized lenders.
To mitigate these challenges, consumers are advised to consult with legal experts to understand their rights and available remedial actions.
Strategic Conclusion: Securing Legal Assurance with AMA Legal Solutions
India’s consumer spending boom indeed opens new vistas for economic expansion, but it also brings with it a growing debt bill that cannot be ignored. Navigating the complex framework governing consumer debt requires a strategic approach to safeguard oneself against potential pitfalls. For consumers caught in this intricate web of spending and debt, AMA Legal Solutions offers a comprehensive suite of services, including debt consolidation, legal protection against unfair trade practices, and personalized financial consultations. By partnering with seasoned professionals, consumers can ensure they uphold their legal rights while making informed financial decisions, thereby managing their debt and financial health effectively.
Popular Searches & Topics
Commonly searched legal queries and keywords related to this article
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages
Frequently Asked Questions
Related Articles
Loan Default Due to Diwali Credit Card Spent? Make Sure Youre Aware of These Facts
Understanding the implications and solutions for managing credit card debt during Diwali.
Read Article
CIBIL 'Suit Filed' Status Removal After Loan Settlement & RBI Rs. 100/Day Rule (2026)
Remove Suit Filed status from CIBIL post-OTS and claim Rs. 100/day RBI penalty.
Read Article
Joint Loan Default During Divorce in India: Co-Borrower Settlement & Release (2026)
Navigate joint loan defaults during divorce and secure a co-borrower OTS release.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611