Debt Recovery System for NBFCs & Fintechs: Automated 3-Notice Cadence & Police Escalation
Overcome unresponsive borrowers, eliminate aggressive collection agency risks, and arrest rising Non-Performing Assets. Deploy AMA Legal Solutions' advocate-supervised debt recovery system for NBFCs. Simply provide delinquent portfolio records in a single spreadsheet. Our automated engine generates contract-specific legal notices, dispatches three progressive notices spaced one week apart across Physical Speed Post, Law Firm Email, and WhatsApp with Section 63 BSA delivery proof, and escalates wilful defaulters to formal Police Complaints under the Bharatiya Nyaya Sanhita, 2023—all under transparent fixed legal advisory without hourly markups or surprise retainers.

Founder & Senior Advocate • Reviewed by Team AMA Legal Solutions
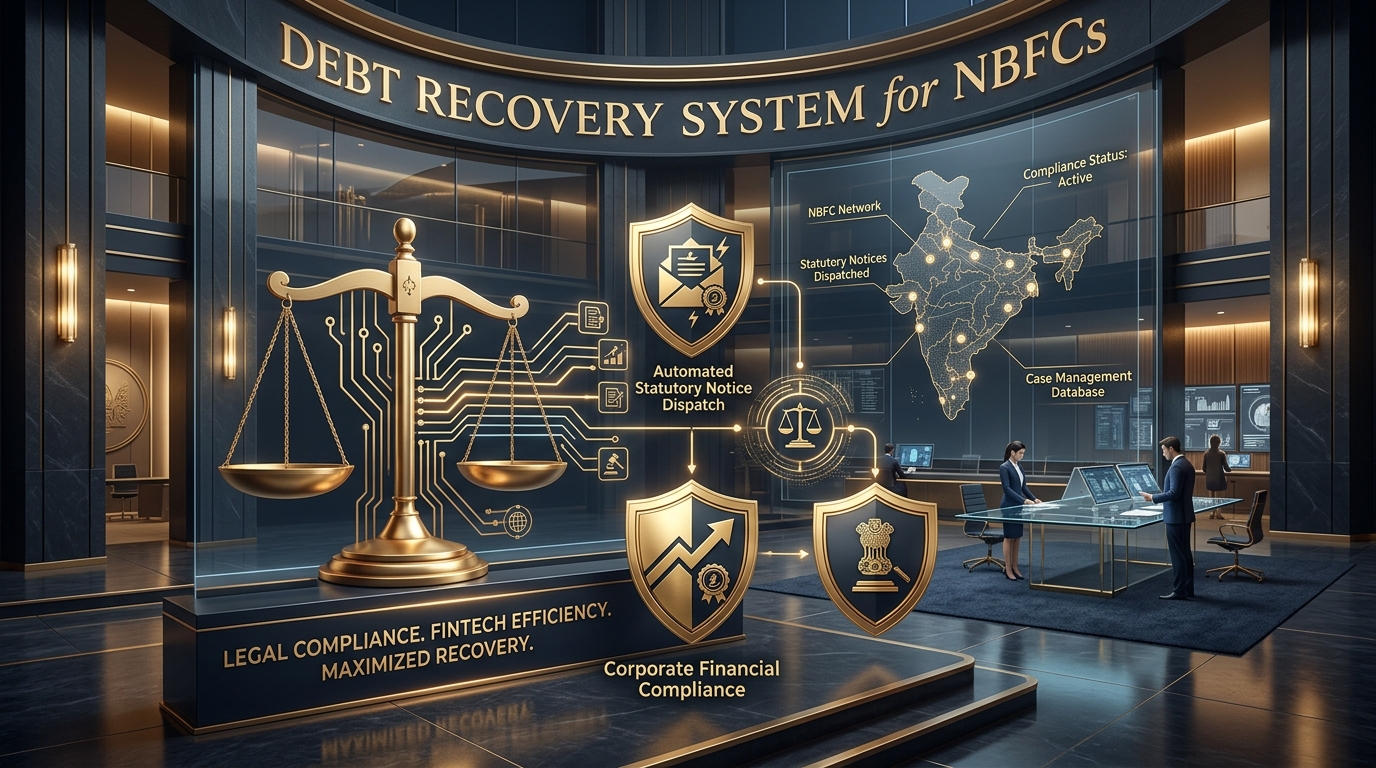
Automated 3-Notice Weekly Cadence + Police Escalation
Speed Post, Email & WhatsApp • Full Statutory Admissibility
Onboarded & Actively Powered
Keep 100% of Recovered Capital (Zero Cut)
Speed Post + Email + WhatsApp Delivery
Average Pre-Litigation NPA Resolution
Institutional Partnership
Require custom master service agreements (MSAs) or automated Loan Management System (LMS) integrations? Speak directly with our senior banking litigators.
Quick Answer: What is a Debt Recovery System for NBFCs?
A debt recovery system for NBFCs is an advocate-led statutory escalation framework that automates bulk delinquent loan resolution through structured legal notices, multi-channel service proof, and police complaint lodging under the Bharatiya Nyaya Sanhita, 2023. This institutional protocol replaces aggressive third-party collection agencies with 100% RBI Fair Practices Code compliant legal workflows dispatched via Speed Post, Email, and WhatsApp. Non-Banking Financial Companies deploy this system to cure non-performing assets (NPAs) swiftly, preserve brand reputation, and enforce contractual repayment without excessive corporate law firm retainers.
Why Traditional Collection Fails & Exposes NBFCs to Regulatory Sanctions
For years, Non-Banking Financial Companies and digital lending fintech platforms have relied on a two-pronged collections playbook: low-cost in-house telecalling call centers or commission-driven third-party recovery agencies. In the modern regulatory landscape governed by the Reserve Bank of India's Master Directions on Fair Practices Code and Digital Lending Guidelines, both approaches have collapsed under operational and legal pressure:
Borrowers entering 30+ Days Past Due (DPD) buckets quickly learn that telecalling agents possess zero statutory authority. Defaulters install spam-blocking applications, block unknown numbers, ignore generic automated SMS reminders, and simply delete mobile lending applications. Contact rates for conventional call centers on delinquent accounts have fallen below 11%, leaving capital stalled in bad debt provisions.
When NBFCs outsource bad loans to unregulated external agencies, agents frequently resort to unauthorized contact harvesting, abusive phone calls to borrower relatives, or unannounced residential confrontations. Under current RBI directives, the regulated entity bears absolute vicarious liability for vendor infractions, leading to crushing regulatory fines, police FIRs against management, and irreparable reputational damage across digital media.
The 3-Notice Weekly Cadence & Police Escalation Architecture
Generic single-letter demands are frequently discarded by serial defaulters. Our proprietary debt recovery system executes a disciplined, multi-stage statutory escalation sequence. Spaced exactly seven days apart, each phase intensifies statutory exposure while maintaining an unimpeachable legal paper trail:
Notice #1: Formal Demand
Dispatched on advocate letterhead under Section 73 of the Indian Contract Act, 1872. Sets forth the credit disbursal date, contractual covenants breached, crystallized outstanding balance, and provides a strict 7-day cure window to settle amicably without judicial intervention.
Notice #2: Statutory Escalation
Automatically triggered on Day 8 if payment or contact is not established. Invokes Section 25 of the Payment and Settlement Systems Act, 2007 (PSSA) for NACH / e-Mandate dishonour or Section 138 of the Negotiable Instruments Act, 1881, warning of penal prosecution and two years imprisonment.
Notice #3: Pre-Litigation Final
Dispatched on Day 15. Serves as final pre-prosecution legal warning. Puts the borrower on notice regarding imminent police lodging under Bharatiya Nyaya Sanhita, summary recovery suit filing under Order 37 CPC, and formal flagging as a Wilful Defaulter across RBI credit bureaus.
Police Complaint Filing
For persistent, unyielding wilful defaulters, our litigation team drafts and files formal Police Complaints under Sections 316 and 318 BNS (Criminal Breach of Trust & Cheating) with jurisdictional cyber and economic offences authorities.
Zero-Friction Ingestion: Excel-to-Dispatch Automation
Institutional recovery systems often fail because they require cumbersome engineering integrations, complex API setups, or disruption of legacy Loan Management Systems (LMS). AMA Legal Solutions engineered a zero-friction data pipeline designed specifically for lean NBFC risk and operations teams:
| Standard Spreadsheet Column | Data Definition | Legal & Judicial Function |
|---|---|---|
| Borrower_Full_Name | Legal name of primary borrower or co-guarantor | Designated as the principal respondent / accused party in notices |
| Registered_Mobile | 10-digit primary mobile / WhatsApp enabled number | WhatsApp statutory notice delivery and Section 63 BSA delivery audit |
| Official_Email | Borrower verified personal or employment email | Dispatched with digitally signed advocate PDF and SMTP transmission logs |
| Postal_Address_PIN | Residential or correspondence address with pin code | Physical Speed Post dispatch with India Post barcode consignment proof |
| Loan_Account_Identifier | Unique credit account / loan agreement number | Statutory debt identifier cited across all legal notices and court filings |
| Principal_Disbursed | Original disbursed principal credit sum | Establishes valid consideration and lawful contract formation |
| Total_Crystallized_Dues | Principal outstanding + contractual interest dues | Liquidated debt sum demanded with statutory cure period |
| NACH_Bounce_Date_Memo | e-Mandate / NACH / Cheque dishonour date & reason | Mandatory statutory prerequisite to trigger Section 25 PSSA / Section 138 NI Act |
Batch Processing Velocity: Whether onboarding 200 delinquent accounts or an institutional batch of 15,000 delinquent accounts, our automated ingestion engine normalizes addresses, validates postal pin codes, populates advocate-vetted templates, and queues triple-rail dispatch within 24 business hours.
Contract-Specific Drafting vs Flawed DIY Automated Templates
Many fintech lenders and smaller NBFCs attempt to cut costs by deploying unverified online DIY legal notice generators or generic automated mail merges. In practice, generic DIY notices invariably fail in court because they lack statutory precision, fail to cite specific loan sanction covenants, and do not carry advocate certification under the Advocates Act, 1961:
Sanction Covenants Cited
Our senior banking advocates review your master lending agreement, sanction letters, and digital click-wrap e-Sign logs. Every notice cites specific acceleration clauses, hypothecation terms, and arbitration provisions, leaving borrowers zero grounds to deny awareness.
High Court Advocate Signing
Unrepresented corporate notices are treated as commercial reminders. A formal legal notice issued on the letterhead of an enrolled High Court advocate carrying Bar Council enrollment details carries immediate psychological gravity and formal evidentiary validity.
Flawless Evidentiary Integrity
In summary suits under Order 37 CPC or Section 25 PSSA prosecutions, courts strictly scrutinize proof of demand. DIY templates lack certified electronic delivery logs, allowing defaulters to stall proceedings by claiming non-service. Our system pre-empts this completely.
Triple-Rail Delivery: Speed Post, Email & Section 63 BSA WhatsApp
Under Indian civil and criminal jurisprudence, establishing conclusive service of notice upon the borrower is a statutory prerequisite before obtaining judicial decrees or criminal summons. Our recovery system simultaneously deploys three synchronized delivery rails:
Speed Post / Registered AD
Physical notices delivered directly to the borrower's residence or registered employer address carry unmistakable gravitas. We generate individual India Post barcode tracking numbers and maintain permanent delivery confirmations.
- India Post Barcoded Consignments
- Verifiable Proof of Delivery (POD)
- Statutory compliance for Section 138 NI Act
Advocate Signed Digital Copy
Dispatched from our official law firm domain to the borrower's registered email address with cryptographic hash verification, digital signatures, and complete SMTP server transmission logs.
- Digitally signed advocate PDF
- Automated SMTP server delivery audit
- Immediate instantaneous dispatch
Instant Verified Messaging
Delivered directly to the borrower's WhatsApp with interactive repayment portal links, advocate letterhead preview, and verifiable timestamped read receipts admissible under Section 63 BSA, 2023.
- Direct Section 63 BSA certificate
- Blue-tick read receipt audit trail
- Over 92% open rate within 3 hours
Visual Blueprint: The Institutional Debt Recovery System for NBFCs
From automated Excel ingestion to triple-rail statutory dispatch and formal Bharatiya Nyaya Sanhita police complaint dockets.
Figure 1.1: Automated 3-Notice Weekly Cadence, Triple-Rail Multi-Channel Delivery & Police Escalation Architecture.
Statutory Grounding: Bharatiya Nyaya Sanhita, PSSA Section 25 & NI Act
Every notice and police complaint docket prepared by AMA Legal Solutions is grounded in established Indian commercial, cyber, and criminal statutes:
Bharatiya Nyaya Sanhita, 2023 (BNS) — Sections 316 & 318
Replacing Sections 406 and 420 of the Indian Penal Code, these provisions penalize Criminal Breach of Trust and Cheating. Where a borrower secures funds through falsified KYC, forged salary credentials, or immediately diverts hypothecated collateral, criminal intent exists from inception. Our advocates draft structured criminal dockets submitted to jurisdictional police stations to initiate formal inquiry.
Payment and Settlement Systems Act, 2007 (PSSA) — Section 25
Explicitly governs electronic fund transfers, NACH auto-debits, and e-Mandates. When an electronic clearing instruction is dishonoured due to insufficient funds or cancellation without lender consent, Section 25 imposes criminal liability identical to Section 138 of the NI Act, carrying up to two years imprisonment and fines up to twice the loan amount.
Code of Civil Procedure, 1908 (CPC) — Order 37 Summary Suits
For liquidated debts arising from written loan contracts, promissory notes, or dishonoured negotiable instruments, Order 37 provides a fast-track summary recovery procedure. The defendant borrower cannot defend as a matter of right without obtaining leave from the court, allowing NBFCs to secure swift summary judgments and asset attachment orders.
Bharatiya Sakshya Adhiniyam, 2023 (BSA) — Section 63
Modernizing Section 65B of the Indian Evidence Act, Section 63 governs the admissibility of electronic records. Our system automatically produces statutory certificates validating electronic device logs, WhatsApp blue ticks, and SMTP transmission trails, ensuring conclusive evidence of service in court.
Comparative Evaluation: DIY Templates vs Corporate Firms vs AMA System
When designing an institutional recovery strategy, NBFC management teams must balance legal enforceability, operational speed, and statutory compliance. The matrix below compares the three primary market alternatives:
| Operational Dimension | Free / Cheap Online DIY Templates | Traditional Corporate Law Firms | AMA Legal Solutions Recovery System |
|---|---|---|---|
| Commercial Structure | Low upfront, zero execution | Costly monthly retainers + hourly billing | Transparent Fixed Advisory (Keep 100% Capital) |
| Advocate Certification | None (Unrepresented notices) | Enrolled Advocates | Enrolled High Court Advocates (Every Docket) |
| Multi-Channel Service | Email blast or manual mail only | Physical post only, slow processing | Synchronized Post + Email + Verified WhatsApp |
| Electronic Admissibility | No Section 63 BSA certificate | Manual affidavit preparation | Automated Section 63 BSA Audit Certificate |
| Criminal Escalation | Incapable of criminal drafting | Slow individual complaint drafting | Automated BNS 316/318 Police Complaint Dockets |
| RBI Compliance Shield | High liability risk | Compliant | 100% Compliant Fair Practices Code Shield |
| Batch Ingestion Capacity | Manual copy-paste error prone | Restricted to low volume files | Up to 15,000 Accounts / Batch within 24 Hours |
Frequently Asked Questions (Institutional Legal Desk)
📚 More Institutional Legal & Recovery Guides
AMA Legal Solutions
Premier Banking, FinTech & Commercial Litigation Firm
AMA Legal Solutions is an advocate-led law firm headquartered in Delhi NCR, specializing in institutional debt recovery, banking compliance, financial arbitration, and white-collar defense. We combine decades of High Court courtroom trial experience with automated legal-tech infrastructure to power high-velocity pre-litigation recovery for India's leading financial enterprises.
Our Core Institutional Solutions:
Reviewed & Authored by Adv. Anuj Anand Malik
Verified Bar Council AdvocateFounder & Senior Advocate, AMA Legal Solutions | Enrolled with Bar Council of Delhi & Delhi High Court Bar Association
Advocate Anuj Anand Malik advises institutional banking clients, NBFCs, digital credit platforms, and debt recovery tribunals across India. With over a decade of specialized banking and commercial litigation experience, he pioneers legally sound, high-velocity debt recovery and compliance solutions that maximize loan recovery while upholding statutory dignity and RBI regulatory directives.
Adv. Anuj Anand Malik
Senior Banking Advocate
Advocate at Delhi High Court & Supreme Court of India. Strategic counsel for NBFC loan recovery, corporate NPA resolution, and financial compliance.
Need Legal Help for NBFC Recovery?
Eliminate external agency commissions and cumbersome corporate retainers. Onboard your delinquent loan portfolio onto our automated statutory notice and police escalation framework.
“Implementing AMA Legal Solutions' debt recovery system for our NBFC portfolio transformed our NPA resolution. The automated three-notice escalation across physical Speed Post and verified WhatsApp brought an immediate 43% recovery uplift without any regulatory friction or heavy retainers.”
Vikram Singhania, VP Operations at FinEdge Capital
Verified Institutional Partner • 48 Reviews