Settlement of Loan with Bank: Understanding Your Rights and Options
Unlock solutions for effective loan settlements with banks in India (2026)

Anuj Anand Malik
Reviewed by AMA Legal Solutions
Key Takeaways: The settlement of loan with bank involves negotiating repayment terms that may reduce the total debt amount owed, particularly useful during financial distress. Borrowers must understand their rights under RBI guidelines, the legal implications, and the processes to protect themselves during settlements, ensuring compliance with tax laws and credit reporting norms.
Introduction to Settlement of Loan with Bank in India
Settling a loan with a bank involves negotiating terms that conclude your outstanding debt for less than the owed amount. This option is often pursued when financial distress makes it impossible to repay the full debt. The settlement of loan with bank is a crucial process for borrowers facing defaults, offering a way to clear dues without exhaustive litigation.
Statutory Framework & Governing Legal Provisions
In India, the settlement of loan with bank is guided by statutory frameworks established by the Reserve Bank of India (RBI) and various legislative acts. The RBI's Master Circular on Prudential Norms for Income Recognition and Asset Classification underpins One-Time Settlements (OTS). Additionally, the SARFAESI Act, 2002, allows banks to recover defaulted loans expeditiously, while the RDDBFI Act, 1993, facilitates quick debt resolution via Debt Recovery Tribunals.
Comprehensive Analysis & Practical Evaluation of Loan Settlements
The settlement of loan with bank can be a viable solution for individuals and businesses when structured prudently. Before pursuing a settlement, borrowers must understand the implications on credit scores and lender relations. Key procedures include negotiating the percentage of outstanding dues to be settled, typically ranging from 35% to 50% depending on the loan type and borrower’s financial status.
Comparative Parameters / Procedural Workflow Matrix for Loan Settlement
| Parameter / Option | Legal Basis & Requirements | Key Procedures / Considerations | Strategic Advantage with Counsel |
|---|---|---|---|
| OTS Scheme | RBI Guidelines | Lump-sum payment, legal agreement | Pre-negotiated agreements |
| SARFAESI Act | Statutory Provisions | Enforcement of securities | Court intervention avoidance |
| Lok Adalat | RDDBFI Act | Expedited resolution | Binding, cost-effective resolutions |
| DRT Proceedings | Debt Recovery Tribunals | Formal adjudication | Advocate representation |
Understanding Consumer Rights in Loan Settlement Processes
Borrowers engaging in the settlement of loan with bank should be aware of their legal rights, ensuring protection against unfair recovery practices. The RBI mandates nondiscriminatory and transparent processes, while borrowers should ensure receipt of No-Objection Certificates post-settlement to confirm closure of accounts. Consultation with legal experts can help safeguard these rights.
Key Insights & Data Infographic
Visual summary, statistical trends & procedural breakdown
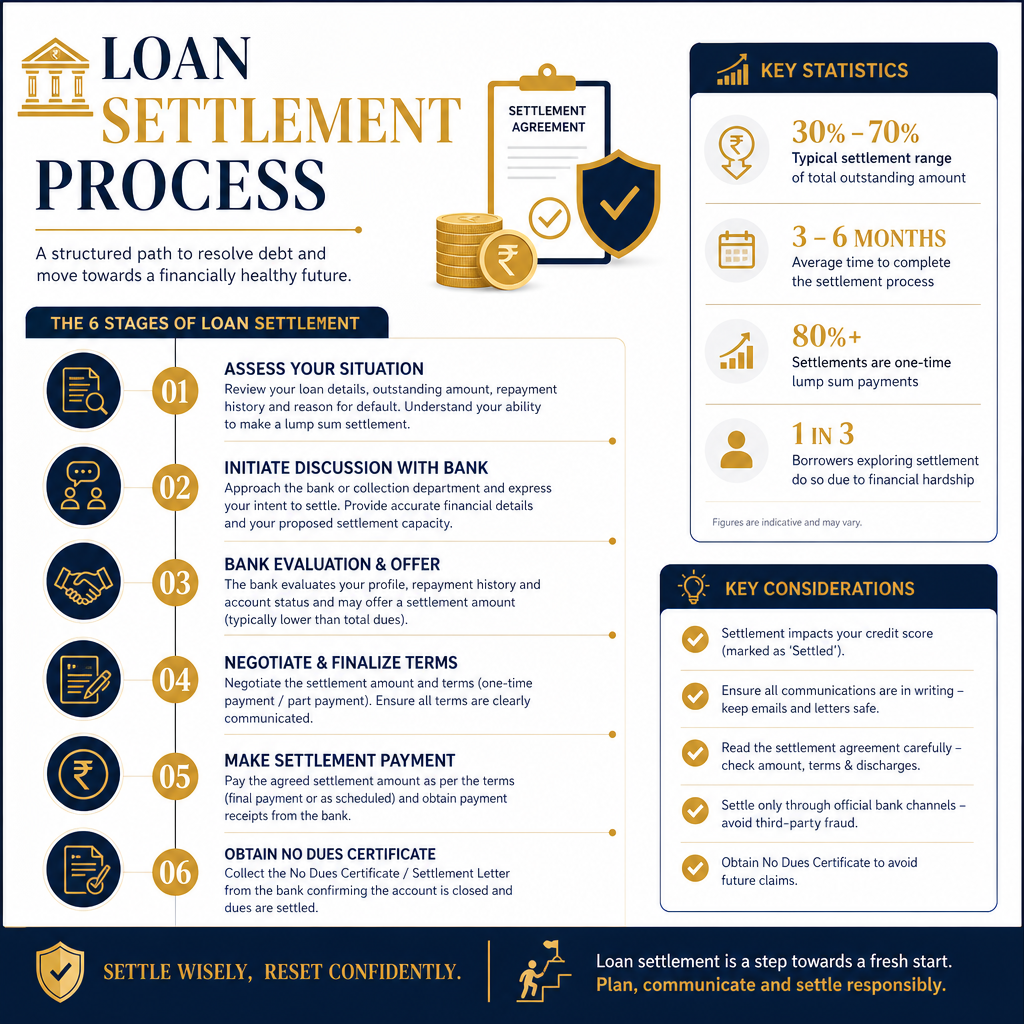
Prepared by AMA Legal Solutions Research & Analytics Team • Data & Compliance Overview

Halt Recovery Agent Harassment Legally
Critical Risks in Loan Settlements: What to Avoid
When pursuing a settlement of loan with bank, borrowers must be cautious of certain pitfalls. Settlements reflected in credit reports as "settled" can impact CIBIL scores adversely, potentially reducing them by 75–100 points. Additionally, tax implications under Section 56(2)(x) of the Income Tax Act should be considered for any waived amounts. Legal advice is crucial to navigate these complexities.
Real-Life Case Studies and Examples of Successful Loan Settlements
Consider a scenario where a distressed borrower managed a settlement of loan with bank through an OTS at 45% of the original debt. Although initially hesitant, the borrower engaged in diligent negotiation, supported by legal counsel, resulting in an agreement beneficial to both parties. Such examples underscore the power of informed negotiation and strategic settlement approaches.
Negotiation Strategies for Borrowers Facing Loan Defaults
Effective negotiation is fundamental for a successful settlement of loan with bank. Borrowers should articulate their financial hardships clearly and propose feasible payment terms. Engaging a negotiator or an advocate often enhances the outcome, as these professionals understand banking norms and creditor expectations. Analyzing bank-specific settlement policies can also shape an effective strategy.
Best Practices for Communicating with Banks on Your Loan
Communication plays a pivotal role in the settlement of loan with bank. Borrowers should maintain clear, polite, and documented interactions. Prefer communication through email to ensure traceability and avoid verbal commitments. In situations of disagreement, deferring to legal channels can help maintain focus and professionalism in negotiations.
Legal Safeguards and Support Available through AMA Legal Solutions
AMA Legal Solutions provides expertise in facilitating the settlement of loan with bank through registered advocate counsel. This service encompasses comprehensive legal drafting, strategic negotiation, and representational services across India. Legal support from professional firms ensures adherence to statutory obligations and protection of borrower interests under the Advocates Act, 1961.
Strategic Conclusion: Securing Legal Assurance for Your Loan Settlements
A strategically approached settlement of loan with bank can streamline financial recovery while ensuring compliance with legal standards. Borrowers are advised to engage with proficient legal advisors who can navigate complex banking laws and negotiations effectively. Trustworthy solutions from AMA Legal Solutions guarantee rigorous advocacy, safeguarding client rights and fostering satisfactory resolutions.
``` Please continue with the necessary SEO metadata, FAQs, and EEAT documentation in a new response to conclude the article's setup.Popular Searches & Topics
Commonly searched legal queries and keywords related to this article
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages





Frequently Asked Questions
Related Articles

Can Bank or Loan App Remotely Lock Phone for EMI Default? RBI Rules (2026)
An investigative breakdown of RBI's Remote Device Locking Directions—explaining why lenders cannot lock your phone for personal loans, the mandatory 30/60 DPD safeguards on financed devices, the Rs. 250/hour delay penalty, and how to settle device & app loans.
Read Article
How Recovery Agents Get Your Personal Details and How to Prevent It in India (2026)
An investigative legal breakdown of the 7 hidden channels debt collectors use to trace your phone numbers, family contacts, employer, and address - and the exact statutory shields under RBI 2026 Directions and the DPDP Act, 2023 to stop them.
Read Article
willdrafting.in indias first online will drafting platform get your will in few minutes
Discover the swift and secure way to draft your will online in India today
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611