Received A DRT / Sarfaesi Notice? A Borrower’s And Guarantor’s Guide To Response Timelines And Defences
Essential steps and defenses for borrowers and guarantors facing DRT/Sarfaesi notices in India.
Anuj Anand Malik
Reviewed by AMA Legal Solutions
Key Takeaways: When you receive a DRT/SARFAESI notice, it's crucial to understand your rights under the RDB and SARFAESI Acts. Borrowers and guarantors must respond within specified timelines to protect their interests and explore potential defenses against asset recovery actions.
Introduction to Received A DRT / Sarfaesi Notice in India
Receiving a DRT or SARFAESI notice can be a daunting experience for borrowers and guarantors. It signifies the initiation of recovery proceedings by financial institutions due to unpaid debts. Understanding the implications of "Received A DRT / Sarfaesi Notice? A Borrower’s And Guarantor’s Guide To Response Timelines And Defences" is crucial in effectively navigating these proceedings. This guide will elucidate the statutory framework, response timelines, and available defenses, ensuring that borrowers and guarantors can make informed decisions.
Statutory Framework & Governing Legal Provisions
The statutory framework surrounding "Received A DRT / Sarfaesi Notice? A Borrower’s And Guarantor’s Guide To Response Timelines And Defences" primarily involves the Recovery of Debts and Bankruptcy Act, 1993 (RDB Act) and the Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002 (SARFAESI Act).
- RDB Act: Under Section 19, financial institutions are empowered to file an Original Application before the Debt Recovery Tribunal (DRT) for recovery of debts exceeding ₹20 lakh. The DRT operates on the principles of natural justice.
- SARFAESI Act: This act allows secured creditors to issue a demand notice under Section 13(2) to defaulting borrowers, providing them 60 days to discharge their liabilities. The act facilitates quicker recovery by enabling creditors to take possession of secured assets upon non-compliance.
These legislative measures are complemented by key judgments like Mardia Chemicals Ltd. v. Union of India (2004), upholding the SARFAESI Act's constitutional validity while emphasizing the borrower's right to a hearing before asset possession is executed.
Understanding DRT and Sarfaesi Act Implications
Understanding the implications of "Received A DRT / Sarfaesi Notice? A Borrower’s And Guarantor’s Guide To Response Timelines And Defences" requires a grasp of procedural nuances associated with both the DRT and SARFAESI frameworks. The DRT handles cases where secured creditors file applications for debt recovery, whereas the SARFAESI Act focuses on securitization and asset enforcement without court intervention.
Borrowers and guarantors receiving such notices should be acutely aware of the potential for asset possession and management measures under Section 13(4) if they fail to comply. They must also pay heed to the importance of timely objections under Section 13(3A) and subsequent rights to appeal against adverse measures.
Timeline for Responding to DRT/Sarfaesi Notices
When you have "Received A DRT / Sarfaesi Notice? A Borrower’s And Guarantor’s Guide To Response Timelines And Defences", adhering to the response timeline is critical. Here’s a breakdown of the key timelines:
| Stage | Event | Action Required | Response Deadline |
|---|---|---|---|
| DRT Notice | Original Application Filed | Submit written statement | Within 30 days |
| SARFAESI Notice | Demand Notice Issued | Submit objections | Within 60 days |
| SARFAESI Action | Possession Notice under Section 13(4) | File appeal with DRT | Within 45 days |
| DRT Decision | Adverse DRT Order | File appeal with DRAT | Within 30 days |
Missed deadlines can jeopardize the borrower's rights. It is imperative to act within the stipulated period to maintain one's legal standing.
Key Insights & Data Infographic
Visual summary, statistical trends & procedural breakdown
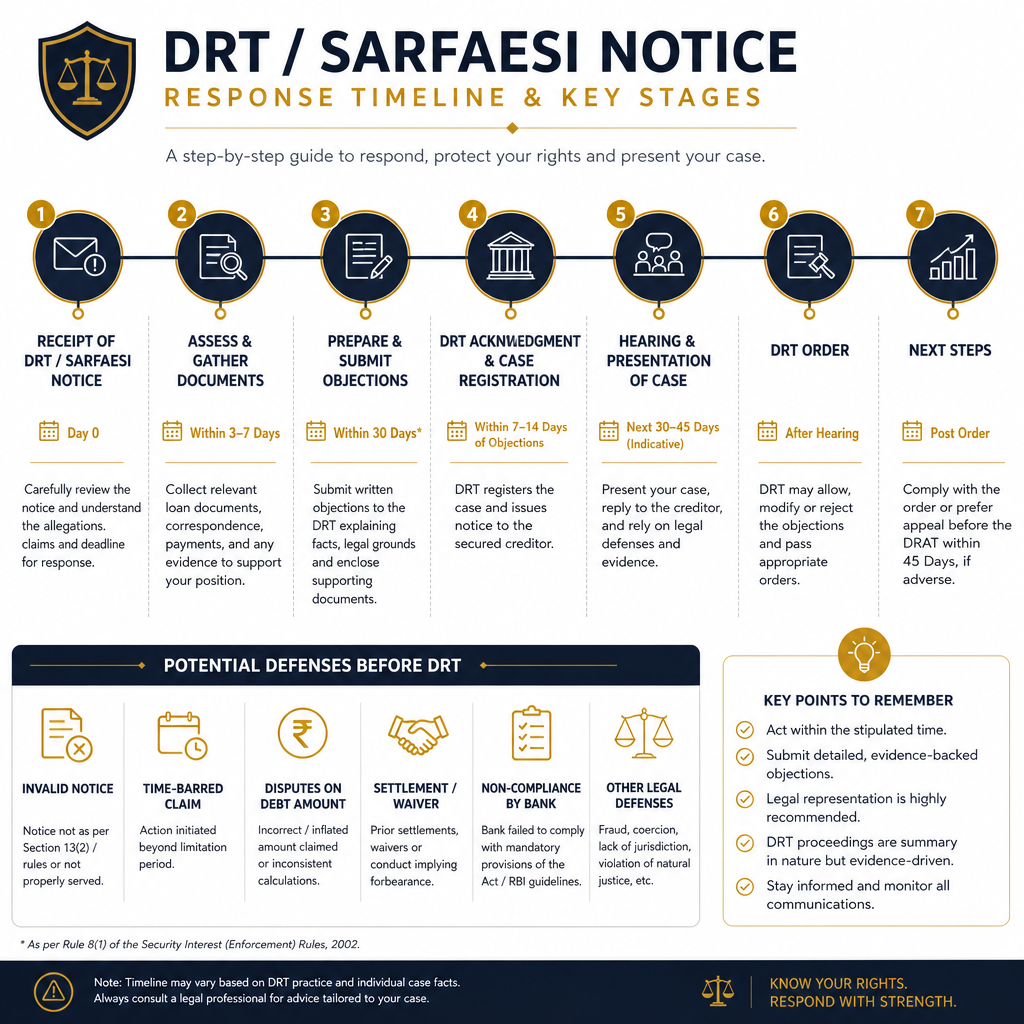
Prepared by AMA Legal Solutions Research & Analytics Team • Data & Compliance Overview

Halt Recovery Agent Harassment Legally
Available Defences for Borrowers and Guarantors
"Received A DRT / Sarfaesi Notice? A Borrower’s And Guarantor’s Guide To Response Timelines And Defences" also entails knowing the available defenses. Both borrowers and guarantors have specific legal defenses they can employ, including:
- Dispute of Amounts: Contesting the claimed amount if it's incorrect or not substantiated.
- Improper Classification: Challenging the classification of the account as a Non-Performing Asset (NPA).
- Procedural Lapses: Citing lapses or non-compliances by the creditor in issuing notices or in their conduct during the proceedings.
- Negotiation and Restructuring: Engaging creditors in amicable settlements or restructuring agreements to defer contention.
Borrowers and guarantors should work closely with legal professionals to explore these defense avenues comprehensively.
Practical Analysis of Common Defences
A practical understanding of common defenses under "Received A DRT / Sarfaesi Notice? A Borrower’s And Guarantor’s Guide To Response Timelines And Defences" allows better preparation for the legal challenges ahead. The legitimacy of objections and procedural adherence significantly influences outcomes:
- Data Discrepancies: Discrepancies between the creditor's claims and actual borrower records can be pivotal. Detailed documentation and independent audits can support your case.
- Asset Valuation: Objecting to undervaluation of assets before sale under the SARFAESI process is a smart line of defense. Supporting documentation and expert valuation reports may strengthen such objections.
- Engagement and Negotiation: Proactively engaging with financial institutions to negotiate terms or seek restructuring opportunities may mitigate adversarial proceedings. Engaging legal advisers early can enable concise negotiation strategies.
With professional legal backing, borrowers and guarantors can construct convincing arguments that stand rigorous scrutiny before the DRT or SARFAESI administrative proceedings.
Legal Safeguards, Consumer Rights, and Critical Risks to Avoid
Understanding "Received A DRT / Sarfaesi Notice? A Borrower’s And Guarantor’s Guide To Response Timelines And Defences" involves recognizing legal safeguards and essential consumer rights, as well as avoiding critical risks:
- Consumer Rights: Borrowers hold fundamental rights such as fair evaluation of assets, receiving detailed explanations in notices, and opportunities for representation.
- Rights of Guarantors: Guarantors can leverage defenses related to the contract nature and notice obligations under the Indian Contract Act.
- Risks to Avoid: Ignoring notices, missing statutory deadlines, and inadequately preparing defense documents are pitfalls that lead to unfavorable outcomes.
Strategic legal counsel, like that provided by banking and finance law experts at AMA Legal Solutions, can help avert these risks and preserve borrowers' rights through informed action and meticulous adherence to process timelines.
Strategic Conclusion: Securing Legal Assurance with AMA Legal Solutions
Navigating the implications of "Received A DRT / Sarfaesi Notice? A Borrower’s And Guarantor’s Guide To Response Timelines And Defences" is a complex process requiring strategic legal action. Engaging professional legal assistance is critical to ensure comprehensive defense formulations, timely filings, and rigorous representation. As India's premier legal firm, AMA Legal Solutions offers registered advocate counsel, bespoke legal drafting, and pan-India representation. With your rights and interests at the forefront, ensure your legal assurances are well secured by professional advocates skilled in drafting and dispute resolution. Don't navigate these proceedings alone; contact AMA Legal Solutions today for expert guidance tailored to your specific case.
This article provides general information and is not intended as legal advice. Please consult with a qualified legal professional to address your specific legal needs.
Popular Searches & Topics
Commonly searched legal queries and keywords related to this article
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.
AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages
Frequently Asked Questions
Related Articles
Why You Should Not Go to an Agency for Loan Settlement but a Lawyer or Law Firm
Understanding the benefits of legal expertise over agencies in loan settlements.
Read Article
Best Lawyer for Loan Settlement? Find Your Expert in 2026
Discover top strategies and insights for finding the best lawyer for loan settlement.
Read Article
Finding the Best Loan Settlement Agency in India (2026)
Unlock effective loan solutions with expert guidance on the best loan settlement agencies.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611