Exploring Loan Settlement Under OTS: Any Downsides?
Discover the potential drawbacks of settling loans under OTS.

Anuj Anand Malik
Reviewed by AMA Legal Solutions
Introduction to Loan Settlement Under OTS
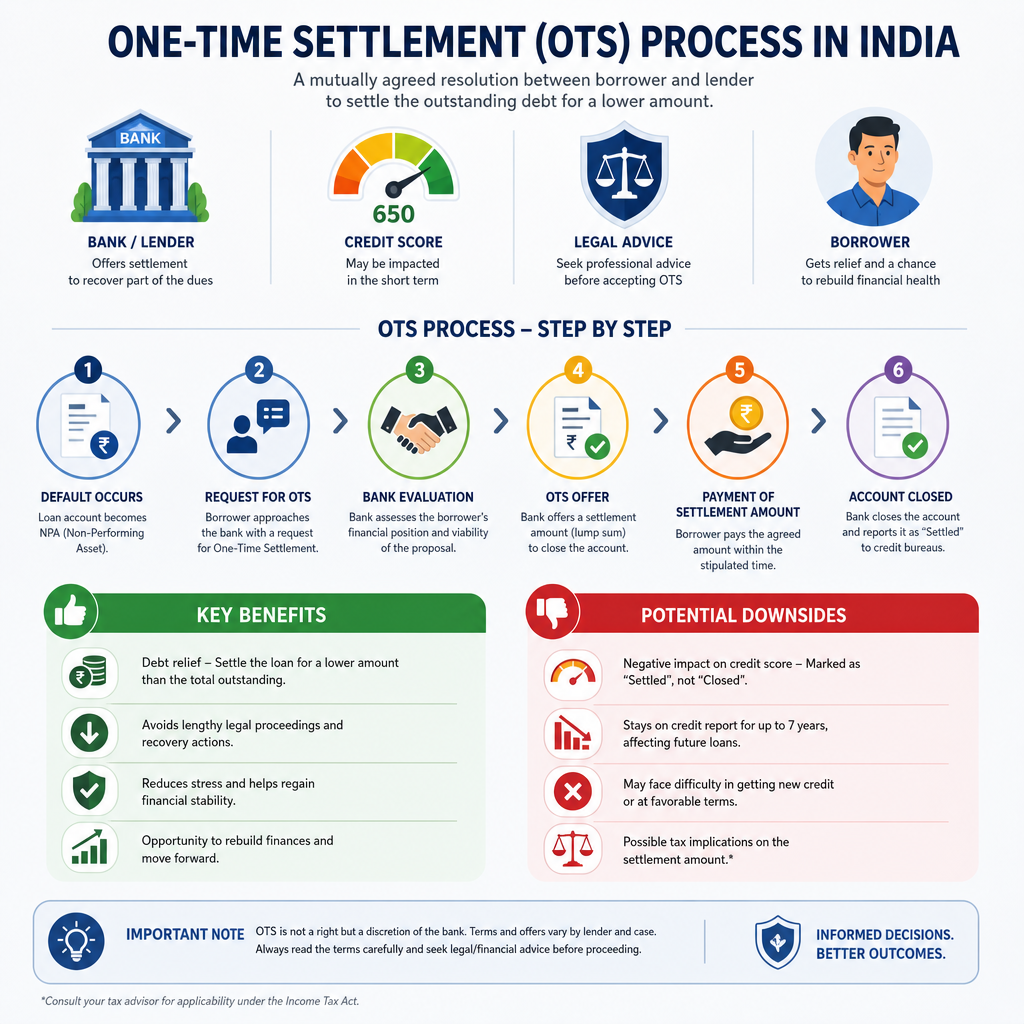
Loan settlement under the One-Time Settlement (OTS) scheme is a significant financial tool utilized by banks and financial institutions in India to manage and minimize their non-performing assets (NPAs). The Reserve Bank of India (RBI) provides guidelines for such settlements, which allow borrowers facing financial difficulties to negotiate a reduced repayment amount, thereby clearing their debt. While OTS offers a lifeline for both lenders and borrowers, it is essential to understand its intricacies and any downsides that may accompany this settlement method.
OTS is primarily aimed at recovering a portion of the loan that might otherwise be written off entirely due to the borrower's inability to repay. This process involves a settlement where the borrower pays a lump sum amount, often less than the outstanding balance, to settle the loan. The OTS mechanism is beneficial for banks as it helps in cleaning up their balance sheets and for borrowers who are often under significant financial stress. However, it is not without its challenges and potential pitfalls.
One of the key considerations in opting for loan settlement under OTS is the impact on the borrower's credit history. Participating in an OTS can significantly affect the borrower's credit score, as lenders typically report these settlements to credit bureaus. This could impede the borrower's ability to access future credit facilities. Borrowers must weigh this potential downside against the immediate relief from financial distress. For detailed assistance on managing such impacts, consider exploring banking and finance services offered by AMA Legal Solutions.
Another critical factor is the negotiation process itself. Borrowers must be equipped with robust negotiation strategies to ensure a favorable settlement amount. This often necessitates expert legal guidance to navigate the complexities of the process. Engaging services like loan settlement assistance provided by AMA Legal Solutions can be beneficial in these circumstances.
Furthermore, it's crucial for borrowers to understand the legal implications that can arise from entering into a loan settlement agreement. These may include waivers or releases that could affect future claims or disputes related to the loan. Legal expertise, such as that found in litigation services and contract drafting, can be invaluable in ensuring that all agreements are fair and transparent.
In conclusion, while the loan settlement under OTS provides a viable alternative for debt resolution, borrowers must exercise caution and seek professional advice to mitigate any potential downsides. The insights and services available from AMA Legal Solutions can be pivotal in navigating this complex financial landscape, ensuring that borrowers make informed decisions that align with their long-term financial health.
Understanding the Legal Framework of OTS
The One-Time Settlement (OTS) scheme is an instrumental mechanism in the Indian banking and finance sector, providing borrowers an opportunity to clear outstanding non-performing assets (NPAs) by paying a lump sum amount, which is generally less than the total due. The Reserve Bank of India (RBI) has established guidelines that banks must adhere to when implementing OTS schemes. These guidelines ensure that the settlement process is both transparent and equitable, protecting the interests of both the borrower and the lender.
The legal framework for OTS is primarily governed by the RBI's directives, which set out the eligibility criteria and procedural guidelines for borrowers and banks. It is crucial for borrowers to understand these regulations to make informed decisions. For a comprehensive understanding of financial laws and regulatory compliance, seeking assistance from expert legal advisors, such as AMA Legal Solutions' Banking and Finance Services, can prove beneficial.
One of the critical aspects of the OTS framework is the classification of a loan as an NPA, which triggers the eligibility for settlement under OTS. According to the RBI, a loan becomes an NPA when the borrower fails to meet interest or principal payments for a specified period. Once classified as an NPA, the borrower may negotiate with the bank for a one-time settlement. However, the terms and conditions of such settlements can vary significantly between financial institutions, necessitating thorough scrutiny and potentially the guidance of a professional service like AMA Legal Solutions' Loan Settlement Services.
Although OTS can offer a reprieve to distressed borrowers, it is not without its complexities and potential downsides. Legal repercussions and procedural intricacies may arise, which require a deep understanding of the statutory framework surrounding loan recoveries and settlements. Engaging with legal experts who specialize in litigation and drafting can help navigate these challenges effectively and ensure compliance with relevant legal standards.
Additionally, while the settlement might resolve immediate financial distress, it could impact the borrower's creditworthiness. Such settlements are often reported to credit information companies, affecting the borrower's credit score. Understanding the implications of OTS on one's financial standing and exploring alternative dispute resolution mechanisms, such as arbitration, can provide a more holistic view of the available options.
In conclusion, while the OTS framework provides a structured avenue for loan settlement, it is imperative for borrowers to be aware of the legal intricacies and potential repercussions. Consulting with professionals who are well-versed in the nuances of corporate and civil law, as well as other related legal fields, ensures that borrowers can make informed choices and navigate the settlement process effectively.
Benefits of Opting for OTS Loan Settlement
Choosing a One-Time Settlement (OTS) for loan resolution can offer substantial benefits for borrowers in India, particularly those struggling with financial constraints. This strategic move often provides a viable alternative to the traditional debt repayment process, offering relief to individuals and businesses alike. Below, we delve into the key advantages of opting for an OTS loan settlement.
Firstly, the primary benefit of opting for an OTS loan settlement is the opportunity to pay off a loan at a significantly reduced amount compared to the total outstanding balance. This reduction can be a significant financial relief, enabling borrowers to close their loans by paying a lump sum that is often much lower than what was originally owed. This can result in considerable savings, especially for borrowers who are under considerable financial stress.
Furthermore, an OTS loan settlement can help improve a borrower's financial stability and creditworthiness in the long run. Once the settlement amount is paid, the borrower's credit report is updated to reflect the closed status of the loan, which can potentially enhance their credit score over time. This is particularly beneficial for borrowers aiming to rehabilitate their credit history and regain eligibility for future loans or financial services. For detailed guidance on improving your credit score post-settlement, you can explore our Banking and Finance services.
Another significant advantage is the reduction in legal pressures. Borrowers who opt for an OTS settlement can avoid the potential legal actions that might arise from prolonged defaults, such as litigation or asset seizure. By settling the loan, borrowers can avert these legal complications and focus on rebuilding their financial health. For those dealing with legal challenges, our Litigation services offer comprehensive support.
OTS loan settlements also offer an opportunity for financial planning and restructuring. By resolving the debt quickly, borrowers can redirect their attention and resources towards more productive financial goals or investments. This could involve venturing into new business opportunities or investing in property. Our Real Estate services can assist clients in making informed investment decisions.
Finally, opting for an OTS settlement can offer peace of mind. The ability to close a loan account and move forward without the burden of debt weighing on one's shoulders cannot be overstated. This psychological benefit can lead to increased productivity and personal well-being. At AMA Legal Solutions, our experts are well-versed in guiding clients through the OTS process, ensuring that the path to financial freedom is as smooth as possible.
Potential Downsides: An Overview
Loan settlement under the One-Time Settlement (OTS) scheme can be an attractive option for borrowers struggling with debt repayment. However, it is crucial to be aware of the potential downsides before opting for this solution. While the OTS scheme offered by banks and financial institutions might provide a respite, it is not without its disadvantages that borrowers should carefully consider.
Firstly, opting for a loan settlement under OTS can significantly impact a borrower’s credit score. When a loan is settled, the bank typically updates the borrower's credit report with a "settled" status. This status indicates that the borrower did not repay the loan in full, which can remain on the credit report for several years. This negative mark can lower the borrower’s credit score and adversely affect their ability to secure loans in the future. For personalized guidance on maintaining a healthy credit profile, [AMA Legal Solutions' banking and finance services](https://www.amalegalsolutions.com/services/banking-and-finance) offer expert advice.
Additionally, the loan settlement process may come with hidden costs. While the immediate financial burden might reduce, banks often levy penalties and charges associated with the settlement. These costs could include processing fees and interest until the settlement date. It is advisable for borrowers to thoroughly review the terms and conditions associated with the OTS to avoid any unexpected financial obligations. For those navigating complex financial terms, [AMA Legal Solutions' loan settlement services](https://www.amalegalsolutions.com/services/loan-settlement) can provide invaluable assistance.
An often-overlooked downside is the potential tax implication. The amount waived by the bank in a settlement is often considered as "income" and may be taxable under the Income Tax Act. Borrowers should consult with a tax advisor to fully understand how the settlement might impact their tax liabilities. For comprehensive legal assistance in understanding tax and other implications, [AMA Legal Solutions' corporate services](https://www.amalegalsolutions.com/services/corporate) can be an excellent resource.
Moreover, loan settlement under OTS is not guaranteed for every borrower. Banks have specific eligibility criteria and may not approve every settlement application. Borrowers without a comprehensive understanding of the OTS criteria may face difficulties in successfully negotiating with their lenders. Legal experts at [AMA Legal Solutions' arbitration services](https://www.amalegalsolutions.com/services/arbitration) can guide borrowers in communicating effectively with financial institutions.
Lastly, the option to settle a loan does not erase the underlying financial issues that led to the debt. Borrowers should address their financial habits to prevent future debt accumulation. In situations requiring ongoing financial management or negotiation, [AMA Legal Solutions' litigation services](https://www.amalegalsolutions.com/services/litigation) can offer strategic legal support to ensure long-term financial health.
Impact on Credit Score and Financial Reputation
While opting for a loan settlement under the One-Time Settlement (OTS) scheme can provide immediate relief from the burden of mounting debts, it is crucial to consider its implications on your credit score and financial reputation. The Reserve Bank of India (RBI) guidelines allow banks to offer OTS as a strategic approach to recover non-performing assets, but this route is often seen as a last resort.
One of the primary downsides of loan settlement under OTS is its significant impact on your credit score. When a borrower settles a loan through OTS, it is usually reported to credit bureaus as a "settled" account, rather than "paid in full." This notation indicates that the borrower did not fulfill the original loan terms, which can negatively affect the credit score. This reduction in credit score can impact future borrowing capacity, making it more challenging to secure loans, credit cards, or even favorable interest rates in the future. At AMA Legal Solutions, we provide expertise in banking and finance law to help navigate these complex situations.
Additionally, a loan settlement can cast a long shadow on your financial reputation. Financial institutions may consider a settled loan when evaluating loan applications, as it reflects on the borrower's creditworthiness and reliability. This may lead to increased scrutiny or even denials when applying for new credit facilities. It is important to keep these potential repercussions in mind and consult professional services such as loan settlement assistance from experts to make informed decisions.
The ramifications of a loan settlement are not limited to just the credit score. It can also affect personal and business financial transactions. Many businesses depend on credit and loans to maintain cash flow and fund expansion. A tarnished financial reputation can hinder business opportunities, making it difficult to engage in lucrative deals or partnerships. In such cases, seeking guidance from legal experts in corporate law can provide strategic insights to mitigate these risks.
Recovery from a loan settlement's impact on credit and financial reputation can be a long and arduous process. It often requires proactive measures, such as timely payment of existing debts, maintaining low credit utilization, and avoiding taking on additional high-interest debt. Legal experts in arbitration and civil law can offer tailored strategies to help rebuild creditworthiness over time.
Before deciding on a loan settlement under OTS, consider comprehensive legal consultation from drafting and litigation experts to weigh the benefits against the potential long-term impacts on your financial health and reputation. This foresight can be instrumental in making decisions that align with your long-term financial goals.
Legal Implications and Compliance Issues
Engaging in a loan settlement under the One-Time Settlement (OTS) scheme can present several legal implications and compliance issues that borrowers must carefully consider. Understanding these factors is critical for ensuring that the settlement process does not inadvertently lead to further legal complications. Borrowers must be thoroughly aware of the implications of such settlements before proceeding.
Firstly, a loan settlement under OTS can have significant consequences on the borrower's credit score. While the settlement may resolve the immediate debt issue, it is often recorded as a "settled" status rather than "paid in full" in the credit report. This can adversely affect the borrower's creditworthiness, potentially making it difficult to secure future loans. An individual's ability to negotiate better terms on new credit facilities could be compromised, which makes it essential to seek expert advice from professionals such as banking and finance experts.
Additionally, borrowers must ensure complete compliance with the terms stipulated in the OTS agreement. Non-compliance or misunderstanding of these terms can lead to legal disputes or additional financial liabilities. Legal professionals specializing in loan settlement can provide guidance on the terms of the settlement to ensure they align with the borrower's financial capabilities and goals.
There are also potential tax implications to consider. The difference between the original loan amount and the settled amount may be treated as taxable income by the Income Tax Department under certain circumstances. It is essential for borrowers to consult with tax professionals to understand the tax obligations arising from the settlement and ensure full compliance with tax laws. This precaution can prevent future tax liabilities and ensure adherence to legal requirements.
Moreover, the legal framework governing OTS can vary significantly across different financial institutions, thus making it paramount for borrowers to understand the specific legal stipulations of their lender. Engaging with a legal service provider experienced in corporate law or civil law can help navigate these complexities, ensuring a thorough understanding of the implications before entering into a settlement agreement.
Finally, borrowers should be aware of the potential for arbitration or litigation if disputes arise from the settlement agreement. It is advisable to have a legal strategy in place for any potential disputes that may arise during or after the settlement process. Leveraging services from professionals in arbitration and litigation can provide the necessary legal support to protect the borrower's interests.

Halt Recovery Agent Harassment Legally
Long-term Financial Consequences
Opting for a loan settlement under the One-Time Settlement (OTS) scheme can seem like a viable solution for borrowers facing financial difficulties. However, it's important to weigh the potential long-term financial consequences before proceeding. While the immediate relief might be appealing, there are several downsides that could impact your financial health in the future.
Firstly, settling a loan under OTS can significantly affect your credit score. When a borrower chooses this route, the lender typically reports the account status to credit bureaus as "settled" rather than "closed", which implies that the full amount was not repaid. This can adversely affect your credit score for several years, making it difficult to secure future loans or credit lines. Consequently, you might find yourself ineligible for competitive interest rates or even face outright denials of credit applications.
Furthermore, a settled loan can raise red flags with potential lenders or financial institutions when you apply for any new form of credit or loan. They might perceive you as a high-risk borrower, demanding additional assurances or higher interest rates. This can impact not only personal loans but also extend to other financial products such as home loans or credit cards. For a comprehensive understanding of how loan settlements can affect your financial pursuits, consider exploring the Banking and Finance services provided by AMA Legal Solutions.
Moreover, settling a loan may have tax implications. Under Indian tax laws, the amount waived off during the settlement process could be considered as a taxable income. This unexpected tax liability could strain your finances further, especially if you were not prepared for this additional burden. Consulting a legal expert in taxation laws might provide valuable insights into managing these potential liabilities.
In addition to financial repercussions, there might be legal consequences if not handled properly. A poorly negotiated settlement agreement can lead to future disputes or legal challenges. This is where the expertise of professionals offering loan settlement services can be invaluable. They can assist in ensuring that all terms are clearly defined and legally binding, reducing the risk of complications later on.
Finally, the psychological impact of carrying a "settlement" label can not be understated. The stress associated with impaired creditworthiness and potential financial instability can take a toll on your overall well-being. Seeking advice from professionals in litigation or corporate laws can provide strategic insights into mitigating these consequences and planning effectively for future financial endeavors.
Alternative Options to OTS Loan Settlement
While opting for a One-Time Settlement (OTS) can be a viable solution for many borrowers facing financial distress, it is important to explore alternative options that might better suit individual circumstances. Not all borrowers will find OTS to be the optimal choice, especially considering potential credit score impacts and the fact that it might not lead to full debt forgiveness. Below are some alternatives that borrowers can consider.
Debt Restructuring
Debt restructuring is a popular alternative for those wishing to avoid the downsides associated with OTS, such as adverse effects on credit scores. This approach involves negotiating new terms with your lender, potentially lowering the interest rates or extending the loan tenure. This can help reduce the monthly repayment burden. Financial institutions in India, under the guidance of the RBI, offer various restructuring schemes. For professional assistance in negotiating favorable terms, borrowers may consult with legal experts specializing in banking and finance.
Loan Refinancing
Refinancing a loan is another alternative worth considering. This involves taking a new loan to pay off the existing one, ideally with more favorable terms such as a lower interest rate or longer repayment periods. This option can be particularly attractive if the borrower’s credit situation has improved since the original loan agreement. It is advisable to seek guidance from loan settlement professionals to assess if refinancing aligns with your financial goals.
Debt Consolidation
If managing multiple debts becomes overwhelming, debt consolidation might be the solution. This involves combining all debts into a single loan, often at a reduced interest rate, simplifying the repayment process. It is critical to evaluate the total cost over the loan term, as consolidation may extend the repayment period. Engaging with experts who offer corporate financial solutions can provide insights into whether this option suits your debt profile.
Legal Arbitration
Engaging in arbitration can be a strategic move for resolving disputes involving loan terms without resorting to litigation. This method involves a neutral third party who facilitates a mutually agreeable solution between the lender and borrower. Arbitration can often be quicker and less costly than court proceedings. Borrowers can leverage arbitration services to navigate these proceedings effectively.
In conclusion, while OTS is a widely recognized method for managing distressed loans, considering alternative options can lead to more favorable outcomes depending on personal financial scenarios. Consulting with professionals equipped with expertise in various drafting and litigation techniques can ensure that borrowers make informed decisions tailored to their unique needs.
Expert Opinions on Loan Settlement Under OTS
Loan settlement under the One-Time Settlement (OTS) scheme often attracts diverse opinions from industry experts. One primary perspective is that while OTS offers a feasible route for borrowers to settle their debts without enduring lengthy legal procedures, it can also bring certain downsides that need careful consideration. Financial analysts and legal professionals from institutions like AMA Legal Solutions frequently discuss both the advantages and potential pitfalls of the OTS approach.
From a legal standpoint, experts highlight that while OTS can alleviate immediate financial burdens, it may lead to long-term credit implications. Borrowers who settle their loans under OTS might find themselves marked with “settled” status on their credit reports, which can adversely impact their credit scores. This status is often perceived negatively by future lenders, affecting the borrower's ability to secure loans at favorable terms. This aspect is particularly crucial for individuals and businesses looking to engage in further financial dealings or expand into sectors such as real estate or corporate ventures.
Financial advisors also caution that the negotiation process involved in OTS can be arduous and requires a thorough understanding of one's financial standing. Missteps in this process can lead to unfavorable settlement terms, making expert legal guidance indispensable. Consulting firms like AMA Legal Solutions provide essential support in navigating these complex negotiations, ensuring that the borrowers are well-equipped to deal with potential drawbacks.
Furthermore, experts in arbitration and litigation warn that OTS settlements might not always be the end of the road in terms of legal obligations. There can be scenarios where creditors might pursue further legal actions if the settlement terms are not fulfilled satisfactorily. This highlights the necessity of engaging with seasoned professionals in litigation and arbitration who can provide robust legal defense and advice.
Finally, some experts argue that OTS might inadvertently encourage a culture of non-repayment among borrowers, as they may come to rely on such settlements as an escape route from financial responsibilities. This perspective is significant in the context of maintaining a healthy credit discipline across sectors, including entertainment and intellectual property rights. Ultimately, the decision to proceed with OTS should be made after a comprehensive analysis of one's financial landscape and in consultation with legal experts capable of assessing the broader implications of such settlements.
Case Studies of Loan Settlement Under OTS
Understanding the practical implications of loan settlements under the One-Time Settlement (OTS) scheme is crucial. Let's examine a few case studies that highlight the dynamics, both positive and negative, that borrowers might encounter during the process. These insights will provide a deeper understanding of the potential downsides and the strategic considerations involved in opting for an OTS.
Case Study 1: SME Borrower in Textile Industry
Consider a small and medium enterprise (SME) in the textile industry based in Surat, Gujarat, which faced financial troubles due to market downturns and increased competition. The company had an outstanding loan of ₹2 crore. With the help of a customized loan settlement plan, the bank offered a settlement of ₹1.5 crore under the OTS scheme. While this reduced the immediate financial burden, the company faced a significant downside: its credit score suffered due to the settlement. This affected its ability to secure future financing, which is a common repercussion in loan settlements. For more insights on handling such financial intricacies, you can explore our banking and finance services.
Case Study 2: Individual Home Loan Settlement
An individual in Mumbai had taken a home loan amounting to ₹50 lakh and fell behind on payments due to sudden unemployment. The bank offered an OTS of ₹40 lakh. While the immediate benefit was the reduction in outstanding debt, the individual found that the settlement was recorded with credit bureaus, impacting their CIBIL score. This made future loan applications more challenging. It's important to weigh these factors before deciding on an OTS, and seeking professional guidance through our loan settlement services can be beneficial.
Case Study 3: Corporate Loan in IT Sector
A tech startup in Bengaluru faced a liquidity crisis due to delayed payments from clients, affecting its ability to service a corporate loan of ₹5 crore. The bank provided an OTS settlement of ₹4 crore. Although this eased the immediate cash flow issues, the downside was evident when the company's growth plans were hampered by the inability to leverage additional credit. The strategic implications of such decisions can be complex, and our corporate services offer in-depth advisory for businesses navigating these challenges.
These case studies illustrate that while OTS can provide a lifeline to distressed borrowers, it comes with potential downsides such as impaired creditworthiness and limited future borrowing capacity. Borrowers should carefully evaluate these aspects in consultation with legal and financial experts. For more detailed assistance, consider our drafting and litigation services to navigate the complexities of loan settlements effectively.
How to Decide if OTS is Right for You
Deciding whether the One-Time Settlement (OTS) is the right strategy for you involves careful consideration of your financial situation, the specifics of your loan, and the potential impact on your credit history. The OTS option can offer relief by allowing you to settle your debt for less than the full amount, which is appealing for many borrowers. However, it is important to thoroughly evaluate if this path aligns with your long-term financial goals and obligations.
First, assess your current financial health. Are you struggling to meet your loan repayments due to a significant decrease in income or unforeseen expenses? If so, OTS might provide a viable solution to alleviate immediate financial pressure. However, you should also consider the downsides of loan settlement under OTS, such as the potential impact on your credit score and future borrowing capacity. A comprehensive evaluation of your financial status can be guided by a financial expert, like those available through AMA Legal Solutions' banking and finance services.
Next, evaluate the terms being offered by your creditor under the OTS. It is crucial to understand the total amount you are required to pay, any up-front costs, and the timeline for making these payments. Compare these terms against your current financial capabilities and consider if you can realistically meet the requirements without further financial strain. Consulting with a legal professional can help clarify these terms and assist with negotiation, ensuring that you are making an informed decision. You can explore options with loan settlement services at AMA Legal Solutions.
Consider the long-term effects on your credit profile. While settling a loan might relieve immediate debt pressure, it could negatively impact your credit score, making it harder to obtain new loans or credit in the future. Before proceeding, weigh the immediate benefits against the potential long-term credit implications. Engaging with experts in corporate and civil legal services can provide insights into managing these outcomes effectively.
Moreover, evaluate alternative options to OTS. Depending on your situation, restructuring your existing loan or seeking financial advice might offer a better strategy. Consulting with an arbitration or litigation expert at AMA Legal Solutions can provide a broader perspective on the available options and help you decide the best course of action.
In conclusion, deciding if OTS is right for you requires a detailed analysis of your financial situation, loan specifics, and long-term credit implications. Seeking professional advice from legal and financial experts can aid in making a well-informed decision that aligns with your financial goals. With the right guidance, you can navigate the complexities of loan settlement under OTS effectively.
Conclusion: Weighing the Pros and Cons
The Loan Settlement under One-Time Settlement (OTS) can be an enticing option for borrowers facing financial distress, yet it is imperative to carefully weigh the pros and cons before proceeding. On the positive side, OTS can significantly reduce the burden of debt by allowing borrowers to settle their debts for a lesser amount than owed. This can provide immediate financial relief and help in avoiding the long-term ramifications of rising debt. Furthermore, opting for an OTS can spare individuals the stress and uncertainty associated with prolonged negotiations with lenders.
However, there are notable downsides that cannot be overlooked. One significant disadvantage is the impact on credit scores. Opting for an OTS may be recorded as a default on the borrower's credit history, which can affect their ability to secure loans in the future. This negative mark may persist for several years, potentially increasing interest rates on future borrowings. For those seeking to engage in larger financial ventures, such as real estate investments, this could pose substantial challenges. At AMA Legal Solutions, we provide expert guidance to help clients understand the implications of such decisions on their financial health.
Furthermore, the possibility of hidden costs and fees associated with OTS should be considered. Lenders may include additional charges within the settlement process, which can reduce the effectiveness of the financial relief sought. It is crucial to read the fine print and understand all terms and conditions, a step that can be navigated effectively with the help of professional loan settlement services.
Another potential downside is the limited scope for negotiation once an OTS has been finalized. In contrast to continuous debt restructuring, which allows for periodic adjustments based on changing financial circumstances, an OTS is a one-time offer. This could be restrictive for borrowers who might anticipate further financial hurdles. For those in need of ongoing financial strategy and legal support, our corporate and arbitration services provide robust frameworks for managing such complexities.
In conclusion, while a Loan Settlement under OTS can offer immediate relief, it is essential to carefully consider the long-term implications. A comprehensive evaluation of personal financial situations, combined with professional legal advice, can aid borrowers in making an informed decision. The experienced team at AMA Legal Solutions stands ready to assist clients in navigating these intricate financial waters, ensuring that the chosen path aligns with their broader financial and legal objectives.
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages





Client Reviews
"The legal advisors at AMA Legal Solutions are experts in managing OTS agreements. Their assistance ensured my financial future remains secure."
Vikram Joshi
"AMA Legal Solutions provided exceptional guidance during my OTS negotiation, ensuring a favorable outcome. Highly recommended!"
Arjun Sharma
"Choosing AMA Legal Solutions was the best decision for my loan settlement. Their strategic advice was crucial to achieving a fair settlement."
Anjali Desai
"Excellent service! Their expertise in banking law helped me understand the implications of my loan settlement thoroughly. Thank you, AMA Legal Solutions."
Rajesh Nair
"The team at AMA Legal Solutions was knowledgeable and supportive, making the complex OTS process seamless and stress-free."
Priya Kapoor
Frequently Asked Questions
Related Articles

RuPay Credit Card on UPI Default & Credit Line on UPI Settlement (2026)
Micro-transactions on RuPay UPI Credit Cards and pre-approved 'Credit Lines on UPI' have triggered a massive wave of 42%+ APR revolving debt traps. Find out if defaulting blocks your personal savings UPI and how to settle RuPay UPI credit dues for 30%–50%.
Read Article
Paytm, PhonePe & BharatPe Daily EDI Merchant Loan Settlement (2026)
Drowning in Equated Daily Installment (EDI) merchant loans where 100% of your daily QR Soundbox collections are auto-swept before you can pay suppliers or rent? Learn how retail shopkeepers and MSMEs legally halt QR sweeps and negotiate a 50%+ OTS.
Read Article
Can Bank or Loan App Remotely Lock Phone for EMI Default? RBI Rules (2026)
An investigative breakdown of RBI's Remote Device Locking Directions—explaining why lenders cannot lock your phone for personal loans, the mandatory 30/60 DPD safeguards on financed devices, the Rs. 250/hour delay penalty, and how to settle device & app loans.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611