Comprehensive Loan Settlement Guide: Insights from a Veteran
Master loan negotiations with expert tips from a 25-year seasoned recovery agent.

Anuj Anand Malik
Reviewed by AMA Legal Solutions
Introduction to Loan Settlement Strategies
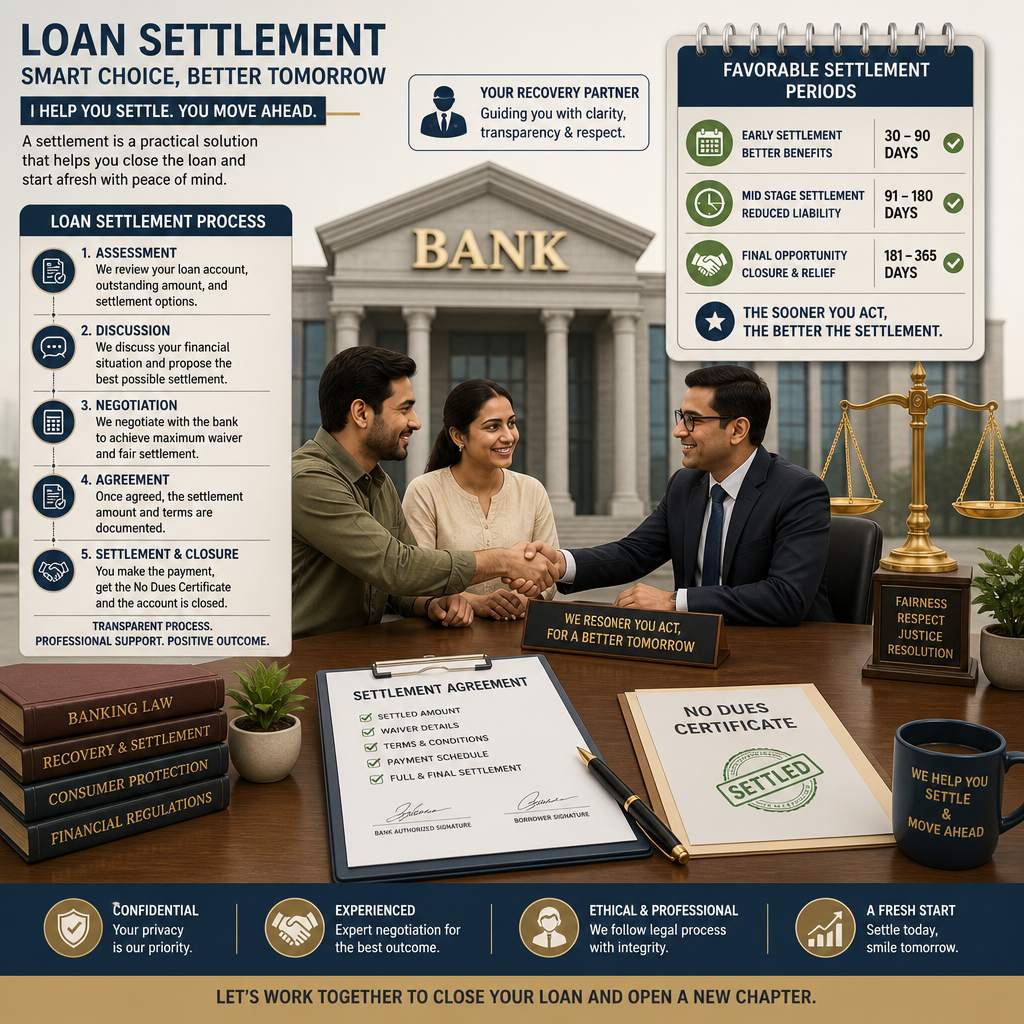
Loan settlement is a pivotal option for borrowers facing financial distress and the pressure of impending recovery actions. With 25 years of experience navigating the complexities of loan settlements, a veteran recovery agent can offer invaluable insights into effective negotiation techniques and settlement strategies. Understanding the nuances of how banks and financial institutions operate is fundamental to securing a favorable settlement.
At the core of any successful loan settlement strategy is the foundation of clear communication with the lender. Borrowers must articulate their financial hardships and propose realistic repayment plans that align with their current capabilities. A seasoned recovery agent emphasizes the importance of presenting documented evidence of financial constraints, such as loss of employment or medical emergencies, to support the case for settlement.
Furthermore, recognizing the bank's viewpoint-its desire to recover as much of the outstanding amount as possible-enables borrowers to craft proposals that are mutually beneficial. Timing is critical; approaching lenders during their quarterly or financial year-end periods can lead to more favorable terms, as banks are keen on closing books with resolved accounts.
Finally, understanding the legal landscape, such as the RBI guidelines on loan recovery, equips borrowers with the knowledge to protect their rights throughout the settlement process. This comprehensive approach ensures that loan settlements are negotiated effectively, minimizing stress and maximizing outcomes for all parties involved.
Understanding the Legal Framework for Loan Settlements
In the realm of loan settlements in India, understanding the legal framework is crucial for borrowers seeking a resolution with financial institutions. The Reserve Bank of India (RBI) guidelines serve as the cornerstone, dictating the processes banks must follow during recovery. These guidelines aim to ensure fair treatment of borrowers while maintaining the integrity of the banking system.
The SARFAESI Act and the Debt Recovery Tribunal (DRT) provide statutory mechanisms for banks to recover debts. Under the SARFAESI Act, banks have the authority to seize and sell assets pledged as collateral, circumventing lengthy judicial processes.
Borrowers must be aware of their rights, such as the right to receive a 60-day notice before asset seizure, offering time to negotiate or repay. Additionally, the Insolvency and Bankruptcy Code (IBC) offers another framework for resolving insolvency and bankruptcy, which can also impact loan settlements.
Understanding these laws and leveraging them effectively can significantly influence negotiation outcomes. Engage with experienced legal counsel to navigate this complex landscape and achieve a favorable settlement.
Identifying the Role of Recovery Agents in Settlements
Recovery agents play a crucial role in the loan settlement process, acting as intermediaries between banks and borrowers. Their primary function is to facilitate communication and negotiation to recover overdue amounts. With over 25 years of experience, seasoned agents understand the nuances of debt recovery while adhering to legal frameworks and ethical guidelines.
Experienced agents often begin by assessing the borrower's financial situation. They aim to establish a realistic repayment plan that balances the bank's interests with the borrower's capacity. An in-depth understanding of the borrower's circumstances helps agents propose viable settlement options, which can be a win-win for both parties.
The Process Involved
- Initial Contact: Agents reach out to borrowers through phone calls, emails, or letters, initiating the settlement dialogue.
- Financial Analysis: Agents assess the borrower's financial standing to propose feasible repayment terms.
- Negotiation: By leveraging their expertise, agents negotiate terms that align with RBI guidelines and consumer rights, ensuring fair treatment.
- Documentation: Once a settlement is agreed upon, agents oversee the documentation process to formalize the agreement.
It is vital for borrowers to recognize that while recovery agents represent the bank, they are bound by regulations that prevent harassment or intimidation. Knowing your rights and maintaining clear communication can lead to a more favorable settlement outcome.
How Banks Classify Non-Performing Assets (NPAs)
Understanding how banks classify Non-Performing Assets (NPAs) is crucial for borrowers facing financial difficulties. An asset becomes non-performing when it ceases to generate income for a bank. Typically, this occurs when interest or principal payments are overdue for 90 days or more. Classification of NPAs is essential, as it determines the bank's strategy for recovery.
Stages of NPA Classification
- Substandard Assets: These are assets overdue for less than 12 months. Banks may attempt to recover through softer measures, offering borrowers a chance to renegotiate terms.
- Doubtful Assets: If the asset remains non-performing for over 12 months, it moves to this category. Recovery strategies intensify, often involving legal notices and possible initiation of recovery proceedings under the SARFAESI Act or through Debt Recovery Tribunals.
- Loss Assets: When the bank or auditors identify that the asset is virtually irrecoverable, it is classified as a loss asset. Here, banks may resort to selling the asset to asset reconstruction companies.
Banks follow guidelines issued by the Reserve Bank of India (RBI) for classifying NPAs, which ensures uniformity and transparency. Understanding these classifications helps borrowers anticipate bank actions and strategize their repayment or settlement plans effectively.
What Banks Often Keep Hidden from Borrowers
Borrowers frequently remain unaware of certain aspects that banks prefer to keep under wraps. These hidden elements often affect loan settlement processes and outcomes. Understanding these can significantly empower borrowers facing financial distress.
Internal Classification of NPAs
Banks internally categorize Non-Performing Assets (NPAs) into subcategories. This classification influences the settlement approach. For instance, accounts nearing the end of the financial year may receive more lenient settlement offers to clean up the balance sheet.
Recovery Incentives
Recovery agents are sometimes incentivized based on recoveries. This means they might push for settlements or repayments aggressively. Borrowers should remain cautious and negotiate calmly, knowing that agents have targets to meet.
Settlement Timing Strategies
Banks often utilize strategic timing in sending settlement offers. Offers might be delayed to maximize pressure or provided at quarter-end when banks aim to show improved financials. Borrowers can leverage this timing knowledge to initiate negotiations.
- End-of-year pressures can lead to better settlement terms.
- Quarter-end financial reporting periods are critical for banks.
Impact of Credit Scores on Settlements
Banks rarely divulge how settlements might affect credit scores. While settling can affect your credit history, negotiating to mark the account as “settled in full” can mitigate negative impacts.
Knowing these hidden factors allows borrowers to approach loan settlements with strategy, significantly improving negotiation outcomes.
Legal Rights of Borrowers Against Recovery Agents
Borrowers in India have specific legal rights when dealing with bank recovery agents. First and foremost, borrowers should know that recovery agents must adhere to RBI guidelines which mandate respectful and non-intrusive behavior. Any form of harassment, intimidation, or public shaming is strictly prohibited. Recovery calls are only permissible between 7 AM and 7 PM, ensuring borrowers' privacy and peace.
Communication Protocol
- Agents must communicate in a professional manner and are required to provide accurate identification, including bank details and authorization letters.
- Borrowers can request all communication to be done in writing, providing a documented record of interactions.
Legal Recourse
If a borrower feels threatened or harassed, they can lodge a complaint with the bank’s grievance cell or escalate it to the Banking Ombudsman. It’s advisable to document all interactions with recovery agents, including call times and spoken words, which can serve as evidence in disputes.
Exceptions and Practical Advice
While recovery agents are allowed to recover dues, they cannot confiscate property or assets without due legal process. Borrowers are advised to negotiate settlements amicably and involve legal counsel if necessary. Understanding these legal protections can empower borrowers to handle recovery situations confidently.

Halt Recovery Agent Harassment Legally
Effective Communication Tactics with Recovery Agents
Engaging with recovery agents can be a daunting experience, yet effective communication is key to navigating this process. Here are some practical tactics to employ:
Understand Their Role
Recovery agents are tasked with collecting overdue payments, but they must adhere to legal and ethical guidelines. Familiarize yourself with these regulations to better advocate for your rights. The RBI mandates that agents cannot harass or use threatening language.
Maintain Composure and Clarity
Stay calm and composed during conversations. Clearly articulate your current financial situation and propose a realistic repayment plan. For instance, if you've lost your job, mention your proactive efforts to secure employment and request additional time.
Request Written Communication
Whenever possible, request that communication be conducted in writing. This provides a documented trail of your interactions and can be crucial if disputes arise. An example statement could be: "Please send any repayment proposals or demands via email for clarity and record-keeping."
Negotiate Amicably
Approach negotiations with a collaborative mindset. Express willingness to settle but highlight any constraints you face. For example, "I am committed to resolving this and can manage a monthly payment of INR 5,000. Could this be acceptable?"
By employing these strategies, you can effectively communicate with recovery agents, leading to more favorable settlement outcomes.
Step-by-Step Process for Negotiating Settlements
Successfully negotiating a loan settlement requires a strategic approach. Here’s how you can efficiently manage the process:
Step 1: Assess Your Financial Position
Begin by evaluating your financial situation. Calculate your income, expenses, and existing debts to determine what you can realistically offer as a settlement.
Step 2: Contact the Recovery Agent
Reach out to the recovery agent through email or a formal letter. Clearly express your intention to settle the debt and propose an initial offer based on your assessment.
Step 3: Gather Supporting Documentation
Compile evidence such as pay slips, bank statements, and any correspondence with the bank. These documents will support your financial claims during negotiations.
Step 4: Negotiate Terms
- Present your offer and be prepared to discuss it.
- Negotiate interest rates, penalties, and repayment schedules.
- Remain calm and flexible to reach a mutually agreeable solution.
Step 5: Get the Agreement in Writing
Once terms are agreed upon, ensure all details are documented in a formal settlement agreement. This protects both parties and provides legal evidence of the settlement.
Step 6: Follow Through
Adhere to the agreed terms and make payments as scheduled. Keep records of all transactions and communications for future reference.
Mistakes That Can Jeopardize Settlement Success
Successfully settling a loan with a recovery agent requires strategic thinking and attentive communication. Here are common mistakes that borrowers often make:
Ignoring Communication
When borrowers avoid calls or fail to respond to notices, recovery agents may escalate the issue, leading to legal actions. It's crucial to maintain open communication lines with agents and creditors.
Emotional Responses
Getting overly emotional or confrontational with recovery agents can harm negotiation efforts. Instead, discuss repayment options with a calm and solution-oriented approach.
Incomplete Documentation
Settlements require comprehensive documentation. Providing incomplete or inaccurate information can delay the process. Always have up-to-date financial statements, income proofs, and loan account details ready.
Overpromising
Committing to unrealistic repayment terms just to appease recovery agents can lead to future defaults. Clearly assess your financial capacity and negotiate feasible terms.
Ignoring Legal Advice
Many borrowers underestimate the importance of legal counsel. A seasoned banking lawyer can provide invaluable insights, protect your rights, and enhance settlement outcomes.
Avoiding these pitfalls can greatly improve your chances of achieving a favorable loan settlement. Establishing a cooperative and informed dialogue with recovery agents is key to successfully resolving financial difficulties.
RBI Guidelines on Loan Repayment and Settlement
The Reserve Bank of India (RBI) provides a structured framework for loan repayment and settlement, ensuring transparency and borrower protection. These guidelines are crucial for borrowers to understand their rights and obligations.
Key Aspects of RBI Guidelines
- Fair Practice Code: Banks and financial institutions must adhere to the RBI's Fair Practice Code. This includes clear communication regarding terms, conditions, and any changes in interest rates or charges.
- Grievance Redressal Mechanism: Borrowers must have access to an effective grievance redressal system. RBI mandates banks to resolve complaints within a stipulated timeframe.
- Loan Restructuring: RBI permits restructuring of loans under specific conditions, especially when borrowers face financial difficulties. This includes extending the loan tenure or altering repayment terms.
- Settlement Offers: Any settlement offer made by banks must be transparent and fair. Borrowers are entitled to receive a written document of the settlement terms.
Implications for Borrowers
Understanding RBI guidelines can empower borrowers to negotiate effectively and safeguard their interests. For instance, if a bank deviates from the Fair Practice Code, borrowers can raise a complaint with the Banking Ombudsman. By staying informed, borrowers can better manage loan settlement processes and mitigate financial stress.
Case Studies: Successful Loan Settlement Stories
Understanding how loan settlements can be successfully negotiated is crucial for borrowers facing financial distress. Below are two real-world examples demonstrating effective loan settlement strategies:
Case Study 1: SME's Pathway to Debt Resolution
A small manufacturing enterprise faced mounting debts of ₹50 lakh due to a market downturn. The recovery agent initiated discussions by acknowledging the company's financial constraints. By presenting a detailed financial plan, the borrower demonstrated future profitability. Consequently, the bank agreed to a one-time settlement of ₹30 lakh, payable over 12 months. This was achieved through transparent communication and presenting realistic financial projections, ensuring both parties found a mutually beneficial solution.
Case Study 2: Personal Loan Restructuring Success
An individual borrower, overwhelmed by a ₹10 lakh personal loan after unexpected medical expenses, proactively contacted the recovery agent. The borrower provided medical records and a repayment proposal. The recovery agent, recognizing genuine hardship, facilitated a reduction to ₹7 lakh, to be paid over 18 months with no additional interest. This case highlights the importance of documentation and upfront communication, proving that honesty and clear records can lead to favorable settlements.
These examples emphasize strategic negotiation and documentation as key elements in successful loan settlements. By understanding these dynamics, borrowers can navigate their financial challenges with greater confidence.
Tips for Long-Term Financial Stability Post-Settlement
Achieving a loan settlement is a significant relief, but maintaining financial stability afterward is crucial. Here are some expert tips to ensure long-term financial well-being:
1. Create a Realistic Budget
Post-settlement, assess your monthly income and expenditures. Prioritize essential costs and set aside savings to avoid future debts. A balanced budget acts as your financial roadmap.
2. Build an Emergency Fund
Set aside a portion of your income each month for emergencies. Aim for at least three to six months' worth of living expenses in this fund, providing a safety net against unforeseen events.
3. Monitor and Improve Credit Score
Regularly check your credit report and work on improving your credit score by paying bills on time, reducing outstanding debts, and avoiding new debt where possible.
4. Seek Financial Counseling
Consider consulting a financial advisor to help you plan investment strategies or manage your resources more effectively. Professional guidance can offer new perspectives and strategies tailored to your situation.
5. Educate Yourself Financially
Stay informed about financial products, investment opportunities, and personal finance strategies. Education is a powerful tool for making informed financial decisions.
By implementing these tips, you'll be better positioned to maintain financial stability and avoid falling back into debt traps.
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages





Client Reviews
"AMA Legal Solutions provided strategic and practical advice, leading to a successful loan negotiation. I'm grateful for their support and expertise."
Sunita Rao
"I highly recommend AMA Legal Solutions. They effectively negotiated with my bank, resulting in a favorable settlement that relieved my financial stress."
Ravi Shankar
"AMA Legal Solutions transformed my loan settlement experience. Their expert guidance and knowledge of banking laws were invaluable."
Anjali Mehta
"Outstanding service from AMA Legal Solutions! Their deep understanding of RBI guidelines ensured my rights were protected throughout the loan settlement."
Vikram Joshi
"The team at AMA Legal Solutions demonstrated exceptional expertise and professionalism, helping me navigate the complex loan settlement process with ease."
Priya Kapoor
Frequently Asked Questions
Related Articles

RuPay Credit Card on UPI Default & Credit Line on UPI Settlement (2026)
Micro-transactions on RuPay UPI Credit Cards and pre-approved 'Credit Lines on UPI' have triggered a massive wave of 42%+ APR revolving debt traps. Find out if defaulting blocks your personal savings UPI and how to settle RuPay UPI credit dues for 30%–50%.
Read Article
Paytm, PhonePe & BharatPe Daily EDI Merchant Loan Settlement (2026)
Drowning in Equated Daily Installment (EDI) merchant loans where 100% of your daily QR Soundbox collections are auto-swept before you can pay suppliers or rent? Learn how retail shopkeepers and MSMEs legally halt QR sweeps and negotiate a 50%+ OTS.
Read Article
Can Bank or Loan App Remotely Lock Phone for EMI Default? RBI Rules (2026)
An investigative breakdown of RBI's Remote Device Locking Directions—explaining why lenders cannot lock your phone for personal loans, the mandatory 30/60 DPD safeguards on financed devices, the Rs. 250/hour delay penalty, and how to settle device & app loans.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611