How to Control Calls from Recovery Agents for Loan Recovery
Practical Steps to Manage and Mitigate Recovery Agent Calls

Anuj Anand Malik
Reviewed by AMA Legal Solutions
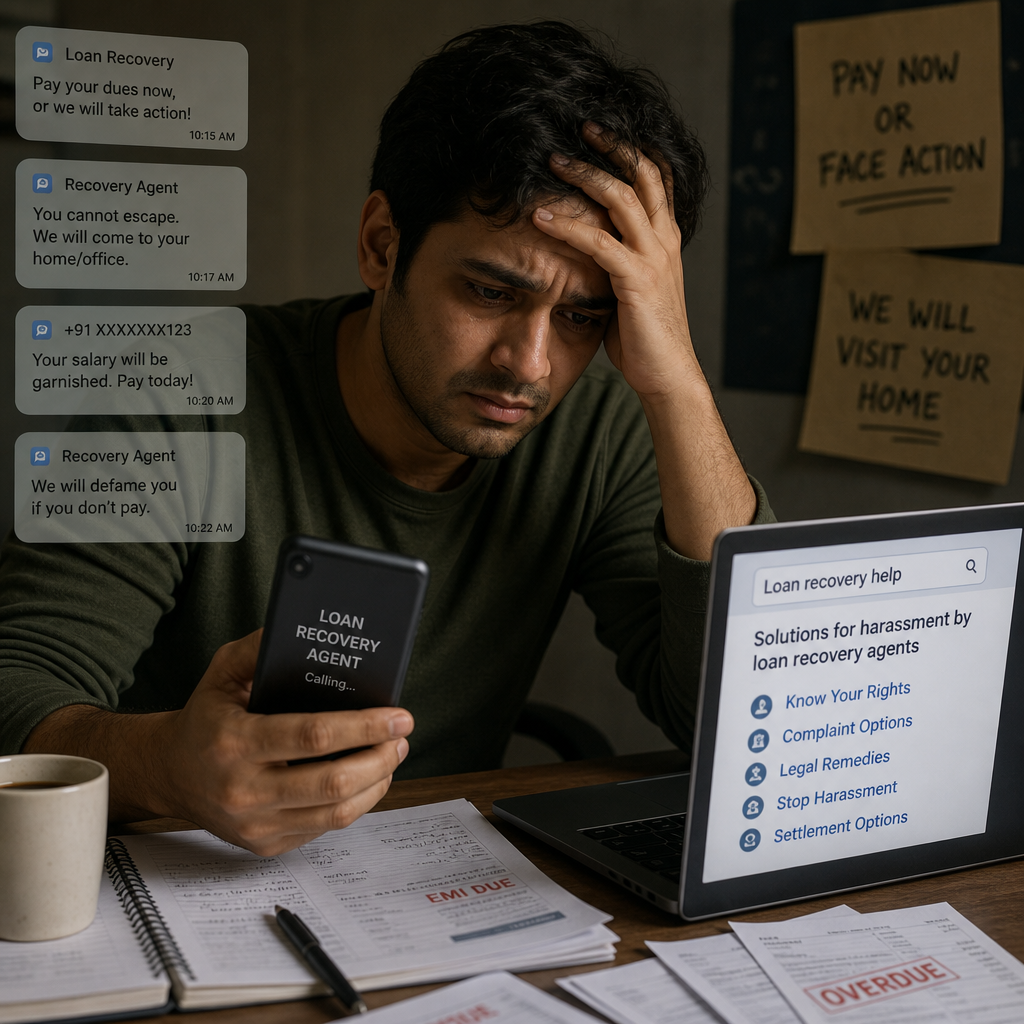
Introduction to Managing Recovery Agent Calls
Dealing with recovery agent calls for loan recovery can be a stressful experience, but understanding your rights and the correct approach can significantly alleviate your concerns. Indian laws, including the RBI guidelines, protect borrowers by regulating how recovery agents can operate. Knowing these regulations is crucial when you receive a call. For example, recovery agents cannot call you before 7 AM or after 7 PM, nor can they use abusive language or threats. If you’re facing financial difficulty, communication is key. Clearly explain your situation and offer a realistic payment plan, if possible.
Every call should be handled calmly and professionally. It's advisable to request details in writing, ensuring that any verbal communication is documented. This helps avoid misunderstandings and provides evidence if disputes arise. It's also important to stay informed about the status of your loan and any legal notices you might receive. Contacting a legal expert can provide further assurance and guidance tailored to your situation. Remember, recovery agents are performing their duty, but they must comply with legal standards. By staying informed and prepared, you can manage these calls effectively and protect your rights as a borrower.
Understanding the Legal Framework for Recovery Agents
In India, the activities of recovery agents are governed by several legal frameworks designed to protect borrowers. The Reserve Bank of India (RBI) lays down specific guidelines that banks and their recovery agents must follow. These guidelines emphasize ethical practices and prohibit harassment, threatening behavior, or use of force.
According to RBI directives, recovery agents must display proper identification and act with dignity and respect. They are required to inform the borrower about their appointment by the bank and the purpose of their visit. Calling hours by recovery agents are typically restricted to 7 a.m. to 7 p.m.
Key Legal Provisions
- Recovery agents must adhere to RBI guidelines and the Indian Penal Code (IPC) provisions regarding harassment and threats.
- Agents cannot engage in intimidation or use abusive language.
- Borrowers have the right to lodge a complaint with the bank and escalate it to the RBI if necessary.
Understanding these rights helps borrowers manage interactions with recovery agents effectively. Legal intervention can be sought if these guidelines are violated, providing a crucial layer of protection against unethical recovery practices. Borrowers should be proactive in documenting any misconduct to strengthen their case in the event of a legal challenge.
Your Rights as a Borrower Against Recovery Agents
As a borrower in India, you are protected by various rights when dealing with recovery agents. The Reserve Bank of India (RBI) has established guidelines to ensure fair practices. Understanding these rights can help you manage interactions effectively.
Right to Fair Treatment
Recovery agents must treat you with respect and dignity. They are prohibited from using abusive language or harassment tactics. If you experience such behavior, document the incidents and report them to your bank.
Right to Privacy
Agents should only contact you during prescribed hours, typically between 8 a.m. and 7 p.m. They cannot disclose your debt details to third parties without your consent, protecting your personal and financial privacy.
Right to Information
You are entitled to receive accurate information about your loan account, including the outstanding balance and details of interest and fees. Request these details in writing to ensure clarity and transparency.
Right to Dispute Resolution
If you disagree with the recovery process, you can raise a dispute with your bank's grievance redressal officer. Ensure you submit your complaint in writing and keep copies for reference.
By knowing your rights, you can better navigate interactions with recovery agents and protect yourself from unfair practices.
What Recovery Agents Can and Cannot Do Legally
Recovery agents play a pivotal role in the loan recovery process, but there are strict legal boundaries they must adhere to. Understanding these can help borrowers protect their rights.
What Recovery Agents Can Do
- Contact borrowers during reasonable hours, typically between 7 AM and 7 PM.
- Communicate the outstanding debt and repayment options clearly and professionally.
- Visit borrowers at their residence or workplace, but only with prior consent.
- Offer settlements or negotiate on behalf of the bank, subject to approval.
- Provide valid identification and authorization documents from the lender.
What Recovery Agents Cannot Do
- Use abusive or threatening language in any form of communication.
- Harass borrowers or their family members through repeated calls or visits.
- Misrepresent the consequences of non-payment or threaten illegal actions.
- Confiscate property or assets without due legal process under the SARFAESI Act.
- Disclose debt information to unauthorized persons, violating borrower privacy.
It's crucial for borrowers to be aware of these legal boundaries to effectively manage interactions with recovery agents. In case of any misconduct, borrowers can file a complaint with the banking ombudsman or consumer court.
Effective Communication Strategies with Recovery Agents
Communicating with recovery agents can be challenging, but strategic engagement can mitigate stress and protect your rights. Here's how:
1. Stay Calm and Composed
Engage with recovery agents with a calm demeanor. Emotional responses can escalate conflicts. Instead, listen attentively and acknowledge their concerns.
2. Set Clear Boundaries
Politely inform agents when and how you prefer to be contacted. For instance, request written communication through email, which provides a documented trail.
3. Gather Information
- Agent's Name and Contact Details: Always document who you're speaking with.
- Loan Details: Confirm the outstanding amount and any penalties before discussions.
4. Negotiate Wisely
Discuss feasible repayment plans based on your financial situation. Offer a realistic timeline and stay consistent with your proposals.
5. Know Your Rights
According to RBI guidelines, agents must respect borrower privacy and cannot harass. Familiarize yourself with these rights to identify any overreach.
6. Use Sample Responses
Have a few prepared responses for common questions. For example:
Recovery Agent: "Why is the payment delayed?"
Borrower: "I've been facing financial challenges due to medical expenses. I'm committed to resolving this and request some flexibility in repayment."
By employing these strategies, you can handle recovery calls with confidence, ensuring respectful and productive dialogue.
When to Insist on Written Communication
Insisting on written communication with recovery agents is crucial when you need a clear record of all interactions. It is advisable to request written communication if:
- Verification of Debt: You require a formal acknowledgment of the outstanding loan amount or details related to any discrepancies.
- Clarification of Terms: When negotiating settlement terms or repayment plans, having documented agreements ensures clarity and prevents misunderstandings.
- Protective Measure: In instances where communication has become aggressive or threatening, written communication serves as evidence and maintains a professional tone.
- Legal Documentation: If you anticipate any legal proceedings, such as arbitration or court cases, written records provide a solid foundation for your defense or negotiation strategy.
To transition to written communication, inform the agent during a call that you prefer future interactions to be via email or official letters. Follow up with an email requesting all future correspondences to be sent in writing. This method helps in maintaining your rights under the Reserve Bank of India (RBI) guidelines and provides a verifiable trail should you need to escalate the matter to a legal advisor.
Always retain copies of all written communications, and respond promptly to maintain a constructive dialogue.

Halt Recovery Agent Harassment Legally
How to File a Complaint Against Harassment
Facing harassment from recovery agents is distressing, but you have legal recourse. Here’s a step-by-step guide to filing a complaint:
1. Document Everything
Keep a record of all calls, messages, and interactions. Note the date, time, caller details, and nature of the communication. This documentation is crucial in supporting your complaint.
2. Contact the Bank
Before escalating, inform your bank about the harassment. Banks are responsible for the actions of their recovery agents. Request them to intervene and instruct their agents to cease inappropriate behavior.
3. Write a Formal Complaint
Draft a formal complaint letter to the bank and the recovery agency. Clearly specify the incidents of harassment, attaching your documented evidence. Request a resolution timeline.
4. Approach the Banking Ombudsman
If the bank does not address your complaint within 30 days, escalate the issue to the Banking Ombudsman. Fill the online complaint form, attaching your complaint copy and evidence.
5. File a Police Report
If harassment persists, consider filing a police report. Harassment is a criminal offense under Indian law, and law enforcement can take action against aggressive recovery practices.
Remember, you have the right to dignity and respectful treatment. Never hesitate to use these legal avenues to protect yourself from harassment.
Negotiating Settlements: Practical Tips
When faced with persistent calls from recovery agents, negotiating a settlement can be a strategic way to control the situation and manage your loan recovery process effectively. Here's how to approach it:
Understand Your Position
Before entering negotiations, review your financial status. Know how much you owe, your current income, and what you can realistically offer. This preparation provides a clear starting point for negotiations.
Communicate Professionally
- Always remain calm and professional, even if pressured. This demeanor will show agents you are serious about resolving the matter.
- Request all communication to be made via email for a documented record, reducing miscommunication risks.
Offer a Reasonable Proposal
Provide a settlement amount that is feasible for you but also attractive to the lender. Offering a lump-sum payment can often lead to a more favorable settlement.
Negotiate Terms
- Be clear about your terms. If you require more time, articulate this and propose a realistic timeline.
- Ask for a written agreement outlining the new terms once negotiations conclude.
Seek Legal Advice
If negotiations stall or you feel pressured, consult a legal expert who specializes in banking law. They can guide you on your rights and help safeguard your interests.
Employing these practical tips can help you regain control of the negotiation process and reduce the stress associated with recovery agent calls.
Common Mistakes Borrowers Make with Recovery Agents
When dealing with recovery agents, borrowers often make errors that can complicate their situation. Understanding these mistakes can help in managing interactions more effectively.
Engaging in Heated Arguments
Borrowers sometimes get into heated exchanges with recovery agents. Such arguments can escalate tensions and may lead to intimidation tactics. Keeping calm is crucial; instead, communicate your situation clearly and professionally.
Sharing Excessive Personal Information
Providing unnecessary personal details to recovery agents can be risky. It is advisable to only share information that is relevant to your loan settlement discussions. Always prioritize your privacy and security.
Ignoring Calls and Notices
Some borrowers choose to ignore calls and legal notices from recovery agents, hoping the problem will disappear. This approach can lead to legal actions such as court summons, which can further complicate matters.
Not Documenting Conversations
Failing to keep a record of communications can be detrimental. Always document conversations, including dates, times, and content of discussions, to ensure you have a clear trail of interactions.
Agreeing to Unreasonable Terms
In a rush to settle, borrowers might agree to unfavorable terms. Evaluate terms thoroughly and consult a legal advisor if necessary to avoid commitments that could be financially disadvantageous.
What Banks Don't Tell You About Recovery Timelines
Understanding recovery timelines is crucial for borrowers facing loan defaults. Banks operate under specific internal protocols, which they often do not disclose fully. Typically, after a loan is classified as a Non-Performing Asset (NPA), banks initiate recovery processes, but the timeline can vary significantly based on the type of loan and borrower profile.
Timeline Stages:
- Initial Notices: Expect to receive multiple notices within the first 90 days after a missed payment. These are designed to prompt quick repayment.
- Classification as NPA: If payment delays persist beyond 90 days, the account may be classified as an NPA, leading to intensified recovery actions.
- Engagement of Recovery Agents: Following NPA classification, banks may engage recovery agents, often within 120 days.
- Legal Actions: Legal proceedings such as those under the SARFAESI Act can commence after 180 days. However, banks usually exhaust all recovery avenues before pursuing court intervention.
Borrowers can influence these timelines by actively communicating with banks and exploring restructuring or settlement options. Banks might not openly discuss that early and transparent communication can delay or alter recovery timelines, offering borrowers potential relief and additional time to stabilize their financial situation.
Remember, each situation is unique, and proactive engagement with your bank can significantly impact the recovery process.
Recovery Agent Strategies: How to Respond
When dealing with recovery agents, your approach can significantly affect the outcome. Here’s how to handle calls effectively:
Stay Calm and Composed
Recovery agents may use pressure tactics to provoke a reaction. Remain calm. Take deep breaths before responding. Showing composure indicates confidence and control.
Understand Your Rights
Familiarize yourself with RBI guidelines that protect borrowers. Recovery agents cannot harass or threaten you. If they do, inform them that you are aware of your rights and are documenting the interaction.
Request Written Communication
Politely ask the recovery agent to send any repayment proposals via official email or post. This creates a documented trail and prevents miscommunication.
Provide Relevant Information
If asked about your financial situation, be honest but concise. Avoid oversharing personal details that aren't directly related to your repayment capacity.
Negotiate Wisely
When discussing repayment options, consider your financial capacity. Request a settlement that is realistic for you. Mention any previous payments or hardships as leverage.
End Calls Politely
If the conversation becomes aggressive, calmly end the call by stating, “I’ll communicate further through written correspondence.” Always maintain respect even in challenging interactions.
- Stay calm; avoid reacting under pressure.
- Understand and assert your rights under RBI guidelines.
- Request all proposals in writing for documentation.
- Share only relevant financial details.
- Negotiate based on your financial capabilities.
- End aggressive calls politely and suggest further written communication.
Understanding RBI Guidelines on Loan Recovery Processes
The Reserve Bank of India (RBI) has set comprehensive guidelines to regulate the loan recovery processes undertaken by banks and financial institutions. These guidelines ensure that borrowers are treated fairly and their rights are protected during the recovery proceedings.
Key RBI Directives
- Code of Conduct: Recovery agents must follow a code of conduct, ensuring polite communication without harassment or intimidation.
- Agent Training: Banks are mandated to appoint only trained recovery agents familiar with RBI guidelines and ethical collection practices.
- Time Restrictions: Recovery calls must be made between 7 AM and 7 PM to respect the borrower's personal time and privacy.
- Official Communication: Banks should provide borrowers with prior written notice before involving recovery agents, detailing the overdue amount and recovery process.
- Dispute Resolution: Banks must have a grievance redressal mechanism for borrowers to address any misbehavior or harassment by recovery agents.
Understanding these RBI guidelines is crucial for borrowers to protect themselves from any unlawful practices. If these rules are violated, borrowers have the right to report such instances to the ombudsman or directly to the bank's grievance cell. Staying informed empowers borrowers to handle recovery processes more effectively, ensuring their rights are upheld.
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages





Client Reviews
"I was very impressed with the thoroughness and expertise of AMA Legal Solutions. They handled my case with great care and effectively managed interactions with recovery agents."
Kavita Rao
"AMA Legal Solutions helped me manage recovery agent calls with ease and professionalism. Their expert advice and guidance were invaluable in protecting my rights."
Ramesh Iyer
"The legal team at AMA Legal Solutions provided fantastic support during a stressful time. They helped me understand my rights and negotiate a fair repayment plan."
Priya Sharma
"AMA Legal Solutions’ knowledge of banking law and recovery agent guidelines was exceptional. They provided clear and actionable advice that helped me navigate difficult situations."
Arjun Patel
"I highly recommend AMA Legal Solutions for anyone dealing with loan recovery issues. Their professional approach and compassionate service made the process much more manageable."
Meena Gupta
Frequently Asked Questions
Related Articles

RuPay Credit Card on UPI Default & Credit Line on UPI Settlement (2026)
Micro-transactions on RuPay UPI Credit Cards and pre-approved 'Credit Lines on UPI' have triggered a massive wave of 42%+ APR revolving debt traps. Find out if defaulting blocks your personal savings UPI and how to settle RuPay UPI credit dues for 30%–50%.
Read Article
Paytm, PhonePe & BharatPe Daily EDI Merchant Loan Settlement (2026)
Drowning in Equated Daily Installment (EDI) merchant loans where 100% of your daily QR Soundbox collections are auto-swept before you can pay suppliers or rent? Learn how retail shopkeepers and MSMEs legally halt QR sweeps and negotiate a 50%+ OTS.
Read Article
Can Bank or Loan App Remotely Lock Phone for EMI Default? RBI Rules (2026)
An investigative breakdown of RBI's Remote Device Locking Directions—explaining why lenders cannot lock your phone for personal loans, the mandatory 30/60 DPD safeguards on financed devices, the Rs. 250/hour delay penalty, and how to settle device & app loans.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611