Can You Get Another Credit Card After Settlement? Understanding Your Options in 2026
Explore your eligibility for a new credit card post-settlement and essential legal insights.
Anuj Anand Malik
Reviewed by AMA Legal Solutions
Key Takeaways: After settling a credit card debt in India, obtaining a new credit card is possible but challenging. The 'settled' status on your credit report may affect your creditworthiness for up to seven years, which could result in higher interest rates or loan rejections. Understanding regulatory norms and improving your financial profile through responsible credit behavior is essential for securing a new credit card post-settlement.
Introduction to Can You Get Another Credit Card After Settlement? in India
Navigating the complexities of credit card settlements can be daunting, especially when contemplating future credit options. A common question that arises is: can you get another credit card after settlement? Understanding the implications of settling debt and its impact on your financial prospects is crucial. In 2026, with constantly evolving financial landscapes in India, borrowers must be informed about their options and the legal frameworks governing credit post-settlement. This comprehensive guide unravels the various aspects that influence your ability to acquire a new credit card after settling previous debts.Statutory Framework & Governing Legal Provisions
In India, the borrowing and lending processes are primarily governed by the Reserve Bank of India (RBI) and encompass credit reporting norms that all financial institutions must adhere to. According to the RBI, post-settlement, your credit account status gets updated to "settled," affecting how lenders view future credit applications. This status remains on your credit report for up to seven years, affecting your creditworthiness significantly. No statutory provision explicitly prevents someone from acquiring a new credit card after settlement; however, the reality is more nuanced. Understanding how these regulatory norms work is fundamental when seeking new credit.Comprehensive Analysis & Practical Evaluation of Credit Card Eligibility After Settlement
When evaluating whether you can get another credit card after settlement, several factors come into play. Post-settlement, lenders scrutinize your credit report more stringently. The presence of a "settled" tag serves as a red flag, indicating that you did not fulfill the entire obligation. This often results in credit applications being subject to more stringent terms, higher interest rates, or outright rejection. Rebuilding your financial credibility is essential, requiring a strategic approach such as timely payments on existing loans, maintaining a low credit utilization ratio, and gradually re-establishing trust with lenders.Comparative Parameters / Procedural Workflow Matrix for Credit Applications
| Parameter / Option | Legal Basis & Requirements | Key Procedures / Considerations | Strategic Advantage with Counsel |
|---|---|---|---|
| Secured Credit Card | Requires a fixed deposit as collateral | Application linked to existing deposit, eligible for individuals with low scores | Guidance on securing optimal terms and conditions |
| Credit-Builder Loan | Offered by both banks and NBFCs | Regular payments enhance credit profile | Assistance in selecting the best lender |
| Standard Credit Card | Requires improved CIBIL score post-settlement | Higher scrutiny of credit report, potential higher rates | Strategic counsel in negotiating terms |
| NBFC Loan Product | Less stringent credit requirements | Higher interest rates and stricter conditions | Expert advice on navigating NBFC options |
Key Insights & Data Infographic
Visual summary, statistical trends & procedural breakdown
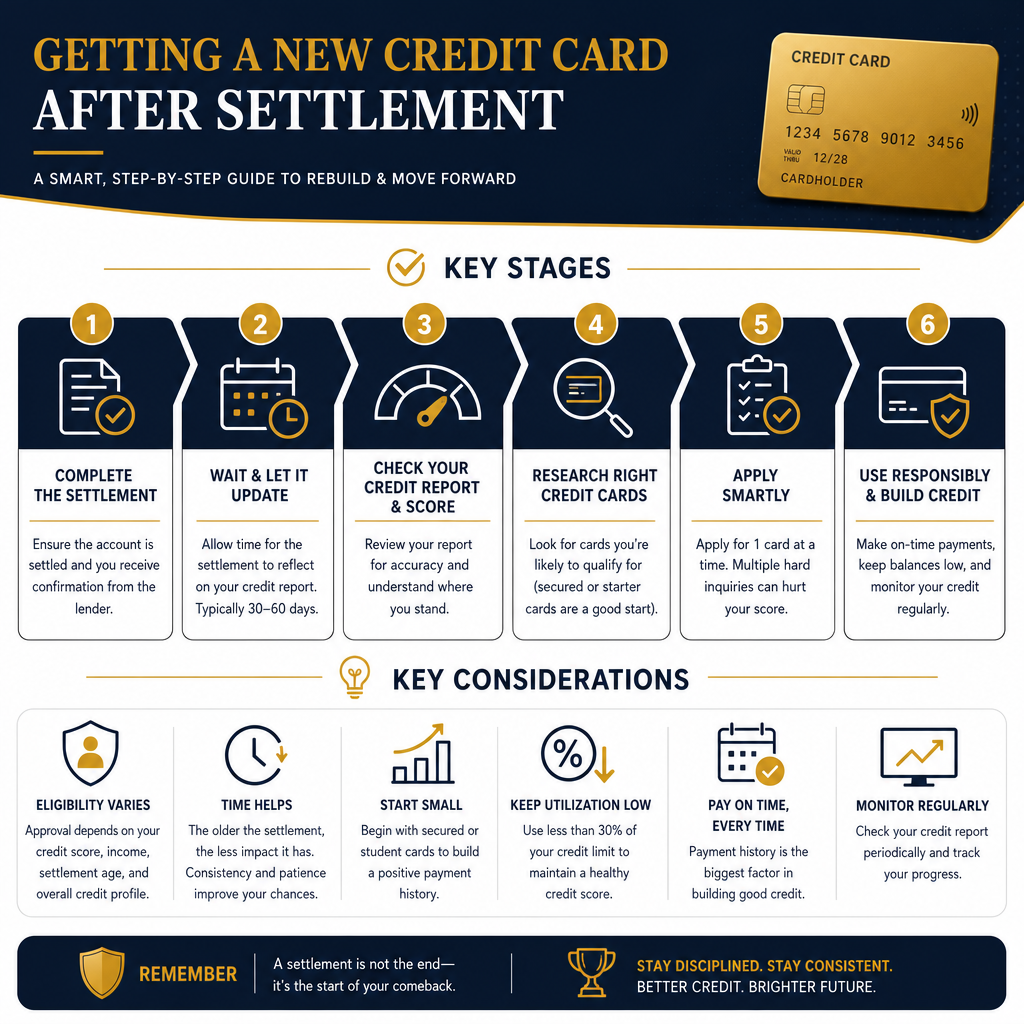
Prepared by AMA Legal Solutions Research & Analytics Team • Data & Compliance Overview

Bank Compromise Settlement & Debt Relief
Legal Safeguards, Consumer Rights, and Critical Risks to Avoid
Understanding one's rights post-settlement is crucial for navigating the credit landscape. Credit institutions are mandated to ensure accurate credit reporting. Acquiring a No Dues Certificate post-settlement can safeguard you against erroneous claims. If discrepancies in your credit report arise, you have the right to dispute inaccuracies directly with credit bureaus, which must investigate and correct errors within a 30-day investigative window. Being proactive in credit management post-settlement by maintaining payment discipline can significantly influence your future credit standing.Impact of Settlement on Credit Score and Future Borrowing
Can you get another credit card after settlement when your credit score has taken a hit? The answer lies in understanding the extent of the impact. Typically, post-settlement, the CIBIL score can drop significantly, often between 75 to 150 points. This drop makes potential lenders wary, viewing your credit behavior as high-risk. However, sustained efforts to improve financial discipline can gradually restore your credit score. Regularly monitoring your credit report and engaging in responsible credit activities, such as timely payments or using secured credit cards, can facilitate credit rehabilitation.Criteria for Approval of New Credit Applications Post-Settlement
The criteria for credit approval post-settlement involve evaluating the changed parameters of your creditworthiness. When can you get another credit card after settlement? If you demonstrate improved financial discipline, have a clear repayment history post-settlement, and maintain a low credit utilization ratio, these factors could work in your favor. Engaging directly with potential lenders to understand their requirements and addressing any concerns regarding previous settlements further enhances your application prospects.Strategic Conclusion: Securing Legal Assurance with AMA Legal Solutions
If you're pondering, "Can you get another credit card after settlement?" remember that the path to restoring creditworthiness is nuanced and strategic. Consulting with experts like those at AMA Legal Solutions can help navigate the post-settlement phase effectively. Their experience in providing tailored advice and representation ensures that your credit rehabilitation journey is backed by solid legal grounds. By keeping abreast with necessary legal guardianship, you can not only enhance your financial outlook but also foster robust lender relationships, ultimately securing the credit facilities you need and deserve. Prioritizing expert counsel will not only safeguard your financial interests but also place you on a steadfast path towards financial inclusion and stability. This approach not just aids in addressing the specific legal concerns related to credit settlements but also aligns you with broader financial goals.Popular Searches & Topics
Commonly searched legal queries and keywords related to this article
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.
AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages
Frequently Asked Questions
Related Articles
How to Not Trust Loan Settlement Agencies for Loan Settlement but a Law Firm
Discover reliable alternatives to loan settlement agencies with legal expertise for effective resolutions.
Read Article
Recovery agent behaviour and legal limits in India (2026)
Understanding the legal framework for recovery agents and their conduct
Read Article
Complaints against abusive recovery practices in India (2026)
Explore your rights and options for addressing abusive recovery practices effectively.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611