Why Banks Offer Loan Settlements: Hidden Downsides Explored
Discover if loan settlements are beneficial or if there are concealed pitfalls.

Anuj Anand Malik
Reviewed by AMA Legal Solutions
Introduction to Primary Keyword
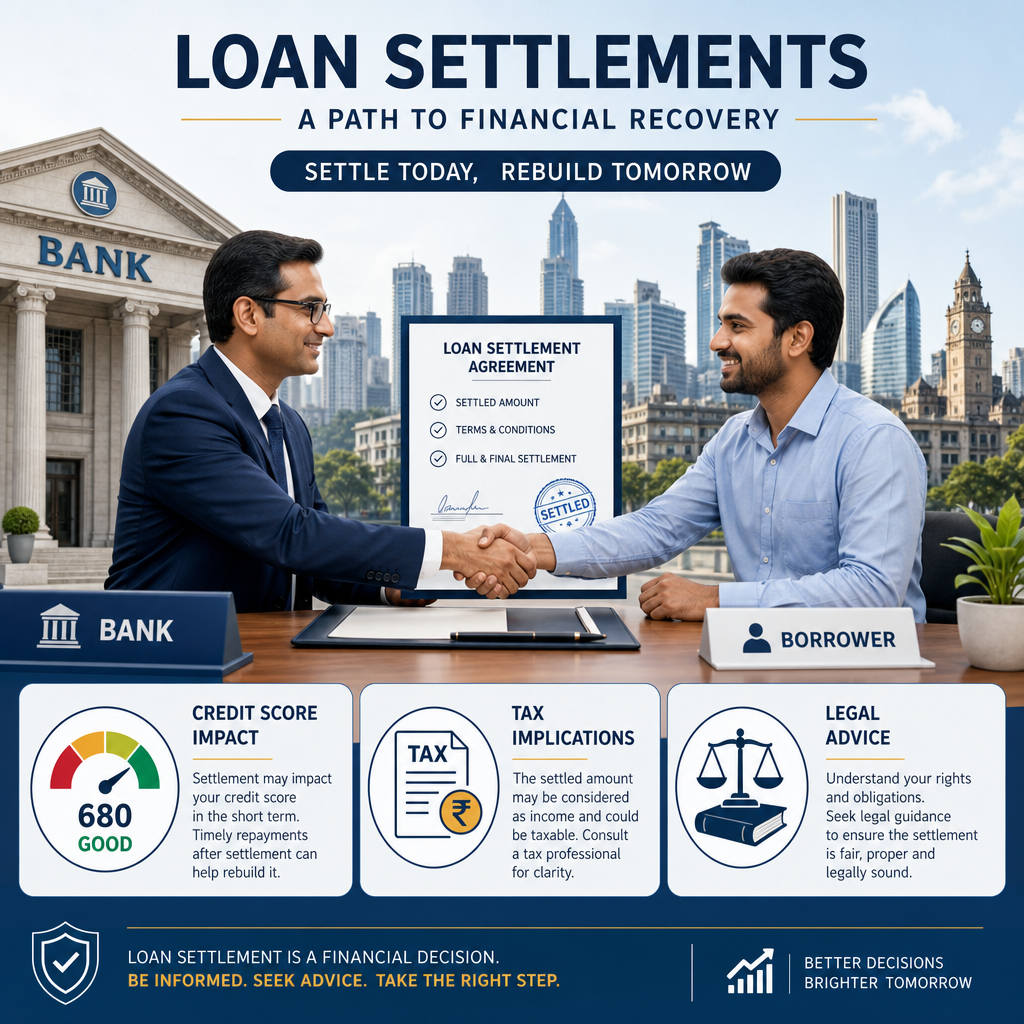
In the intricate world of banking and finance, loan settlements have become a prevalent practice for both financial institutions and borrowers. But why do banks offer these settlements, and more importantly, are there any hidden downsides that borrowers should be aware of before accepting one? Understanding the rationale and implications of loan settlements is crucial for individuals who find themselves navigating through financial challenges. This segment delves into the motivations behind banks offering loan settlements and the potential pitfalls that may accompany them.
Banks and financial institutions, such as those operating under the guidelines of the Reserve Bank of India (RBI), often offer loan settlements to mitigate losses arising from non-performing assets. When borrowers default on their loans, it affects the bank's balance sheet adversely. By offering a settlement, banks aim to recover a portion of the outstanding amount quickly, thereby improving their financial standing. This pragmatic approach allows banks to keep their operations smooth and maintain liquidity. Detailed insights into such banking strategies can be explored through the Banking and Finance services provided by AMA Legal Solutions.
For borrowers, accepting a loan settlement might seem like a viable option to alleviate financial strain. However, it is imperative to recognize the hidden downsides that could potentially affect one's financial future. Settlements can adversely impact credit scores, making it difficult to secure loans in the future. This could be a critical consideration for those planning to invest in real estate or engage in corporate ventures. AMA Legal Solutions offers thorough guidance through their Loan Settlement services, assisting clients to make informed decisions.
Moreover, loan settlements can sometimes come with tax implications that borrowers may not anticipate initially. The forgiven amount might be considered as taxable income, adding another layer of financial responsibility. It is advisable to seek professional advice to navigate these complexities effectively. AMA Legal Solutions, with expertise in tax regulations, can provide the necessary insights to manage these aspects efficiently.
Additionally, borrowers should be wary of the terms and conditions laid down in the settlement agreement. Misunderstanding or overlooking specific clauses can lead to legal complications in the future. Engaging in professional legal drafting and litigation services can ensure that borrowers are well-protected and aware of their rights and obligations.
In conclusion, while loan settlements may offer immediate relief to borrowers facing financial difficulties, they come with strings attached. A comprehensive understanding of both the advantages and potential downsides is essential. With the support of experienced legal professionals like those at AMA Legal Solutions, individuals can navigate this complex process with greater confidence and clarity.
Understanding Loan Settlements: A Brief Overview
Loan settlements can be a viable option for borrowers who find themselves in dire financial straits and are unable to meet their debt obligations. Banks in India, including both public and private sector institutions, might offer loan settlements as a way to recover a portion of the loan amount rather than face a complete default. This is particularly pertinent in situations where the borrower is significantly delinquent, and the prospects of full recovery appear bleak.
Loan settlement is essentially an agreement between the lender and the borrower, where the lender consents to accept a sum less than the owed amount as full and final payment. This arrangement could significantly ease the financial burden on the borrower as it allows for a reduction in the outstanding debt. However, the offer is primarily beneficial for the bank since it enables them to recover a part of the loan without undergoing lengthy legal procedures or the sale of collateral assets. You can learn more about these banking and finance solutions on our Banking and Finance Services page.
Despite the potential advantages, borrowers should be aware of potential downsides associated with loan settlements. A critical factor to consider is the impact on the borrower’s credit score. Settlements are flagged in credit reports and can adversely affect the borrower's creditworthiness, leading to difficulties in securing future loans. Moreover, accepting a loan settlement may result in a situation where the borrower is seen as a higher-risk individual by other financial institutions, potentially leading to higher interest rates or stricter terms on future borrowing. If you are navigating the complexities of loan settlement and need professional guidance, our Loan Settlement Services offer expert advice tailored to your situation.
Additionally, there may be tax implications for the forgiven debt amount, as it might be treated as income by the tax authorities, thereby increasing the borrower’s tax liability. It's vital to fully understand these implications before proceeding with a settlement. For in-depth analysis and advice on such fiscal matters, our Corporate Services can provide comprehensive support.
Before accepting a loan settlement, it is prudent for borrowers to seek professional legal advice to ensure they are making an informed decision. Our Arbitration Services and Litigation Services are available to help navigate the legal nuances and implications of loan settlements. Understanding the full scope of both the benefits and potential drawbacks is crucial in such financial decisions.
Why Banks Offer Loan Settlements: Key Motivations
Banks have several key motivations for offering loan settlements, a practice that involves negotiating a reduced payoff amount with borrowers who are struggling to meet their financial obligations. Understanding these motivations is crucial for borrowers considering this option, as it can provide insight into the bank's perspective and the underlying factors that influence such decisions.
One primary reason banks offer loan settlements is to mitigate losses. When a borrower defaults, the bank stands to lose not only the interest income but potentially a significant portion of the principal amount lent. By agreeing to a settlement, banks can recover at least a part of the outstanding loan amount, which is often more favorable than incurring a total loss. This financial strategy helps banks maintain healthier balance sheets and minimize the impact of non-performing assets.
Another critical factor is the cost of litigation. Pursuing legal action against defaulting borrowers can be both time-consuming and expensive, often requiring resources that could be allocated elsewhere. Loan settlements provide a more cost-effective solution by allowing banks to bypass the lengthy litigation process. For borrowers seeking legal advice during such negotiations, services like litigation services from AMA Legal Solutions can offer invaluable guidance.
Regulatory compliance also plays a role in banks’ decisions to offer settlements. Banks in India must comply with stringent guidelines set by the Reserve Bank of India (RBI) regarding non-performing assets. Offering settlements can help banks manage their portfolios in line with these regulatory requirements, ensuring that their financial practices remain compliant. For those navigating the complexities of banking regulations, banking and finance services at AMA Legal Solutions can provide expert assistance.
Maintaining customer relationships is another significant motivation. Banks often prefer to retain a positive relationship with their clients, even in challenging financial circumstances. By offering settlements, banks show a willingness to work with borrowers, which can preserve goodwill and potentially lead to future business. Borrowers can benefit from professional negotiation support by exploring loan settlement services offered by AMA Legal Solutions to ensure a fair outcome.
In conclusion, while loan settlements are beneficial for banks in managing risks and maintaining regulatory compliance, it is essential for borrowers to consider the terms carefully. Understanding the bank's motivations can aid in making informed decisions, and consulting with legal experts through services such as drafting and arbitration can provide further clarity and support.
The Legal Framework Surrounding Loan Settlements
The legal framework governing loan settlements in India is comprehensive, aiming to balance the rights and obligations of both lenders and borrowers. The provisions under the Reserve Bank of India (RBI) guidelines play a pivotal role in shaping these transactions. The RBI mandates that all banks adhere to fair practice codes, ensuring transparency and fairness in loan settlements. This regulation is designed to protect borrowers from coercive recovery practices while allowing banks to resolve bad debts efficiently.
Loan settlements typically involve negotiations between the borrower and the bank to agree on a reduced payoff amount. It is crucial for borrowers to understand the legal implications, as accepting a settlement could impact their credit score adversely. The settlement, once accepted, is reported to credit bureaus, reflecting that the full debt was not paid as originally agreed. Borrowers should consult with legal experts to understand these nuances fully. AMA Legal Solutions offers comprehensive services to guide borrowers through the loan settlement process, ensuring all legal aspects are meticulously handled.
The Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act (SARFAESI Act) also plays a significant role in the legal framework of loan settlements. This Act empowers banks to auction properties to recover loans without court intervention. However, it requires banks to issue a notice and follow a specific procedure before taking possession of the property. Understanding the SARFAESI Act is essential for borrowers engaged in settlement negotiations. Professional legal advice, such as that provided by AMA Legal Solutions' banking and finance services, can be invaluable in navigating these complexities.
Another crucial element is the Insolvency and Bankruptcy Code (IBC), which provides a framework for resolving insolvencies in a time-bound manner. While primarily aimed at corporate borrowers, the implications for personal loans can sometimes intersect, particularly when individuals have significant business interests. The IBC outlines the process for asset liquidation and debt settlement, and its impact on personal loan settlements can be intricate. Consulting legal services specializing in corporate law and arbitration may provide deeper insights into these proceedings.
Understanding the legal framework is critical to avoid potential pitfalls associated with loan settlements. Borrowers should be cautious of any hidden clauses or conditions that may lead to future legal complications. Engaging with litigation services can help identify any drawbacks in the terms of settlement agreements. It is always advisable to have a legal expert review settlement offers to ensure they align with the borrower’s best interests and comply with current legislation.
Financial Implications for Borrowers
Loan settlements offered by banks can appear to be a financial reprieve for borrowers struggling with debt. However, it is essential to understand the financial implications before proceeding with such settlements. While banks may offer settlements as a way to recover part of the outstanding loan, borrowers should be aware of potential hidden downsides that can impact their financial standing.
One of the primary financial implications of accepting a loan settlement is the potential impact on the borrower's credit score. Loan settlements are typically recorded on credit reports as "settled" rather than "paid in full," which can negatively affect a borrower's creditworthiness. This derogatory mark can stay on a credit report for several years, making it challenging to secure future loans or credit at favorable interest rates. Borrowers may need to consult with experts in banking and finance to fully understand the long-term impact on their credit profile.
Another critical financial implication is the possibility of repayment of more than expected due to accrued interest and penalties. Before settling, borrowers should scrutinize the terms of the settlement agreement to ensure that they are not agreeing to pay more than they can afford. Legal advice from professionals experienced in loan settlements can clarify any ambiguous terms and help borrowers navigate the complexities involved.
Furthermore, borrowers should be aware of the tax implications associated with loan settlements. In some jurisdictions, the forgiven amount of a loan may be considered taxable income, which means that borrowers could face a significant tax liability. It is advisable for borrowers to seek guidance from financial advisors or tax professionals to understand these tax consequences fully.
Additionally, opting for a loan settlement might limit a borrower's ability to obtain financing for critical needs like real estate purchases or other major investments in the future. The perception of being a higher risk borrower can lead to higher interest rates or outright rejections, affecting long-term financial goals. Engaging with a corporate legal expert might provide insights into alternative financial strategies that can align better with the borrower's needs.
In summary, while loan settlements can offer immediate financial relief, they come with substantial financial implications that must be carefully considered. Borrowers are encouraged to seek comprehensive legal advice and consider alternatives that might offer a more balanced approach to debt resolution. For further assistance, consulting with professionals in arbitration or litigation can provide a more strategic pathway to resolving financial difficulties.
Potential Tax Consequences of Loan Settlements
When considering loan settlements, one often overlooked aspect is the potential tax consequences that may follow. In India, the amount of debt forgiven through a loan settlement could be considered as taxable income by the Income Tax Department. This means that you might be required to pay taxes on the forgiven portion of your loan, which can significantly affect your financial situation.
The concept here is fairly straightforward. If a bank agrees to settle your loan for less than the total outstanding amount, the difference is essentially a gain for you and could be treated as 'income from other sources' under Indian tax laws. This is particularly relevant if the waived amount is substantial, as it could push you into a higher tax bracket, leading to a larger tax liability. It is crucial to understand these implications to avoid any unexpected tax burdens.
It is advisable to consult with a financial advisor or a legal expert to analyze the complete tax implications before proceeding with a loan settlement. At AMA Legal Solutions, our experts in banking and finance law can provide comprehensive guidance on navigating these complex issues. Additionally, our loan settlement services are designed to help you make informed decisions that align with your financial goals.
Furthermore, while pursuing a loan settlement, the documentation must be evaluated meticulously to ensure that the settlement terms are correctly reflected and that all tax responsibilities are appropriately addressed. Legal services in drafting and litigation might be necessary to ensure that your rights are protected and your obligations are clear.
In conclusion, while a loan settlement might appear as a viable solution to reduce debt burdens, it is imperative to weigh the tax implications thoroughly. Engaging with skilled professionals who understand the nuances of Indian tax law can make a significant difference. Ensure you are equipped with the right information and expert advice before making such a crucial financial decision.

Halt Recovery Agent Harassment Legally
Impact on Credit Scores: What Borrowers Need to Know
When considering a loan settlement, understanding its impact on your credit score is of paramount importance. In India, your credit score is a crucial financial metric used by lenders to assess your creditworthiness. A loan settlement can have significant implications for your credit score, which may affect your ability to obtain credit in the future.
Loan settlement is often reported to credit bureaus as a "settled" account. This notation indicates that the lender accepted an amount less than what was originally due, and while this might be a short-term relief, it is viewed negatively by lenders. The Reserve Bank of India (RBI) guidelines require banks to report such settlements, which can remain on your credit report for up to seven years, potentially lowering your credit score significantly.
It's crucial to understand the long-term effect of a reduced credit score. A lower credit score can lead to higher interest rates on future borrowings, increased scrutiny from lenders, or even outright denial of credit applications. For instance, if you plan to invest in real estate or require a business loan, a healthy credit score is imperative. In such cases, seeking expert guidance from our banking and finance services can provide you with strategic advice on managing your financial health effectively.
Borrowers should also be wary of the potential legal repercussions of a loan settlement. Engaging with legal professionals, like those available through AMA Legal Solutions' loan settlement services, can help you navigate the complexities of settlement agreements and their implications. A settlement might resolve immediate financial distress but understanding the possible impact on your credit profile is essential.
Additionally, a loan settlement may limit your negotiating power in future financial transactions. If you hold intellectual property or real estate assets, ensuring these are not jeopardized by a diminished credit standing is necessary. Our intellectual property rights services and real estate services can help protect your assets while managing credit concerns.
Ultimately, while a loan settlement might seem like a beneficial short-term solution, the hidden downside often lies in its impact on your credit score. It is advisable to consult with legal experts to explore all possible options and mitigate risks. Our team at AMA Legal Solutions offers comprehensive legal support to help you make informed decisions and safeguard your financial future.
Hidden Fees and Costs: Unforeseen Financial Burdens
When banks offer loan settlements, the opportunity to resolve outstanding debts at a reduced amount can seem appealing. However, it's crucial to be aware of the hidden fees and costs that might accompany these settlements, which could lead to unforeseen financial burdens. These costs can significantly impact the overall benefit of accepting a loan settlement, turning what seems like a financial reprieve into an unexpected liability.
Firstly, many borrowers are not fully aware that a loan settlement can negatively affect their credit score. The Reserve Bank of India (RBI) mandates that settled loans be reported to credit bureaus, reflecting as “settled” rather than “paid in full.” This notation can lower your credit score and potentially increase the cost of future borrowings. The decline in creditworthiness can also affect your ability to secure competitive interest rates on loans, impacting your long-term financial planning. For guidance on managing these impacts, consider exploring our Banking and Finance services.
Additionally, borrowers may encounter unexpected fees associated with the settlement process. These can include administrative fees, penalty charges, or service fees that the bank imposes to facilitate the settlement. Such costs can reduce the financial relief expected from the settlement. It is essential to carefully review the settlement offer and seek professional advice if necessary to understand these hidden charges. Our team at AMA Legal Solutions can assist in examining the fine print and ensuring you are fully informed.
Moreover, the tax implications of a loan settlement are often overlooked. The amount forgiven by the bank is typically considered taxable income by tax authorities. This means you may have to pay taxes on the forgiven debt, further diminishing the financial benefit of the settlement. Understanding these tax repercussions is crucial in avoiding unpleasant surprises during tax season. Our Drafting and Litigation services can provide you with the necessary legal insights to navigate these complexities.
Finally, the psychological and financial pressure of handling these hidden costs can be overwhelming, especially if the settlement does not provide the anticipated financial relief. This is why it is advisable to consult with legal and financial experts before proceeding with a loan settlement. At AMA Legal Solutions, we offer comprehensive services across various domains, including Civil and Arbitration law, to help you make informed decisions that align with your financial goals.
Negotiating with Banks: Tips for Borrowers
When negotiating with banks for a loan settlement, it's essential to be well-prepared and informed to achieve the best possible outcome. Banks offer loan settlements primarily to reduce their non-performing assets and recover a portion of the lent amount. However, accepting a settlement can have hidden downsides, so it's crucial to approach the negotiation process thoughtfully. Here are some tips for borrowers to effectively negotiate with banks.
Firstly, understand your financial position thoroughly. Before entering negotiations, assess your current financial situation, including your income, expenses, and any other debts. Having a clear picture will help you determine a realistic settlement amount that you can afford. It's advisable to create a detailed budget plan that outlines your monthly commitments. This preparation will not only bolster your confidence but also demonstrate to the bank that you are serious about resolving the debt.
Next, gather all relevant documentation. Banks will require evidence of your financial circumstances, so be sure to have all necessary paperwork ready. This includes bank statements, payslips, and any communication you've had with the bank regarding your loan. Providing comprehensive documentation will support your case and facilitate a smoother negotiation process.
Consider seeking professional advice. Engaging with legal and financial experts, such as those at AMA Legal Solutions, can provide valuable insights and guidance. Their expertise in loan settlement negotiations can help you understand the potential legal implications and hidden downsides of a settlement. This professional assistance can be crucial in ensuring that your interests are protected during the negotiation process.
Furthermore, communicate clearly and respectfully with the bank. Approach negotiations with a cooperative and respectful attitude. Clearly articulate your situation and proposed settlement terms. Being transparent about your financial difficulties can foster goodwill and increase the likelihood of the bank considering your offer. Remember that banks are more inclined to negotiate with borrowers who demonstrate honesty and a genuine willingness to repay.
Finally, be aware of the potential consequences of a loan settlement, such as its impact on your credit score. Settlements might remain on your credit report for several years, affecting your ability to secure future credit. It's crucial to weigh these implications carefully before finalizing any agreement. For a comprehensive understanding of the legal aspects, you may explore litigation and drafting services offered by professionals in the field.
Alternatives to Loan Settlements: Exploring Other Options
While loan settlements might seem like an attractive option, there are several alternatives that borrowers can explore before reaching this stage. These options can preserve your credit score, offer more flexible terms, or even reduce the overall financial burden without some of the potential downsides associated with loan settlements. It is crucial to analyze these alternatives comprehensively, especially in the Indian financial context where regulations by the Reserve Bank of India (RBI) play a significant role.
1. Restructuring Your Loan
Loan restructuring involves revising the terms of your existing loan agreement, which might include extending the tenure or reducing the interest rate. This is a viable option for borrowers experiencing temporary financial difficulties. Engaging with a legal expert, such as those from AMA Legal Solutions’ Banking and Finance team, can provide guidance on negotiating terms that comply with RBI regulations. This ensures that both your interests and those of the lender are adequately protected.
2. Refinancing Your Loan
Refinancing allows you to replace your current loan with a new one, typically with more favorable terms. This can be an ideal alternative if your credit score has improved or if you find a lender offering better rates. It is essential to conduct a thorough cost-benefit analysis, often with the help of corporate financial advisors, to ascertain whether the savings from refinancing outweigh any associated fees.
3. Exploring Debt Consolidation
Debt consolidation involves merging multiple debts into a single loan with a lower interest rate. This option simplifies your payment schedule and can lead to reduced monthly obligations. It is particularly beneficial if you are juggling multiple high-interest debts. Seeking professional advice from litigation experts can help navigate potential legal challenges and ensure that the consolidation process adheres to all regulatory requirements.
4. Seeking Financial Counseling
Financial counseling can provide you with strategies to manage your debts effectively. Counselors can assist in creating a budget and exploring repayment plans that fit your financial situation. Connecting with a multidisciplinary legal team, such as AMA Legal Solutions, can offer a holistic approach by combining legal advice with financial strategies, ensuring that all aspects of your financial health are addressed.
Before deciding on any alternative, it is advisable to consult with legal professionals who can offer personalized advice based on your specific circumstances. By exploring these options, you may find a solution that is both financially viable and legally sound, safeguarding your interests in the long run.
Real-Life Case Studies: Lessons Learned
Loan settlements can seem like a financial lifeline for borrowers facing economic hardships. However, it's essential to dig deeper into real-life scenarios to understand the potential consequences. Below, we explore a few case studies that shed light on the complexities and challenges involved in loan settlements.
Case Study 1: Ms. Sharma's Unexpected Complications
Ms. Sharma, a small business owner in Mumbai, faced severe financial stress due to declining market conditions. She decided to settle her ₹15 lakh business loan for ₹9 lakh, believing it would alleviate her immediate financial burdens. While this settlement indeed reduced her debt, it had unforeseen repercussions. Her CIBIL score plummeted, leading to difficulties in securing future loans and credit facilities. This case underscores the importance of understanding how loan settlements can impact creditworthiness, affecting future financial endeavors. At AMA Legal Solutions' Banking and Finance division, experts advise on these implications to help clients make informed decisions.
Case Study 2: Mr. Rao's Long-term Financial Strategy
Mr. Rao, a salaried professional from Bengaluru, opted for a loan settlement to manage his ₹10 lakh personal loan, accepting a ₹7 lakh settlement. While initially beneficial, Mr. Rao faced challenges when he tried to invest in real estate. Financial institutions viewed his settlement negatively, complicating his attempts to obtain new loans. This highlights the importance of considering long-term financial goals before accepting a settlement offer. Consulting with experts, such as those at AMA Legal Solutions' Real Estate team, can provide crucial insights and alternatives.
Case Study 3: The Corporate Dilemma of ABC Enterprises
ABC Enterprises, a mid-sized company, accepted a loan settlement during a challenging economic period. The reduced liability helped in the short term but tarnished their reputation in the corporate world. This case illustrates how settlements can impact a company's market perception and future partnership opportunities. Companies should weigh these factors carefully, perhaps consulting with AMA Legal Solutions' Corporate advisory services, to evaluate the broader implications of loan settlements.
These case studies serve as a reminder of the nuanced nature of loan settlements. While they offer immediate relief, the hidden downsides, such as credit score impact and future borrowing difficulties, cannot be overlooked. It's crucial for borrowers to seek professional guidance, like that provided by AMA Legal Solutions, to navigate the complexities and make well-informed decisions.
Making an Informed Decision: Weighing the Pros and Cons
Before proceeding with a loan settlement offer from your bank, it is crucial to weigh the pros and cons carefully. Understanding both sides of the spectrum will empower you to make a decision that aligns best with your financial goals and long-term credit health.
Advantages of Loan Settlement
One of the primary benefits of accepting a loan settlement is the immediate financial relief it provides. By settling a debt for less than what you owe, you can alleviate the burden of high monthly payments, leaving more room in your budget for other essentials. Additionally, settling a loan may halt ongoing collection activities, reducing the stress associated with persistent lender communications.
Hidden Downsides to Consider
Despite the immediate relief, loan settlements come with certain hidden downsides. A significant one is the negative impact on your credit score. A settled status on your credit report indicates that you did not pay the full amount owed, which can deter future lenders. Furthermore, the amount that is forgiven in a settlement might be considered taxable income, potentially leading to unexpected tax liabilities.
It is also important to consider the long-term financial implications. While a loan settlement might solve immediate cash flow issues, it does not necessarily resolve underlying financial problems. Consulting with professional legal services, such as those offered by AMA Legal Solutions, can provide you with a broader understanding of how a settlement can affect your overall financial standing.
Seeking Professional Guidance
To make an informed decision, it is advisable to consult with financial and legal experts. At AMA Legal Solutions, our specialists can guide you through the complexities of loan settlements, ensuring that you understand both the immediate benefits and the potential long-term consequences. They can also assist in exploring alternative solutions, such as debt restructuring or refinancing, which might be more advantageous.
Moreover, considering the diverse range of services available at AMA Legal Solutions, such as corporate law and arbitration, you can gain a holistic view of your financial and legal standing. An informed decision involves more than just understanding the terms of the settlement but also anticipating future financial scenarios.
Conclusion: Is a Loan Settlement Right for You?
Deciding whether a loan settlement is the right choice for you involves weighing several factors. A loan settlement can provide a significant reduction in your debt burden, leading to immediate financial relief. However, this decision should not be made lightly, as it may carry hidden downsides that could affect your financial future. It's crucial to understand both the benefits and potential repercussions before proceeding.
One of the primary considerations is the impact on your credit score. Loan settlements typically result in a negative mark on your credit history, which can last for several years. This could make it more challenging to secure new credit or loans, such as a home mortgage or car financing, at favorable terms in the future. If maintaining a strong credit score is important for your long-term financial goals, you may want to explore other options, such as loan restructuring or negotiation with the assistance of professionals from AMA Legal Solutions' Banking and Finance Services.
Additionally, loan settlements might have tax implications. The amount of debt forgiven may be considered taxable income by the Income Tax Department of India, potentially leading to an unexpected tax liability. It's advisable to consult with a financial advisor or legal expert to fully understand these implications. At AMA Legal Solutions, our experts can guide you through these complexities to ensure you are informed of all potential outcomes.
It's also essential to consider your relationship with your lender. Opting for a settlement might affect your ability to borrow from the same institution in the future. Establishing a pattern of settlements may suggest to lenders that you are a high-risk borrower. Thus, if you plan to engage in future borrowing, whether for personal or business purposes, consulting with corporate law experts or arbitration specialists could provide valuable insights into maintaining favorable lender relationships.
Ultimately, determining if a loan settlement is right for you requires a thorough evaluation of your current financial situation, future goals, and potential long-term consequences. Consider seeking professional advice from legal experts who can offer personalized guidance tailored to your specific circumstances. For comprehensive support, reach out to AMA Legal Solutions for assistance in navigating your financial and legal challenges with confidence.
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages





Client Reviews
"Their professional advice on tax implications during my loan settlement was invaluable. AMA Legal Solutions truly cares about their clients."
Ajay Gupta
"The team at AMA Legal Solutions helped me understand the intricacies of loan settlements, protecting me from future financial pitfalls. Highly recommended!"
Priya Sharma
"AMA Legal Solutions provided exceptional guidance through my loan settlement process. Their expertise made a complex situation much simpler."
Rajesh Kumar
"I was worried about the impact of my loan settlement on my future investments, but AMA Legal Solutions provided clear and reassuring advice."
Sneha Patel
"The legal team at AMA was thorough and attentive. They made sure I understood every aspect of my loan settlement agreement."
Vikram Singh
Frequently Asked Questions
Related Articles

RuPay Credit Card on UPI Default & Credit Line on UPI Settlement (2026)
Micro-transactions on RuPay UPI Credit Cards and pre-approved 'Credit Lines on UPI' have triggered a massive wave of 42%+ APR revolving debt traps. Find out if defaulting blocks your personal savings UPI and how to settle RuPay UPI credit dues for 30%–50%.
Read Article
Paytm, PhonePe & BharatPe Daily EDI Merchant Loan Settlement (2026)
Drowning in Equated Daily Installment (EDI) merchant loans where 100% of your daily QR Soundbox collections are auto-swept before you can pay suppliers or rent? Learn how retail shopkeepers and MSMEs legally halt QR sweeps and negotiate a 50%+ OTS.
Read Article
Can Bank or Loan App Remotely Lock Phone for EMI Default? RBI Rules (2026)
An investigative breakdown of RBI's Remote Device Locking Directions—explaining why lenders cannot lock your phone for personal loans, the mandatory 30/60 DPD safeguards on financed devices, the Rs. 250/hour delay penalty, and how to settle device & app loans.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611