Understanding Personal Loan Harassment in India: Your Rights
Learn how to protect yourself from unlawful recovery practices in India.

Anuj Anand Malik
Reviewed by AMA Legal Solutions
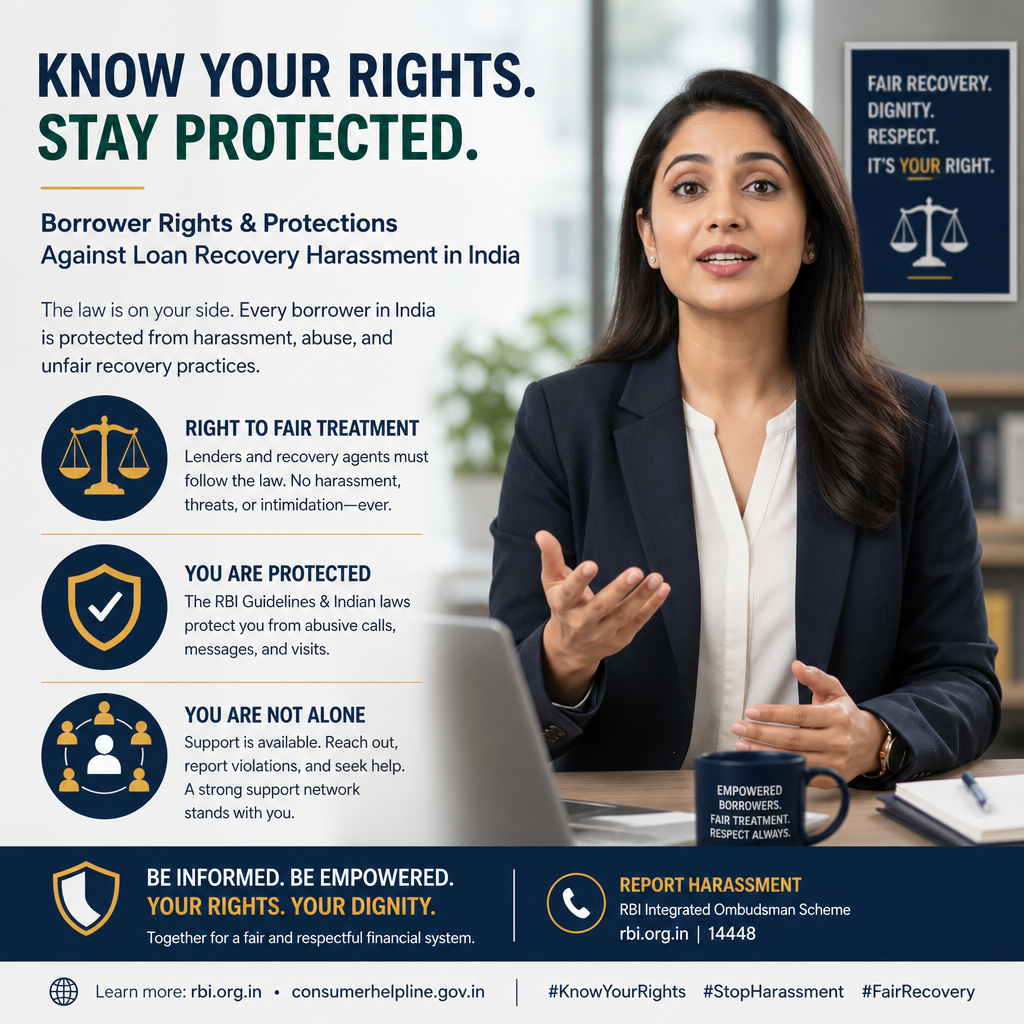
Introduction to Personal Loan Harassment in India
Receiving dozens of phone calls every day from recovery agents can be mentally exhausting. Many borrowers begin to believe that defaulting on a personal loan is a criminal offence or that they may be arrested at any moment. Others fear that banks can seize their property, publicly shame them, or contact their employers to force repayment.
The reality is very different.
In India, defaulting on a personal loan is generally a civil matter, not a criminal offence. While banks and financial institutions have the legal right to recover outstanding dues, they must follow the law. They cannot threaten, abuse, intimidate, or harass borrowers simply because payments are overdue.
The Reserve Bank of India (RBI) has issued detailed guidelines governing how banks and recovery agents must interact with borrowers. Courts across India have repeatedly emphasised that financial institutions cannot violate an individual's dignity while attempting to recover money.
Unfortunately, many borrowers remain unaware of these legal protections. As a result, they often tolerate unlawful behaviour that they are not legally required to endure.
This guide has been prepared to help borrowers understand:
- What legally amounts to personal loan harassment.
- The rights available to borrowers under Indian law.
- What recovery agents can and cannot do.
- RBI guidelines governing debt recovery.
- The legal process after a personal loan default.
- How loan settlements work.
- When legal assistance becomes necessary.
- Practical steps to stop harassment lawfully.
Whether you have missed one EMI or your loan has already entered the recovery stage, understanding the legal framework can help you make informed decisions and protect your rights.
Understanding the Legal Framework: Civil vs. Criminal Matters
In the context of personal loan defaults in India, it is crucial to differentiate between civil and criminal matters. Defaulting on a personal loan is primarily dealt with under civil law. This means the resolution process typically involves civil recovery actions such as legal notices, arbitration, or civil court proceedings, rather than criminal prosecution.
However, borrowers often mistakenly believe that failing to repay can lead to arrest or criminal charges. In reality, criminal proceedings are only applicable under specific circumstances involving fraudulent activities, such as using forged documents or intentional deception to secure the loan.
Key Considerations
- Civil Proceedings: Primarily involve recovery of dues through legal channels like arbitration or civil court, without criminal implications.
- Criminal Liability: Arises only in cases of fraud or intentional deceit; not applicable for ordinary defaults.
- Borrower's Rights: Borrowers have the right to fair treatment and cannot be intimidated or harassed by recovery agents.
- Legal Recourse: Borrowers should respond to legal notices professionally and seek legal advice to navigate disputes effectively.
Understanding these distinctions helps borrowers protect their rights and effectively address personal loan recovery challenges, ensuring they are not subjected to undue harassment or misinformation.
RBI Guidelines on Fair Recovery Practices
The Reserve Bank of India (RBI) mandates that all banks and Non-Banking Financial Companies (NBFCs) adhere to fair recovery practices to protect borrowers from unethical treatment and harassment. These guidelines emphasize the dignity and privacy of borrowers, ensuring that recovery processes do not infringe upon their rights.
Key Principles of RBI Guidelines
- Ethical Conduct: Recovery agents must maintain professionalism and refrain from using abusive or threatening language.
- Authorized Identification: Recovery agents must identify themselves clearly and disclose the bank or NBFC they represent.
- Reasonable Communication: Contact should be made at appropriate times, avoiding excessive or unwarranted calls.
- Privacy Respect: Agents should not disclose debt information to unauthorized third parties like neighbors or employers.
- Legal Compliance: All recovery actions should comply with the legal framework, avoiding coercion or intimidation.
- Grievance Redressal: Lenders must provide a clear mechanism for borrowers to file complaints regarding recovery practices.
These guidelines aim to balance the rights of borrowers and lenders, ensuring that while due amounts are recoverable, the methods employed should not compromise an individual's dignity or privacy. Borrowers are encouraged to report any deviations from these guidelines to the relevant authorities for redressal.
Identifying Personal Loan Harassment: What It Looks Like
Personal loan harassment in India manifests through various unlawful and unethical practices by banks and recovery agents. It is crucial for borrowers to recognize when recovery efforts cross the line into harassment. Key indicators include:
Continuous and Excessive Calls
Receiving an overwhelming number of calls daily can be considered harassment. If you notice persistent calls aimed at causing mental distress, it may be time to take action.
Abusive Language and Threats
Harassment involves the use of offensive, derogatory, or threatening language. Recovery agents must maintain professionalism, and any form of verbal abuse is unacceptable.
False Legal Consequences
Informing borrowers that they will face immediate arrest or legal action for missing EMIs is a scare tactic often used by unethical agents. It's important to understand that defaulting on a personal loan is typically a civil matter.
Public Humiliation
Contacting family members, neighbors, or employers to embarrass the borrower publicly is a form of harassment. Such actions are beyond the legal scope of recovery efforts.
Invasive Home Visits
While recovery agents may visit your home, any behavior that involves intimidation, threats, or unauthorized entry falls under harassment. It is important to assert your rights if faced with aggressive home visits.
Recognizing these signs of harassment can empower borrowers to take appropriate action, ensuring that recovery efforts remain within the bounds of the law.
Common Myths About Loan Defaults and Harassment
Borrowers often make decisions based on misconceptions about loan defaults, which can lead to unnecessary stress and poor financial choices. Here are some prevalent myths and the realities:
Myth 1: Arrest for Non-Payment
- Reality: Defaulting on a personal loan is typically a civil matter in India, not a criminal one. Arrest is generally not a consequence unless there is evidence of fraud or deceit.
Myth 2: Property Seizure by Recovery Agents
- Reality: For unsecured personal loans, assets such as your house cannot be seized without following due legal processes. Collateral is not involved with unsecured loans, so direct seizure is not permissible.
Myth 3: Public Shaming
- Reality: Legally, banks cannot publish or display personal details to publicly shame borrowers. Such actions can lead to legal repercussions against the lender.
Myth 4: Ignoring Calls Will Make Problems Disappear
- Reality: Avoiding communication typically exacerbates issues. It's crucial to engage with lenders, keep records, and address the situation constructively to find a resolution.
Myth 5: Loan Settlement is Unlawful
- Reality: Loan settlements are legitimate and commonly used methods by financial institutions to resolve outstanding debts amicably. Settlements should be documented and understood thoroughly, especially regarding their impact on credit scores.
Borrowers' Rights and Legal Protections
In India, borrowers facing personal loan harassment have several legal protections that ensure fair treatment. The Reserve Bank of India (RBI) mandates that all recovery practices conform to ethical standards, safeguarding the dignity and rights of borrowers.
Key Rights Under Indian Law
- Dignity and Respect: Borrowers must be treated with dignity, and recovery agents are prohibited from using abusive or threatening language.
- Clear Communication: Borrowers have the right to receive information about their outstanding dues in a clear and concise manner.
- Agent Identification: Borrowers can request the identity and credentials of any recovery agent contacting them.
- Written Communication: Borrowers may request all communications in writing to maintain a documented record.
- Grievance Redressal: Borrowers have the right to file complaints through the bank's grievance redressal mechanism if they experience harassment.
RBI Guidelines for Ethical Recovery
The RBI has put forth guidelines that banks and NBFCs must follow, ensuring that recovery efforts are professional and lawful. Violations may lead to regulatory actions, providing borrowers with an added layer of protection.
Understanding these rights helps borrowers navigate recovery processes more confidently and ensures they are treated fairly throughout financial recovery efforts.

Halt Recovery Agent Harassment Legally
What Recovery Agents Can and Cannot Do Legally
Recovery agents play a crucial role in the debt recovery process, but their conduct is strictly regulated to protect borrowers from harassment. Understanding what recovery agents are legally allowed and not allowed to do can help borrowers respond appropriately and protect their rights.
What Recovery Agents Can Legally Do
- Contact Borrowers: They can remind borrowers of overdue payments and discuss repayment solutions.
- Request Payment: Agents can ask for payment and suggest restructuring or settlement options.
- Visit Residences: They may visit borrowers' homes for discussions, provided they do so respectfully and without intimidation.
- Verify Information: Agents can verify borrowers' contact and employment details for recovery purposes.
- Discuss Repayment Plans: Options like revised schedules or settlements can be discussed to resolve defaults.
What Recovery Agents Cannot Legally Do
- Use Abusive Language: Threatening or offensive language is strictly prohibited.
- Threaten Arrest: They cannot threaten arrest for a personal loan default, which is a civil matter.
- Harass Family or Employers: Repeatedly contacting family members or employers to embarrass the borrower is not allowed.
- Enter Homes Forcibly: Agents cannot enter residences without permission or legal authority.
- Fake Legal Notices: Issuing misleading notices that falsely claim legal authority is unlawful.
If recovery agents engage in any improper conduct, borrowers should document the interactions and consider legal recourse or filing a complaint with the bank's grievance mechanism.
Practical Steps to Handle Harassment Effectively
Facing harassment due to personal loan recovery efforts can be distressing. Here are practical steps to manage such situations effectively:
Stay Calm and Document Everything
- Remain calm during interactions and avoid confrontations.
- Keep a detailed log of all calls, messages, and visits, noting dates, times, and agent details.
Verify and Communicate Professionally
- Politely request the recovery agent’s full name, agency, and bank they represent.
- Ask for written communication through email to create a verifiable record.
Know Your Rights
- Understand your rights under RBI guidelines; banks cannot abuse, threaten, or harass you.
- Recovery agents have no legal right to seize property without due process.
Avoid Making Immediate Decisions
- Don't sign any documents without thoroughly understanding their contents.
- Avoid verbal agreements; insist on written confirmation for any settlement or agreement.
Seek Legal Advice
- If harassment persists, consult a banking lawyer for professional advice.
- Legal intervention can help negotiate terms or address unlawful recovery methods.
Following these steps ensures you handle harassment legally and effectively, protecting your rights as a borrower.
The Role of Legal Notices and Arbitration in Loan Recovery
Legal notices and arbitration play crucial roles in ensuring the lawful recovery of personal loans. When a borrower defaults, the initial step involves the issuance of a legal notice. This document serves as a formal demand from the lender, detailing the outstanding amount, the nature of the default, and the time frame within which the borrower should respond or repay. Ignoring such a notice can escalate the situation, potentially leading to arbitration or civil proceedings.
Importance of Legal Notices
A legal notice is not merely a formality; it provides the borrower with the opportunity to resolve the issue before legal proceedings commence. It is a chance to negotiate, explain circumstances, and seek a mutually acceptable repayment plan. Borrowers are advised to respond professionally and consider seeking legal advice to explore their options.
Understanding Arbitration
Many loan agreements include an arbitration clause. Arbitration serves as an alternative to traditional court litigation, offering a faster and less formal resolution process. In arbitration, an independent arbitrator assesses the evidence and issues a binding decision. Borrowers should take arbitration notices seriously and participate actively to ensure their side is heard.
- Legal Notices: Opportunity for negotiation and resolution.
- Arbitration: Quicker resolution than court litigation, governed by the agreement's terms.
Engaging with these processes can prevent further legal complications and facilitate a more amicable settlement of the debt.
Exploring Loan Settlement Options and Strategies
Loan settlement can be a viable option for borrowers facing severe financial hardship and unable to continue with regular EMI payments. Understanding the available strategies can significantly impact the outcome of negotiations.
Evaluate Your Financial Position
Before entering settlement discussions, assess your financial situation realistically. Calculate your total outstanding debt, monthly income, and expenses. This evaluation helps in proposing a settlement amount that is affordable and acceptable to both parties.
Documentation Is Key
Presenting clear evidence of financial hardship strengthens your settlement request. Relevant documents include salary slips, termination letters, medical bills, and any other proof of reduced income or increased expenses. These documents demonstrate your genuine need for settlement.
Negotiate Effectively
- Avoid accepting the first settlement offer. Initial offers are often negotiable.
- Always request written confirmation of any settlement terms.
- Discuss the full implications of the settlement, including any potential impact on your credit score.
Involve Professionals When Necessary
Legal or financial advisors can offer valuable insights into negotiating favorable terms. They can also ensure that all necessary documentation is in place and correctly filed, thus reducing the risk of future disputes.
Taking a strategic approach to loan settlement can lead to a mutually agreeable resolution, alleviating financial pressure while maintaining good faith with lenders.
Real-Life Case Studies and Court Decisions
Understanding how courts have addressed personal loan harassment can help borrowers navigate their own situations effectively. Indian courts have consistently emphasized that while lenders have a right to recover dues, they must do so lawfully and respectfully.
Case Study 1: Continuous Harassment Calls
A government employee was inundated with daily calls from recovery agents due to missed EMIs after losing his job. Initially, he ignored the calls, assuming they would cease. However, the frequency increased, leading him to document each call meticulously and communicate his job loss in writing. This proactive approach led to a structured repayment plan.
Case Study 2: Repeated Employer Contact
A sales executive was distressed when recovery agents began contacting her workplace. She documented these instances and filed a formal complaint with her bank, leading to a cessation of such communications. This illustrates the power of documentation and direct complaints in halting inappropriate recovery practices.
Court Decision: Upholding Borrower Rights
The Delhi High Court has reinforced that recovery efforts must not infringe on the borrower's dignity. In a landmark case, the court criticized recovery agents for public shaming tactics and mandated banks to adhere strictly to RBI guidelines. This decision underscores the judiciary's commitment to upholding borrower rights against coercive recovery methods.
When to Seek Legal Assistance: Practical Advice
Understanding when to seek legal assistance can significantly impact how effectively you manage personal loan harassment. Legal guidance becomes essential in certain scenarios to safeguard your rights and navigate complex situations efficiently.
Instances to Consider Legal Advice
- Receiving a Legal Notice: If you've been served with a legal notice, consult a lawyer immediately to understand its implications and formulate a response strategy.
- Arbitration Proceedings Initiated: Many loan agreements include arbitration clauses. Receiving an arbitration notice necessitates legal advice to navigate this formal dispute resolution process.
- Improper Recovery Conduct: Legal help is crucial if recovery agents engage in behavior such as repeated intimidation, abusive language, or threats. A lawyer can guide you on appropriate legal remedies.
- Complex Settlement Negotiations: High-value settlements often involve detailed agreements. A lawyer can assist in reviewing terms, ensuring clarity, and mitigating risks.
- Multiple Loan Accounts: Managing several loans without a strategic approach can be overwhelming. Legal assistance can help streamline negotiations and documentations for better outcomes.
Seeking legal advice early can prevent escalation and provide clarity on the best course of action. Always prepare your documents in advance to make consultations more productive and focused.
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages





Client Reviews
"AMA Legal Solutions gave me the confidence and legal support to challenge unlawful recovery practices, protecting my dignity and privacy."
Vikram Joshi
"Thanks to AMA Legal Solutions, I could negotiate a fair settlement with my bank. They are knowledgeable and compassionate about borrower rights."
Sneha Patel
"I was clueless about handling unlawful loan recovery calls until AMA Legal Solutions stepped in. Their expertise and support turned the situation around."
Priya Sharma
"The team at AMA Legal Solutions provided professional and timely advice, ensuring I was treated fairly by the bank. Highly recommend their services!"
Anil Mehta
"AMA Legal Solutions helped me understand my rights against unfair loan recovery practices. Their guidance was invaluable in stopping harassment from recovery agents."
Rajesh Khanna
Frequently Asked Questions
Related Articles

RuPay Credit Card on UPI Default & Credit Line on UPI Settlement (2026)
Micro-transactions on RuPay UPI Credit Cards and pre-approved 'Credit Lines on UPI' have triggered a massive wave of 42%+ APR revolving debt traps. Find out if defaulting blocks your personal savings UPI and how to settle RuPay UPI credit dues for 30%–50%.
Read Article
Paytm, PhonePe & BharatPe Daily EDI Merchant Loan Settlement (2026)
Drowning in Equated Daily Installment (EDI) merchant loans where 100% of your daily QR Soundbox collections are auto-swept before you can pay suppliers or rent? Learn how retail shopkeepers and MSMEs legally halt QR sweeps and negotiate a 50%+ OTS.
Read Article
Can Bank or Loan App Remotely Lock Phone for EMI Default? RBI Rules (2026)
An investigative breakdown of RBI's Remote Device Locking Directions—explaining why lenders cannot lock your phone for personal loans, the mandatory 30/60 DPD safeguards on financed devices, the Rs. 250/hour delay penalty, and how to settle device & app loans.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611