Is Loan Settlement Legal? Insights on RBI Guidelines
Exploring the Legality and Process of Loan Settlement in India

Anuj Anand Malik
Reviewed by AMA Legal Solutions
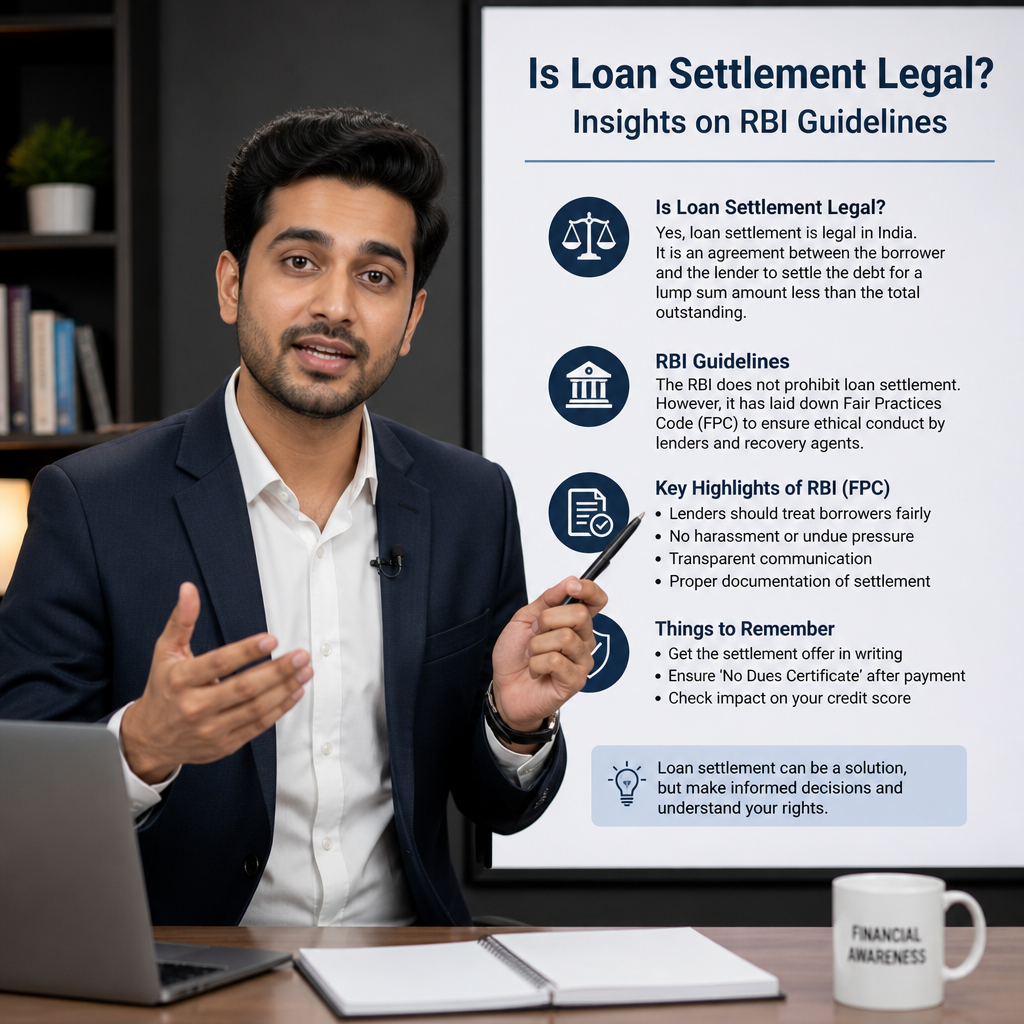
Introduction to Loan Settlement Legality
Loan settlement, a crucial financial recourse for borrowers facing repayment difficulties, is indeed legal under the Reserve Bank of India (RBI) guidelines. It allows borrowers to negotiate with banks to pay a reduced amount in lieu of the total outstanding debt, potentially saving individuals and businesses from severe financial distress. The RBI, the apex financial regulator in India, provides clear directives on how settlements should be conducted, ensuring fairness and transparency for both parties involved.
Typically, loan settlements arise when borrowers are unable to meet their repayment schedules due to unforeseen financial hardships. Banks, recognizing the potential for complete default, may offer settlements as a pragmatic solution to recover a portion of the outstanding amount. It is important to note that while settlements can relieve immediate financial pressure, they can also impact the borrower’s credit score negatively. This is because the settled amount is often less than what was originally owed, reflecting unfavorably in credit records.
The RBI mandates that banks follow certain protocols, such as communicating settlement offers in writing and maintaining a record of all correspondence. This legal framework protects borrowers from arbitrary actions by creditors and ensures that loan settlements are handled in a structured and accountable manner.
Understanding the Legal Framework for Loan Settlement
The legality of loan settlement in India is anchored in the Reserve Bank of India's (RBI) guidelines, which provide a structured approach for resolving non-performing assets (NPAs). Loan settlements are legitimate means by which borrowers can negotiate with banks to repay a reduced amount as full and final settlement of their dues. However, this process is not arbitrary; it is bound by the regulatory framework established by the RBI.
Key RBI Guidelines
- Prudential Framework for Resolution of Stressed Assets: Issued in June 2019, this framework outlines the specific procedures and timelines banks must follow for restructuring loans, including settlement agreements.
- One-Time Settlement (OTS) Schemes: Banks often offer OTS to clear NPAs. These schemes are designed to recover dues in a time-efficient manner, often with concessions on interest rates and penalties.
- Fair Practices Code: Mandates transparency and fairness in dealings, ensuring borrowers are informed of terms, consequences, and alternatives during loan settlement negotiations.
While RBI guidelines provide legitimacy to the settlement process, they also ensure protection for borrowers against coercive recovery practices. Borrowers should be aware of their rights and the specific procedures involved to safeguard their interests during negotiations.
RBI Guidelines: What Borrowers Need to Know
The Reserve Bank of India (RBI) provides clear guidelines regarding loan settlements. These guidelines ensure that the process is conducted fairly and transparently, offering protection to borrowers. It's crucial for borrowers to understand these regulations to navigate the settlement process effectively.
Understanding One-Time Settlement (OTS)
One-Time Settlement (OTS) is a popular method encouraged by RBI guidelines. Under OTS, banks can offer borrowers a chance to settle their outstanding dues by paying a lump sum amount, which is often less than the total amount owed. This can be beneficial for borrowers facing financial stress.
Legal Framework and Borrower's Rights
- Transparency: Banks must communicate the terms of settlement clearly, including any charges or penalties involved.
- No Coercive Practices: RBI strictly prohibits any form of coercion or harassment during the settlement process.
- Written Agreements: A written agreement is mandatory to formalize the settlement, protecting both parties.
Borrowers need to be vigilant about their rights and ensure they receive all communications in writing. Always cross-verify the legitimacy of the offers with the bank's official policies and consult legal experts if necessary.
Staying informed about RBI guidelines can empower borrowers to make informed decisions and potentially negotiate better terms for their settlements.
Legal Rights of Borrowers in Loan Settlement
Borrowers in India have distinct legal rights during loan settlement processes, as outlined by the Reserve Bank of India (RBI). Understanding these rights empowers borrowers to negotiate effectively and avoid undue harassment. Here are key rights every borrower should know:
Right to Fair Treatment
According to RBI guidelines, borrowers are entitled to fair treatment from banks and financial institutions. Recovery agents must adhere to ethical practices and act within legal boundaries, ensuring no coercion or harassment occurs.
Right to Receive Information
Borrowers can request detailed information about their loans, including outstanding amounts, interest rates, and applicable charges. This transparency is crucial for understanding settlement terms and options.
Right to One-time Settlement (OTS)
OTS schemes allow borrowers to settle their loans by paying a lump sum amount, often less than the total outstanding debt. Banks are mandated to communicate these schemes transparently and provide reasonable timelines for acceptance.
Right to Dispute Resolution
If disagreements arise, borrowers have the right to approach the banking ombudsman or consumer courts for redressal. This mechanism provides a platform to resolve disputes without resorting to litigation.
By being aware of these rights, borrowers can navigate the loan settlement process confidently, ensuring their interests are protected and that they engage in fair and legal negotiations with banks.
How Banks Handle Loan Settlements: An Insider's View
When it comes to loan settlements, banks follow a structured approach that aligns with RBI guidelines. Understanding this process can empower borrowers facing financial challenges. Initially, banks classify non-performing assets (NPAs) based on overdue periods. This classification determines the urgency and the level of action required. Generally, when a borrower defaults, the bank's recovery department evaluates the financial status and repayment capacity of the borrower.
Banks often initiate the settlement process by assessing the borrower's total outstanding dues, which include the principal, interest, and any penalties. They then determine a settlement amount, often a reduced figure, that the borrower can feasibly repay. This amount is calculated by analyzing the borrower's financial health, market conditions, and previous repayment history. A key aspect here is the borrower's ability to provide a valid rationale for the default, such as loss of employment or health issues.
During negotiations, banks aim to minimize their losses while providing the borrower with a feasible repayment plan. It's crucial for borrowers to communicate openly and honestly with banks, ensuring all correspondences are documented. Settlements are typically finalized with a 'full and final' settlement letter, confirming the agreed terms. This approach, while beneficial, can influence the borrower's credit score and future borrowing capacity.
Common Misconceptions About Loan Settlement
Loan settlement is often misunderstood, leading borrowers to make decisions that can have long-term financial consequences. Here are some prevalent misconceptions:
Loan Settlement Means Complete Relief
Many believe that settling a loan absolves them entirely from financial obligations. While settlement can reduce the immediate burden, it does not erase the debt in full. Instead, it usually means the lender accepts a reduced amount to close the account, but the settlement is recorded in your credit history, potentially impacting future creditworthiness.
No Legal Implications
Some borrowers think that loan settlement has no legal ramifications. In reality, settling a loan can affect your credit score and might be viewed negatively by future lenders. It is crucial to understand the RBI guidelines and consult with legal experts to navigate these complexities effectively.
All Debts Can Be Settled
Borrowers often assume that any loan can be settled. However, settlement depends on the lender's policies and the specifics of the case. Not all loans are eligible for settlement, and the decision is usually at the lender's discretion, considering factors such as the borrower's repayment history and the loan's outstanding amount.
Settlement is a Quick Process
Contrary to popular belief, loan settlement is not a quick fix. It involves negotiations and legal paperwork, and can take several months to conclude. Proper guidance and understanding of the process are essential to avoid further complications.

Halt Recovery Agent Harassment Legally
Real Scenarios: Loan Settlement in Practice
Understanding how loan settlement works in practice can provide clarity to borrowers. Let's explore a typical scenario. Consider Raj, a small business owner who defaulted on his loan due to unforeseen market downturns. He received a settlement offer from the bank after six months of non-payment, which categorized his loan as a Non-Performing Asset (NPA).
Raj's initial reaction was anxiety, but he sought legal advice. His legal counsel advised negotiating the offer. The bank initially proposed a settlement of 80% of the outstanding principal. Raj, equipped with his financial records, demonstrated his inability to meet this demand and countered with 60%.
This negotiation phase is crucial. The bank, often willing to recover a portion rather than face complete loss, can be flexible. Raj provided evidence of his diminished cash flow and future market projections to support his case.
After a series of discussions, both parties agreed on a 70% settlement. Raj ensured that the agreement was documented, explicitly stating the forgiveness of the remaining debt to prevent future claims.
This process highlights the importance of informed negotiation, understanding RBI guidelines, and documenting agreements. Borrowers should always communicate through written channels, ensuring clarity and legal backing for the settlement terms.
What Borrowers Should Expect During the Settlement Process
Embarking on a loan settlement journey involves navigating several stages, and understanding what to expect can be invaluable. Initially, borrowers should anticipate a thorough evaluation of their financial circumstances by the bank, which includes assessing income, liabilities, and overall repayment capacity. This assessment is crucial in determining the bank's willingness to negotiate a settlement.
Stages of the Settlement Process
- Initial Discussion: Borrowers typically initiate contact with the bank, expressing their challenges in repaying the loan. It is crucial to communicate openly and honestly about financial distress.
- Proposal Submission: After preliminary discussions, borrowers may need to submit a formal settlement proposal. This document outlines their financial position and proposes a feasible settlement amount.
- Bank's Response: The bank will review the proposal and either accept, reject, or counteroffer. This process can take time, and patience is essential.
- Negotiation: If the bank provides a counteroffer, negotiation ensues. Borrowers should be prepared to discuss terms and conditions, aiming for an agreement that is manageable.
- Documentation: Once a settlement is agreed upon, both parties sign a settlement agreement. This legally binding document outlines the terms and protects against future claims.
Throughout the process, borrowers should expect clear communication and documentation. Engaging a professional legal advisor can also help navigate complexities and ensure compliance with RBI guidelines.
Risks and Benefits of Opting for Loan Settlement
Choosing loan settlement is a significant decision, especially for borrowers under financial stress. Understanding the risks and benefits is crucial for making an informed choice.
Benefits
- Debt Relief: Settlement can reduce your debt burden, allowing you to pay a lump sum that is less than the total due.
- Avoiding Legal Action: Successfully negotiating a settlement can halt aggressive recovery actions, including legal proceedings.
- Improved Peace of Mind: Resolving outstanding dues can alleviate stress, allowing you to focus on rebuilding your financial standing.
Risks
- Credit Score Impact: Settling may negatively affect your credit score, impacting future borrowing ability.
- Potential for Negotiation Failure: Not all banks may agree to settlement, and offers can be withdrawn if negotiations are not handled carefully.
- Tax Implications: Forgiven debt may be considered taxable income, potentially leading to tax liabilities.
While loan settlement provides a viable option for debt relief, borrowers must weigh these factors against their personal and financial scenarios. Consulting a legal expert or financial advisor can provide tailored advice, ensuring decisions align with individual circumstances and long-term goals.
Practical Tips for Negotiating Loan Settlements
Successfully negotiating a loan settlement can significantly ease financial burdens. Here are some expert tips tailored to the Indian context to help you navigate the process effectively:
1. Assess Your Financial Position
Before entering negotiations, thoroughly evaluate your current financial status. Calculate your total income, expenditures, and outstanding debts. This enables you to propose a realistic settlement amount.
2. Maintain Open Communication
Initiate a conversation with your lender proactively. Clearly communicate your financial difficulties and express your willingness to settle. Transparency can foster trust and facilitate more favorable terms.
3. Understand RBI Guidelines
Familiarize yourself with the RBI's guidelines on loan settlements. The RBI mandates fair practices, which can be leveraged to ensure that your rights are protected during negotiations.
4. Propose a Lump Sum Payment
Banks often prefer lump sum settlements as it reduces their recovery time and costs. If possible, propose a one-time payment to settle your outstanding dues at a lower negotiated amount.
5. Get Everything in Writing
Ensure all verbal agreements are documented. Written confirmation of the settlement terms prevents future disputes and provides legal protection.
6. Consider Professional Assistance
If negotiations stall, consider engaging a legal expert experienced in banking law. Professionals can provide strategic advice and advocate on your behalf to achieve a favorable outcome.
The Role of Recovery Agents: Legal Boundaries and Borrower Rights
In India, recovery agents play a significant role in the loan settlement process, but their actions are governed by strict legal boundaries as per the Reserve Bank of India (RBI) guidelines. Understanding these boundaries is crucial for borrowers facing financial distress and loan recovery calls.
Recovery agents are appointed by banks to recover overdue payments, but they must operate within the parameters set by the RBI. These include:
Legal Boundaries for Recovery Agents
- Agents must not resort to harassment or intimidation. They should communicate with borrowers in a respectful and civil manner.
- Visits should be conducted at a time and place that is convenient for the borrower, avoiding unreasonable hours.
- Agents are required to carry a valid authorization letter from the bank and a proper identification badge.
- They must abide by any legal notices or injunctions issued by the courts, respecting the privacy and dignity of the borrower.
Borrower Rights
Borrowers have specific rights when dealing with recovery agents:
- The right to be treated fairly and with dignity without being subjected to abusive language or actions.
- The right to request the agent's credentials and verify their association with the bank.
- The right to approach the banking ombudsman or consumer court if they believe their rights have been violated during the recovery process.
Awareness of these rights and legal boundaries empowers borrowers to handle interactions with recovery agents more effectively, ensuring that the process remains lawful and respectful.
Recent Supreme Court and High Court Judgments on Loan Settlements
The legal landscape around loan settlements in India has been shaped significantly by recent judgments. Notably, the Supreme Court in ICICI Bank Ltd vs. Official Liquidator of APS Star Industries Ltd reaffirmed the enforceability of settlements under RBI guidelines, emphasizing that borrowers should receive fair opportunities for settlement negotiations. The court highlighted the non-discriminatory nature of such processes, urging banks to follow a transparent settlement framework.
In a landmark judgment, the High Court of Delhi in XYZ Corporation vs. ABC Bank underscored the importance of adhering to RBI Circulars during settlements. This case emphasized that banks must provide clear justifications for any settlement rejection, ensuring that borrowers are not unduly disadvantaged. The court also pointed out that arbitrary practices by banks could be challenged under consumer protection laws.
These rulings illustrate that while the RBI guidelines provide a framework for loan settlement, judicial intervention remains crucial in ensuring fair and just enforcement. Borrowers facing challenges in negotiating settlements should consider these judgments as important precedents, potentially aiding in legal redress. Such cases highlight the judiciary's role in safeguarding borrowers' rights and ensuring ethical banking practices.
Need Strategic Legal Defense for Your Situation?
Our banking & litigation advocates review your notices, debt liability, and recovery issues under complete advocate-client secrecy.

AMA Legal Solutions
Trusted with a 4.7 Google Rating, over 10,000+ Clients Served, 25,000+ Cases Handled, and more than 40+ Years of Experience in providing strategic legal defense and debt resolution across India.
Our media coverages





Client Reviews
"The expertise of AMA Legal Solutions was invaluable in navigating my loan settlement, making it a smooth experience."
Priya Sharma
"Their knowledgeable team made the complicated settlement process understandable and manageable. Highly satisfied!"
Vikram Deshmukh
"I highly recommend AMA Legal Solutions for their professional handling and deep understanding of RBI regulations in loan settlements."
Anil Kapoor
"AMA Legal Solutions effectively represented my interests, ensuring a fair settlement with my bank."
Sunita Joshi
"AMA Legal Solutions provided excellent guidance through my loan settlement process, ensuring compliance with RBI guidelines."
Rajesh Kumar
Frequently Asked Questions
Related Articles

RuPay Credit Card on UPI Default & Credit Line on UPI Settlement (2026)
Micro-transactions on RuPay UPI Credit Cards and pre-approved 'Credit Lines on UPI' have triggered a massive wave of 42%+ APR revolving debt traps. Find out if defaulting blocks your personal savings UPI and how to settle RuPay UPI credit dues for 30%–50%.
Read Article
Paytm, PhonePe & BharatPe Daily EDI Merchant Loan Settlement (2026)
Drowning in Equated Daily Installment (EDI) merchant loans where 100% of your daily QR Soundbox collections are auto-swept before you can pay suppliers or rent? Learn how retail shopkeepers and MSMEs legally halt QR sweeps and negotiate a 50%+ OTS.
Read Article
Can Bank or Loan App Remotely Lock Phone for EMI Default? RBI Rules (2026)
An investigative breakdown of RBI's Remote Device Locking Directions—explaining why lenders cannot lock your phone for personal loans, the mandatory 30/60 DPD safeguards on financed devices, the Rs. 250/hour delay penalty, and how to settle device & app loans.
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Representation?
Evaluate your defense against recovery agents, notices, or structure your loan settlement directly with Senior Advocates.
Call +91-8700343611